
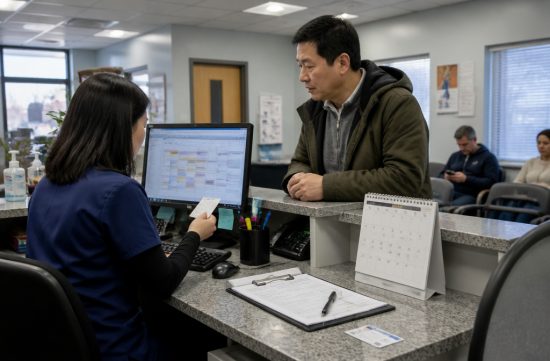
If you had surgery or hospitalization earlier this year, you might have seen the "Deductible met" notification on your insurance app by now. I felt oddly proud when I first saw that screen.
However, it would be a shame to leave this status as is when the new year arrives. Most plans reset the deductible back to zero on January 1.
So today, I want to summarize the treatments that those who have already met their deductible should consider before December. The key is "things you need but have postponed."
First, let's clarify the concept. A deductible is the amount I must pay out of pocket before insurance starts sharing the costs.
Once you exceed the deductible, you move on to coinsurance, which means you share the costs at a certain percentage. It doesn't become free; rather, your share significantly decreases.
The real cap is the Out-of-pocket maximum. Once you reach this, your insurance will cover all in-network services for the remainder of the year.
According to HealthCare.gov, the out-of-pocket maximum for Marketplace plans in 2026 is $10,600 for individuals and $21,200 for families. Plans can set lower limits, but not higher.
High-deductible health plans (HDHP) linked to HSAs have a slightly lower out-of-pocket maximum set by the IRS for 2026, which is $8,500 for individuals and $17,000 for families.
Looking at the numbers, the caps are quite high. Honestly, if you've reached these limits, it has likely been a tough year for you.
Now, let's get practical. The first thing to check is whether your plan is based on a calendar year or a plan year.
Some employer plans reset in July or October, so if that's the case, there's no rush in December. Be sure to check your SBC document or insurance app.
If you have a family plan, you need to check whether you've met the family deductible or just the individual deductible. This will determine if you can group your children's treatments together.
The second thing is postponed specialist visits. Many of you might have been putting off seeing a doctor for persistent knee pain, thinking, "I'll deal with it later." If you have a plan that requires referrals like an HMO, you'll need to schedule a visit with your primary care physician first, so act quickly.
Tests like MRIs or CT scans that your doctor recommended, as well as any remaining physical therapy sessions, are also candidates. These items often apply to the deductible, so the difference at year-end can be significant.
The third item is prescription refills. If you take medication monthly, ask your pharmacy if you can refill a 90-day supply within your plan's limits.
The fourth item is medical devices or aids like CPAP machines. If it's time for a replacement, it might be beneficial to handle it before the year ends.
On the flip side, there are things you don't need to rush. Annual check-ups, vaccinations, and colonoscopies are preventive services that most plans cover without any out-of-pocket costs, regardless of the deductible under ACA guidelines.
However, if you discuss other symptoms during your check-up, it may change to a diagnostic visit, which could incur costs. Many people overlook this aspect.
Here are a few traps to watch out for. Insurance calculates based on the date of service, not the billing date. This means you need to actually receive treatment before December 31.
Tests that require prior authorization can take time. You should start moving now, in early November, to secure appointments for December.
Also, out-of-network hospitals may not be included in this calculation or may be calculated separately. Be sure to confirm whether they are in-network before making an appointment.
If you have an FSA, you should check this as well. According to IRS guidelines, the contribution limit for health FSAs in 2026 is $3,400, and the maximum carryover to the next year is $680.
However, carryover and grace periods are options chosen by the employer. If your company offers neither, any remaining balance will simply disappear, so be sure to ask HR.
If you have parents on Medicare, note that the Part B deductible for 2026 is $283 and resets on January 1. Medicare Advantage plans vary in structure.
After all this, you might think, "Then I should just get everything done." However, I would advise against that direction.
Rushing to get unnecessary tests can take time and may lead to additional tests. This is not beneficial for other members who pay premiums either.
The guideline is simple. Only list tests that your doctor has already recommended or those that you've been concerned about due to symptoms.
What treatments are necessary now varies based on your health status and plan conditions, so be sure to consult with your primary care physician or pharmacist before making decisions.
If I had met my deductible this year, I would check the reset date on my insurance app this week and schedule an appointment with a specialist that I've been postponing.
December is a busy time for hospital appointments due to the holiday season, so it's best to call as soon as you think of it. That's the most reliable way to save.
 ThirstyJjang
 LiveWellFree


 premium |
 The Emperor Must Grow |
 squidogame |
 daddyyo |
 Top Beaches |
 newyorker 101 |
 Encyclopedia of New York and Surrounding Areas |
 Berry News |
 Colorado Lee |
 kiwiii |
 foxtrot83 |
 stiff |
 namico |
 Caribbean |
 dynamico |
 Elastico |
 United States Army |
 Moving Waterfall |
 travelo |
 BOOM BOOM BOOM |
 blues town |
 glenview 89 |
 Mr Oh |
 skiny joe |
 envora21 |
 silverfox |
 nameone |
 bayaa |