
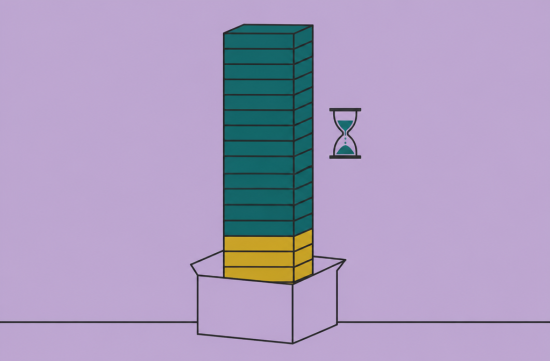
If you check your 401k balance and find that the proportion of company stock funds is much larger than you expected, make sure to read this discussion to the end. There's a tax benefit that disappears the moment you carelessly roll everything over into an IRA before leaving or retiring.
This is the NUA, or Net Unrealized Appreciation. In simple terms, it refers to unrealized gains, and while the name sounds complicated, the structure is surprisingly straightforward.
Typically, when you withdraw money from a 401k, it is taxed at ordinary income tax rates. However, if you take out company stock without converting it to cash, the calculation method splits into two.
The initial purchase price of the stock, or the cost basis, is taxed as ordinary income in the year of distribution. In contrast, the appreciation that has occurred over time, which is the NUA, is taxed at long-term capital gains rates when you sell it later.
The basis for this is found in Section 402(e)(4) of the federal tax code, and the IRS provides guidance on this in Topic 412 and Publication 575. Don't just rely on blog posts; I recommend taking a look at the original documents.
Looking at the numbers makes it clear. For example, let's assume the cost basis is $50,000 and the current market value is $400,000.
Using NUA, only $50,000 will be counted as ordinary income in the year of distribution. The remaining $350,000 will have its taxes deferred until the stock is sold, at which point long-term capital gains rates will apply. This means the amount counted as ordinary income is reduced to one-eighth.
The federal long-term capital gains rates will remain at 0%, 15%, and 20% in 2026. For those in high-income brackets facing the highest ordinary income tax rate of 37%, the difference can be quite significant.
However, this isn't something you can use anytime. The conditions are more stringent than you might think.
First, there must be a reason for distribution. This means a triggering event such as leaving your job, reaching age 59 and a half, or death must occur.
Second, it must be a lump-sum distribution. This means you must empty the entire balance of the plan within the same tax year.
Many people misunderstand this point; it doesn't mean you have to receive everything in a taxable account. You can transfer company stock to a regular brokerage account and roll over the remaining funds into an IRA.
Third, you must receive the company stock as stock. If you sell it within the plan and take cash or transfer it to an IRA, the NUA benefit ends right there.
Honestly, this is the most regrettable part. Many people unknowingly hit the full IRA rollover button when leaving their job and only find out later.
You can check your tax reporting using Form 1099-R. The plan administrator will list the NUA amount in box 6, so make sure to verify that this number is correct after distribution.
There are also points to be cautious about. If you are under age 59 and a half, a 10% early withdrawal penalty may apply to the cost basis portion. However, this penalty does not apply to the NUA gains themselves.
If the stock price increases after distribution, that additional amount is treated separately. You must hold the stock for more than one year after the distribution date to qualify for long-term capital gains rates; selling before that will result in short-term taxation.
Conversely, the gains classified as NUA are always treated as long-term, regardless of how long they were held within the plan. Even if you sell the next day after distribution, it will still be at the long-term rate.
Inheritance considerations are also worth noting. It is understood that the NUA portion does not receive the step-up benefit in basis at death, meaning it does not increase to the market value at that time.
Residents of Washington state should also consider state taxes. Washington imposes a 7% capital gains excise tax on long-term capital gains, and due to a 2025 amendment, an additional 2.9% applies to amounts over $1 million.
Gains within retirement accounts are exempt from this state tax, but how the sale of stocks withdrawn into a taxable account is calculated varies by individual circumstances. It's safest to check with the Washington State Department of Revenue (DOR) or a tax professional.
So, who benefits from this? Those with a low cost basis and significant stock price appreciation, as well as those who can aim for lower capital gains tax brackets after retirement, are typical examples.
On the other hand, if the cost basis is close to the market value, there may be little benefit. The entire cost will be counted as income in the year of distribution, which could even result in a loss.
You should also consider the risk of having too much of your assets concentrated in one stock. Trying to save on taxes by betting your entire retirement on one company's stock isn't a good strategy.
If it were me, I would first ask the plan administrator for the lot-by-lot cost basis of the company stock before leaving, and see if it's possible to choose only the lots with a low basis to take out as NUA.
The remaining stocks with a higher basis and funds would be rolled over into an IRA to continue tax deferral. Note that some plans may not allow lot selection, so be sure to confirm this.
Of course, tax brackets, other income, state taxes, and inheritance plans vary greatly from person to person. The outcomes can differ significantly based on individual circumstances, so be sure to consult with a tax advisor or financial planner before proceeding.
In summary, if you have a 401k with a lot of appreciated company stock, don't hit the rollover button right away. Once you miss the opportunity, it cannot be reversed, so investing just 10 minutes before signing your resignation papers can be well worth it.
 MyHearts
 AjummaIsKing



 memorabilia |

 orvian89 |

 looksee 78 |

 vivavida |

 MEDBIO American Doctor Blog |
 Living in Washington State |
 summita |
 French Macarons |
 kimchi warrior |
 vintago |
 Colorado Lee |
 kiwiii |
 foxtrot83 |
 stiff |
 namico |
 Caribbean |
 dynamico |
 Elastico |
 United States Army |
 Moving Waterfall |
 travelo |
 BOOM BOOM BOOM |
 blues town |
 glenview 89 |
 Mr Oh |
 skiny joe |
 envora21 |
 silverfox |
 nameone |
 bayaa |