
A junior colleague who was working alongside me mentioned that he is moving to another company next month, so I congratulated him. However, during lunch, he suddenly asked me, "Brother, does the money left in the FSA just disappear?"
I was momentarily at a loss for words. Even though I had been using an FSA for several years, I had never considered what would happen upon resignation. It felt unfair to think that money deducted from my paycheck could just vanish, so that evening, I looked into it myself.
To get straight to the point, if you resign, you generally lose the remaining balance in your health FSA. However, there are a few ways to manage this before it happens.
First, let's clarify the numbers. The IRS has set the annual limit for health FSAs at $3,400 for 2026, which is an increase of $100 from last year's limit of $3,300.
If your company has a rollover policy, the maximum amount you can carry over to the next year is $680. This only applies if the company has adopted this policy, and it does not necessarily apply to those who resign.
The key factor is the resignation date. Most plans only recognize medical expenses incurred up to the day you leave. If you go to the hospital the day after your resignation, you cannot use your FSA for that expense.
However, it doesn't mean that everything ends on your resignation date. There is a grace period, during which you can submit receipts for expenses incurred while you were still employed.
This period varies by company. Some give you 90 days after resignation, while others allow a few months after the plan year ends. If you miss this window, your claims will be denied, so you should avoid submitting documents late and losing your money.
There's an interesting rule to note here called the uniform coverage rule.
With a health FSA, you can use the entire elected amount from the beginning of the year, even if you have only contributed a few months' worth.
This can lead to situations where if you exhaust your limit on dental treatment at the beginning of the year and resign in the spring, the company cannot ask you to return the unspent amount. I was surprised to learn that the company bears the loss in this structure.
On the flip side, if you consistently contribute but hardly use the funds, that money is forfeited. It feels a bit unfair that those who contribute diligently end up losing out.
One thing to be cautious about is that while spending is good, it should be for necessary treatments. Hoarding unnecessary items just because you want to use the funds can lead to waste.
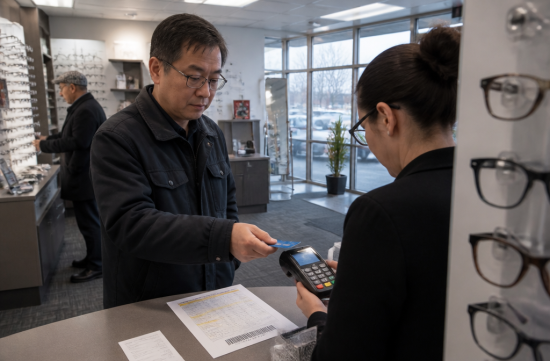
So, if you have a resignation date set, the best approach is to use the funds before you leave. Schedule any overdue dental check-ups, get new glasses or contact lenses, or refill prescription medications.
Many over-the-counter medications and first-aid supplies sold at pharmacies can also be purchased with FSA funds. Just be sure to check the eligibility on your plan management company's list.
The second option is COBRA. Health FSAs are treated as group health insurance, so there may be cases where you can continue coverage under COBRA after resignation.
However, it's not free. You will need to pay the insurance premiums out of pocket, and an additional 2% may be added for administrative fees. The coverage typically lasts only until the end of the plan year.
The calculation is straightforward. If the remaining balance is greater than the premiums you will pay and you have definite expenses, it may be worth considering. Otherwise, there's no compelling reason to keep it, and make sure to check the amounts and deadlines listed in the COBRA notice your company sends.
The dependent care FSA, which covers childcare expenses, is a different story. Starting in 2026, the limit has increased to $7,500 per household.
This account does not have the uniform coverage rule. You can only withdraw what you have contributed, and it is not eligible for COBRA.
However, depending on the plan, some companies allow you to claim childcare expenses with the remaining balance until the end of the year after resignation. You will need to check your company's plan documents for this.
It can be confusing to differentiate between HSA and FSA. HSAs are tied to high-deductible health plans and remain yours even after resignation. They carry over to the next year without the risk of losing funds.
So, first, confirm whether you have an FSA or an HSA. Many people worry unnecessarily because the names are similar.
When re-enrolling in an FSA at a new job, there are also points to be cautious about. While limits are calculated separately by company, since you are essentially contributing twice in the same year, it's better to set an amount that you will actually use.
Checking is not difficult. Just ask your HR department for the plan summary document, commonly referred to as the SPD.
What you need to look for are three things: the run-out period after resignation, whether COBRA is offered, and any rollover or grace period provisions.
Accessing the management company's app to view your current balance alongside the amount you have contributed can also be helpful. Comparing these two numbers will quickly show you which option is more advantageous.
Don't throw away receipts; at least take pictures and keep them. The most important factor when submitting claims is whether the service date is before your resignation date.
If it were me, I would start reviewing my balance a month or two before resignation and schedule any overdue treatments. I would upload all receipts to the app before my last day at work and leave with peace of mind.
Whether it's work or money, cutting corners at the end can lead to problems. Since it's money I earned, I believe it's right to take care of every last cent.
 GarlicGuard
 LunaFlyer

 Casa Mia |
 CA Real Estate |
 Eldorado 88 |
 limestone |
 loran |
 North Dakota Ragdoll Cat Owner |
 reliable |

 US Regional Information Blog |

 My Love Sandra |
 Colorado Lee |
 kiwiii |
 foxtrot83 |
 stiff |
 namico |
 Caribbean |
 dynamico |
 Elastico |
 United States Army |
 Moving Waterfall |
 travelo |
 BOOM BOOM BOOM |
 blues town |
 glenview 89 |
 Mr Oh |
 skiny joe |
 envora21 |
 silverfox |
 nameone |
 bayaa |