
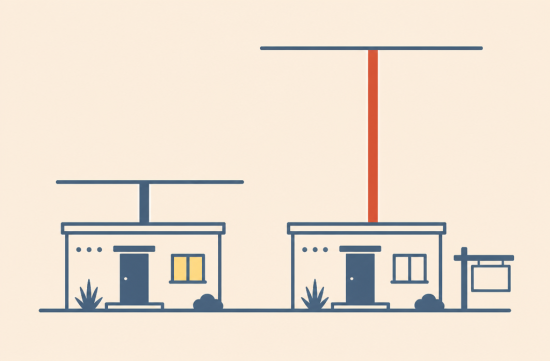
Many people are turning their homes in Las Vegas into rentals and moving to other houses. However, it's common to see inquiries about unexpectedly high property tax bills the following year.
The reason is usually straightforward. The property tax cap in Nevada varies depending on the use of the property.
Nevada law limits how much the property tax bill can increase from the previous year. It's not a system that sets the tax rate itself, but rather a mechanism that caps the increase.
For owner-occupied residences in Clark County, a 3% cap applies. In contrast, properties that are not owner-occupied, such as rental homes, second homes, land, and commercial buildings, are subject to a maximum cap of 8%.
This 8% is recalculated officially every year. The larger of the two values is used: the average increase rate of assessed value over the last 10 years or double the Consumer Price Index (CPI) increase rate. If that value exceeds 8%, it is capped at 8%.
According to the Nevada Department of Taxation's figures confirmed in March this year for the 2026-27 fiscal year, the average increase rate in Clark County was 8.1%. The inflation side was 5.4%, which is double the average annual CPI increase rate of 2.7% for 2025.
Since the larger value is 8.1%, it hits the cap, and the general cap for Clark County is set at 8.0%. The owner-occupied cap remains at 3.0%.
When you place the two numbers side by side, the difference becomes clear. Even in the same neighborhood and for the same size house, if the owner lives there, the tax bill can increase by a maximum of 3% per year, while if it's rented out, it can increase by up to 8%.
This difference may not be felt significantly in one or two years. However, as this difference accumulates over several years, the calculation of rental yield can change quite a bit.
Thus, it is generally correct to say that a rental property does not have a 3% cap as the subject sentence suggests. However, there is one exception that needs to be noted.
Nevada law allows a 3% cap for certain rental properties that meet specific conditions. This applies when the rent received is below the Fair Market Rent set by HUD for the county.
The Clark County Assessor's Office sends rental verification documents to owners of rental properties such as duplexes, triplexes, fourplexes, and apartments every April or May. The rental cap for that year is indicated on those documents.
If all units are rented below the threshold, the owner can fill out the actual rent amount and return it with a signature. Then, they will be reviewed for the 3% cap.
For reference, according to the Nevada Department of Taxation, the Fair Market Rent for Clark County in 2026 is $1,735 for a 2-bedroom unit and $2,413 for a 3-bedroom unit, including utilities.
In the actual review, the standard utility deduction amount is subtracted from this figure. Therefore, the rent received must be slightly lower than these numbers to meet the conditions.
Looking at the recent rental market in Las Vegas, many newly built or well-located 3-bedroom single-family homes often exceed this threshold. Ultimately, it is realistic to view that most investment properties receiving market rent are classified under the 8% cap.
Thus, the choices can be summarized into two options: either charge market rent and accept the 8% cap or adjust the rent to be below the threshold and receive the 3% cap.
In most cases, the loss of monthly rental income from lowering the rent is much greater than the savings on property taxes. When calculated, there are not many reasons to intentionally lower the rent.
However, if you are already renting to long-term tenants at below-market rates, the situation is different. In this case, it is better to carefully gather the verification documents and secure the 3% cap.
Another often overlooked aspect is that if you turn your former home into a rental, you must inform the assessor of this fact.
When applying for the 3% cap, the owner agrees to notify the assessor that the property is no longer their primary residence. Delaying this notification can lead to discrepancies between the actual use and the records, making the process of correcting it much more cumbersome later.
In Nevada, only one primary residence can be designated. If you have moved to a new home, it is normal to register the new home as your primary residence and have the old home transition to the general cap.
Conversely, if you move back into a house that was previously rented out, you must apply for the 3% cap yourself. This benefit does not apply automatically.
If you have objections to the cap decision, you can request a written review from the assessor. The deadline for the 2026-27 fiscal year is June 30, 2027.
You can check what cap has been applied to your property on the tax bill or the property records on the Clark County Assessor's website. If confused, the quickest way is to directly ask the Assessor's Office at 702-455-3882.
The application may vary depending on rental conditions, ownership type, and whether it is under a corporate name. It is recommended to confirm with a tax advisor or the Assessor's Office based on individual circumstances.
Having observed Korean investors for a long time, many tend to carefully consider purchase prices and interest rates while calculating the speed of property tax increases much later. The difference between 3% and 8% is a number that should be included in the yield table from the beginning.
If I were in the position of renting out, I would calculate property taxes based on the 8% cap from the purchase stage. And I would ensure to update the assessor's records whenever the use of the property changes.
 MelonWeather



 |

 Premium Gas Camp |

 CA Real Estate |
 cheesepup |
 breezem |
 Anova US Beauty Information |
 US Legal Consultation on Trials |
 celion78 |
 vegas mom |
 sweetpop |
 California Kangaroo |
 zanero |
 station |
 Static |
 Star Way |
 American Blog Forge |
 MMORPG Games |
 Then you must be spring |
 Spicy Immigration Life |
 zenvor16 |
 The 2000 |
 toclick |
 wexlin84 |
 Hairy Poppins |
 daisypat |
 Taco Bell Candy Note Blog |
 MintO |
 My Town My Way Blog |
 New Mexico Friends MAX |