
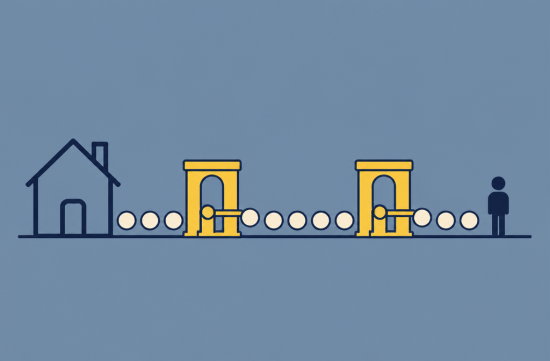
A while ago, a colleague shared a concern over lunch. His aunt, who lives in Maryland and has no children, plans to leave her house to him.
However, he heard from others that Maryland taxes twice, and he asked if that was true.
To put it simply, that's partly true. I was skeptical at first, but after looking into it, I found it to be accurate. Maryland is the only state in the U.S. that levies both estate tax and inheritance tax.
That said, not everyone pays both taxes. It completely depends on who is leaving the assets, who is receiving them, and how much is involved. In reality, most families either pay neither or only one of the two taxes.
First, let's clarify the terminology. In Korean, both are referred to as inheritance tax, which can be confusing.
Estate tax is a tax on the total assets of the deceased. It is paid from the estate before being distributed to the heirs.
Inheritance tax, on the other hand, is based on the recipient. Depending on who receives the assets, there may or may not be a tax.
Let's start with Maryland's estate tax. Since 2019, the exemption amount has been set at $5 million per person, and the maximum rate of 16% applies to amounts exceeding this threshold.
The filing and payment are handled by the Comptroller of Maryland, and it must be paid within 9 months of the date of death. It's important not to miss this deadline, especially when dealing with the chaos of settling an estate.
If you are married, portability applies. The surviving spouse can inherit any unused exemption amount from the deceased spouse, allowing for a combined maximum of $10 million if conditions are met.
One surprising aspect is that the federal estate tax exemption is $15 million per person starting in 2026, while Maryland remains at $5 million.
This means that a family could owe estate tax in Maryland while paying nothing at the federal level.
In neighborhoods where home values have risen significantly, combining a house, retirement accounts, and life insurance could mean that $5 million is not as far-fetched as it seems.
Now, let's discuss the inheritance tax. Maryland's inheritance tax has a flat rate of 10% on the amount received, and it is processed through the Register of Wills in each county and Baltimore City. The key factor is who the recipient is, regardless of the size of the estate.
Fortunately, most close family members are exempt. This includes spouses, children, grandchildren, parents, grandparents, and siblings.
The exemption for siblings is a significant advantage. In neighboring Pennsylvania, inheritance tax is applied to siblings as well.
Conversely, if a niece, cousin, friend, or non-relative receives assets, a 10% tax applies. This was exactly the case for my colleague. If his aunt's house is worth $500,000, he would owe $50,000 in taxes.
If the total inheritance for one person is $1,000 or less, this is also exempt. While not a major detail, it's good to know.
So when do you actually end up paying both taxes? It occurs when the estate exceeds $5 million and the heir is a non-exempt person like a niece or friend.
There is a provision that somewhat alleviates double taxation. The amount paid in inheritance tax can be credited against the estate tax calculation.
So, it's not a simple case of taxes stacking on the same money. However, the calculations do become quite complex.
When you consider both sides of the argument, it makes sense. Supporters argue that it provides necessary revenue for state finances and only affects a small portion of the wealthy.
Opponents point out that retirees are leaving for states like Florida that have no inheritance taxes due to the tax burden. Both arguments have merit.
Personally, I find it disappointing that the $5 million exemption does not keep pace with inflation. Over time, even middle-class families who were originally not affected could find themselves caught in this tax.
I told my colleague that if his aunt's estate is below $5 million, he doesn't need to worry about estate tax, and he should only calculate the 10% inheritance tax as a nephew.
Additionally, I advised him that the tax implications can vary significantly based on how assets are transferred, so it's best to plan ahead.
However, since the application can differ greatly depending on individual circumstances, it's essential to consult a Maryland estate planning attorney or tax professional for actual planning.
In summary, there are three key points: estate tax is 16% on amounts over $5 million, inheritance tax is 10% for non-exempt heirs, and direct family members and siblings are exempt from inheritance tax.
If you have parents or relatives in Maryland, I recommend discussing this with your family at least once. I wouldn't want to put it off.
 PuddingLover


 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 AliAluAlo Blog |
 sweetfox |

 Good Karma |
 USA Business News |
 frostpup |
 Star Way |
 American Blog Forge |
 MMORPG Games |
 Then you must be spring |
 Spicy Immigration Life |
 zenvor16 |
 The 2000 |
 toclick |
 wexlin84 |
 Hairy Poppins |
 daisypat |
 Taco Bell Candy Note Blog |
 MintO |
 My Town My Way Blog |
 New Mexico Friends MAX |
 Hajiwon Blog Hair Salon |
 Wicked - Fireyo |
 Seattle - Emerald City |
 new noah |
 xylora |