
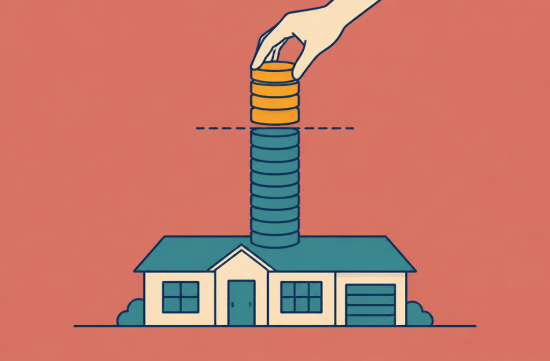
These days, I often hear people say they plan to sell their homes and move to a smaller place when they retire. However, when they actually sit down to calculate, they all seem to hit a wall. The rising home prices make it hard to gauge how much capital gains tax they might owe.
To get straight to the point, as of 2026, if you sell a residential property, couples filing jointly can exempt up to $500,000 in capital gains, while single filers can exempt up to $250,000. Only the amount exceeding these limits is subject to tax.
This is part of Section 121 of the Internal Revenue Code, commonly referred to as the Section 121 exclusion. The conditions are outlined in IRS Publication 523.
The requirements are straightforward. You must have owned the home for at least two of the last five years and lived in it for at least two years. Additionally, you cannot have used this exclusion for another home in the last two years.
For couples to qualify for the $500,000 exemption, at least one spouse must meet the ownership requirement, and both must meet the residency requirement. Many people find this part confusing.
Honestly, what surprises me the most is that this figure has not changed since it was set in 1997. It is not indexed for inflation at all.
Considering how much home prices have skyrocketed in Southern California, it becomes clear. If you bought a home in the 90s or early 2000s, exceeding a $500,000 gain is more common than you might think.
So, what happens if you exceed the limit? The federal long-term capital gains tax rates are 0%, 15%, and 20%. Since you have owned the home for more than a year, these rates apply.
For couples filing jointly in 2026, the 0% rate applies to taxable income up to $98,900. The 15% rate applies up to $613,700, and anything above that is taxed at 20%.
But that's not all. There is also a 3.8% net investment income tax. This applies if your modified adjusted gross income exceeds $250,000 for couples or $200,000 for singles.
Fortunately, the gains exempted under Section 121 do not count toward this 3.8% calculation. Only the amount exceeding the exemption limit is subject to this tax.
California has even stricter rules. The state also recognizes the $500,000 exemption, but any gains above that are taxed as regular income. The tax rate ranges from 1% to a maximum of 13.3%, depending on income.
The key point is that there are no special capital gains tax brackets like at the federal level. Therefore, even for the same gain, California residents feel a much larger tax burden.
Let's consider a simple example. Suppose a couple buys a home for $300,000 and sells it for $1,000,000, resulting in a gain of $700,000. After subtracting the $500,000 exemption, the taxable amount is $200,000.
If this $200,000 falls entirely within the federal 15% bracket, the federal tax would be $30,000. If combined with other income, it could push them over the $250,000 threshold, triggering the additional 3.8%, plus California state tax.
So, it's essential to look for ways to reduce the gain. The first step is to accurately determine the basis, or acquisition cost.
The basis includes not just the original purchase price. You can also add costs for improvements that increase the home's value, such as a new roof, additions, or kitchen remodels.
Additionally, you can deduct real estate agent commissions and closing costs from the gain. If you don't have receipts, it can be hard to get these recognized, so start gathering your renovation records now.
The second way is if you have lost a spouse. If you sell the home within two years of your spouse's death and have not remarried, you can still claim the $500,000 exemption on your own.
If you miss this two-year window, the exemption drops to $250,000. I'm not saying to rush through your grief, but it's important to be aware of this deadline.
The third option is inheritance. If you pass the home on without selling it, there is a step-up basis rule that allows the acquisition cost to be reset to the market value at the time of inheritance. In community property states like California, this effect can be even more significant.
However, this involves estate planning, living trusts, and property tax issues, so it shouldn't be taken lightly. The outcomes can vary greatly depending on personal circumstances, so be sure to consult a tax advisor or estate attorney.
You may have heard about a bill proposing to eliminate capital gains tax when selling a home. It's the No Tax on Home Sales Act, introduced in the House in July 2025, bill number H.R. 4327.
However, nothing has passed so far. If you sell your home in 2026, the existing $250,000 and $500,000 rules will still apply. Relying solely on the bill and delaying your sale could be risky.
Personally, I believe it makes more sense to index the limit for inflation rather than eliminating it entirely. Unlimited exemptions would benefit high-value homeowners and widen the gap with those who do not own homes.
That said, it doesn't mean the limit being unchanged for nearly 30 years is normal. The structure where an average retiree who has lived in one home their whole life pays taxes due to inflation definitely needs to be addressed.
In summary, first check if you have owned and lived in the home for two years. Then calculate the actual gain after deducting the basis and selling costs.
If that number is under $500,000, you likely don't need to worry. If it exceeds that, it's time to consider whether you can reduce other income that year or if inheritance might be a better option.
If I were in your position, I would start organizing receipts at least six months before listing the property and run a simulation with a tax advisor. After all, this is a decision that could involve tens of thousands of dollars.
 LAChocoBear


 Texas Real Estate Blog |
 zentar |
 seouljung |
 AliAluAlo Blog |

 CA Real Estate |
 San Gabriel Mountains |
 Choi Cho |
 some fame |
 Static |
 Star Way |
 American Blog Forge |
 MMORPG Games |
 Then you must be spring |
 Spicy Immigration Life |
 zenvor16 |
 The 2000 |
 toclick |
 wexlin84 |
 Hairy Poppins |
 daisypat |
 Taco Bell Candy Note Blog |
 MintO |
 My Town My Way Blog |
 New Mexico Friends MAX |
 Hajiwon Blog Hair Salon |
 Wicked - Fireyo |
 Seattle - Emerald City |
 new noah |