
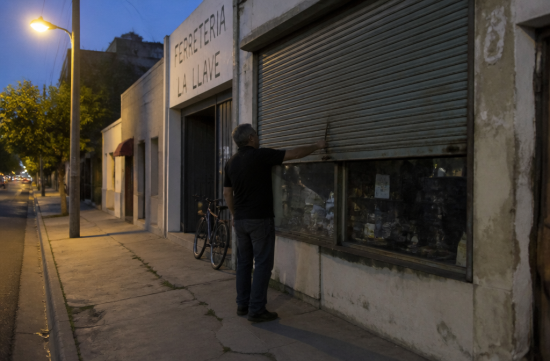
I recently heard that a friend who had been running their own store in the neighborhood for several years has returned to a company. I thought they had closed down due to poor sales, but when I asked, they said business was actually doing reasonably well.
Honestly, when I first heard that, I was surprised. It didn't seem plausible that someone would easily give up a store they had invested years into.
However, as I met more people in similar situations, I realized this wasn't just a unique case. Despite different industries and ages, their reasons were surprisingly similar.
When gathering stories from those who returned to employment after being self-employed, several overlapping reasons emerged. Broadly, they can be categorized into financial issues and physical and mental health concerns.
The first issue that comes up is the burden of health insurance premiums.
As of 2026, if you enroll in a one-person plan through the government marketplace without subsidies, it costs about $625 per month on average.
With the expansion of subsidies ending by the end of 2025, many have seen their actual out-of-pocket insurance costs nearly double.
When working for a company, the employer covers half of the costs, so it's hard to grasp how much it really is. Only when you have to pay it all yourself do you truly feel the weight of that expense.
If a spouse can get family insurance through their job, that helps somewhat. But if both are self-employed, they bear the full burden together.
The tax structure is also cited as a significant reason. Self-employed individuals must pay 15.3% in self-employment tax, which includes Social Security and Medicare taxes.
For employees, the employer covers half of this, and only the remaining half is deducted from their paycheck. Many people only realize this difference when they receive their tax bill.
Based on an annual income of $100,000, self-employed individuals end up paying about $7,065 more in taxes than employees.
Not many people calculate this figure before starting a business. It's common to set sales goals and push tax considerations to a later date.
The stress of fluctuating monthly income is something you only understand through experience. During my salaried days, I took for granted the comfort of receiving the same amount on the same day each month; it's only after leaving that I realize how reassuring that was.
Retirement planning is another crucial aspect that cannot be overlooked. When working for a company, you can at least expect 401(k) matching, but if you're running your own business, you have to manage that on your own.
To handle it alone, you need to find and contribute to an IRA or personal retirement account, but realistically, the immediate pressure to meet sales often pushes retirement savings to the back burner.
With rising rent and labor costs, many express that their profit margins are not what they used to be. Even if they try to endure by taking out loans, the current interest rates make the burden of repayment a significant concern.
The mental exhaustion is also a considerable factor. The weight of managing employees, worrying about sales, and dealing with customers falls solely on the owner throughout the day.
Experiencing the reality of having no one to open the store for you when you're sick can also be surprisingly impactful.
According to data from the Bureau of Labor Statistics, 20.4% of new businesses close within a year. If you extend that to five years, the rate rises to 49.4%.
This means that nearly half of them shut down, indicating that self-employment isn't uniquely unlucky; it's just the inherent probability.
Therefore, choosing to return to employment shouldn't be viewed solely as a failure. If it's a decision made after careful consideration of the numbers, it's likely a wise choice.
Many people are also worn out from a lifestyle that doesn't allow for weekends or holidays. Even on days when the store is closed, their minds are often filled with worries about the business.
However, re-entering the job market isn't necessarily easy. Older individuals may feel barriers right from the application stage.
Many struggle with how to explain their self-employment experience on their resumes. They often worry about being misunderstood as having gaps in their employment history.
Fortunately, more companies are beginning to value that experience as problem-solving skills or responsibility.
So, what's the conclusion? If you ask how to proceed, the answer is surprisingly simple.
Before starting a business, it's essential to calculate insurance premiums, taxes, and retirement savings to establish a minimum sales threshold.
Rather than assuming government subsidies will continue, it's safer to base your calculations on when they will end.
Setting a timeframe of one or two years for how long you can sustain yourself with your family is also a good strategy.
If you're already in business, I recommend honestly assessing your numbers right now. Relying on intuition versus verifying with numbers is a completely different matter.
Whether it's self-employment or re-employment, there's no definitive answer. Ultimately, it's about objectively evaluating your situation through numbers and choosing the right path for yourself.
 MacaronMaker


 coloradoman |
 pintos |
 mapsina |
 Mr. Largo |
 Victory 1988 |
 Anna Life |
 Spaghetti Flying Religion |
 Sugar Cream Door Bulletproof Noodles |
 Round and Round Children's Song Kingdom |
 My Love DS |
 Healthy Local Fresh Information |
 molten |
 Way to easy |
 intact |
 Always Dreaming of Big Success |
 happy 9 |
 Park M.Y. |
 tredon |
 Poppin News |
 metsoo |
 dewyo |
 Casa Mia |
 Asparagus Blog |
 dorange |
 hiddenkong |
 some fame |
 Godory Life |
 Lime Juice |
 French fries |
 Rynex |