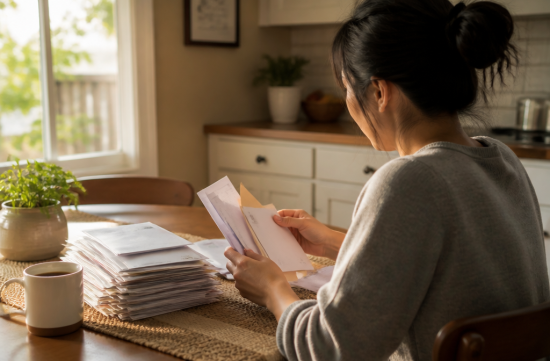
Last month, I was shocked to find an old hospital bill stuck in my mailbox. It was just a forty-dollar bill that I thought was no big deal, but it turned out to be on the verge of going to collections.
Many people think small bills are insignificant, but the impact on your credit score can be greater than you realize. I found out that the moment a collection account is registered, your credit score can drop by over a hundred points. Regardless of the amount, payment history accounts for thirty-five percent of your score, so even a small bill can leave a significant mark if it goes to collections.
Typically, open accounts like credit cards or medical bills go to external collection agencies after being overdue for ninety to one hundred eighty days. Credit card companies write off debts after one hundred eighty days, while installment loans like car payments have a threshold of one hundred twenty-one days. However, keep in mind that credit bureaus can report a debt after just thirty days of delinquency, so your credit score can be affected well before it goes to collections.
It's not just medical bills. Small bills like gym cancellation fees, library late fees, and cable bills can also go to collections. The amount doesn't matter when it comes to your credit score.
So how can you prevent this in advance? I always recommend that when you receive a bill, you should call right away. Whether it's a hospital or a credit card company, reaching out early to request a payment plan can lead to more flexible arrangements than you might expect. Especially with medical bills, there's often more room for negotiation before they go to collections.
There's one more thing to keep in mind regarding medical bills. Although federal regulations were invalidated by a court last year, the three major credit bureaus—Equifax, Experian, and TransUnion—still have policies that do not report unpaid medical collections under five hundred dollars, and they do not reflect paid medical collections regardless of the amount. New medical bills have a grace period of three hundred sixty-five days. However, since this is not a law but an industry self-regulation, it's wise to remember that it could change at any time.
If a collection agency has already contacted you, don't panic. Send a debt validation request within thirty days based on the written notice you received. If you dispute it in writing within this period, the collection agency must stop collection activities until they verify the debt. It's better to send this via certified mail rather than just a phone call, as it serves as solid evidence later on.
I personally try to stick to the principle of not ignoring a bill more than once. Even if I miss the first notice, I make sure to check before the second notice arrives. Just following this practice can significantly reduce the chances of going to collections.
In fact, the issue with small bills is often more about the complexity of the billing system than individual negligence. Still, developing habits to manage your bills is ultimately the most reliable method. Simple practices like not leaving your mailbox empty for days, setting up automatic payments while ensuring you check your balance, and reviewing a free credit score service at least once a month can be sufficient.
Ultimately, the reason small bills are scary is not the amount but the time they are left unattended. Take a moment to check your mailbox today, and if you have any overdue bills, make that call right now. That small action can protect your credit score for years to come.


 Anna Life |
 JESIKYEOALBA BLOG |
 Dad's Tribute TC |
 Glow Yo |
 U.S. Retirement Pension Information |
 AH LALA |
 Montgomery Mom |
 GOGO SING |
 ness 6 |
 SteelOrbit |
 Puddle Puddle |
 Arizona Cowboy |
 macaronpop |
 marydock |
 peachpanda |
 U.S. College Admission Information |
 Fruitop |
 Exploring American Life Information |
 sing sing |
 ORAVEZIN Oppa |
 Lego My Ego |
 logger |
 Conflite Teacher |
 summita |
 Ari Songhan American Immigration Life |
 marketbox |