

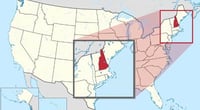
The monthly cost for full coverage car insurance in New Hampshire is $127. The national average is set at $244.
According to NerdWallet's 2026 analysis, Wyoming ranks first for the cheapest car insurance in the U.S. at $1,148 per year.
New Hampshire follows with an annual cost of $1,559, just behind Vermont and Maine.
New Hampshire consistently ranks among the cheapest states in various surveys.
It's interesting to wonder why it's so affordable.
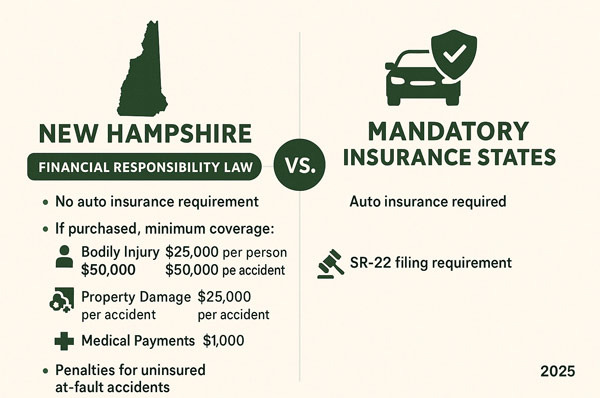
New Hampshire is known as one of the few states that does not legally require most drivers to carry car insurance.
Instead, drivers must prove their financial responsibility, meaning they need to demonstrate their ability to cover damages in the event of an accident.
If they fail to do so, their license and registration may be suspended, and they might need to file an SR-22 certificate.
If you do purchase insurance, the minimum liability limits are $25,000 per person, $50,000 per accident, and $25,000 for property damage.
This is commonly referred to as 25/50/25.
The New Hampshire Insurance Department FAQ states that car insurance issued in this state includes at least $1,000 in medical payment coverage.
Uninsured motorist coverage is also often included, so it's a good idea to check your policy to see what's covered.
I want to make one thing clear: I do not support dropping insurance just because it's not mandatory.
Just one slip on a snowy road that damages someone else's car can cost more than several years' worth of insurance premiums. Saving money should not come at the expense of safety.
Insurance premiums vary significantly based on age, driving record, vehicle type, and where you live.
So how can you lower your already low premiums even further?
The first step is to compare quotes. Even with the same driver and vehicle, prices can vary significantly between companies.
For example, Insurify introduced Progressive as the lowest price in the Concord area at $43 per month, while LendingTree listed Safety Insurance as the lowest full coverage option at $86 per month. The fact that different sites have different top picks shows the importance of comparing directly.
The second step is adjusting your deductible. Raising your deductible can lower your premium, so if you have some emergency funds, it might be worth considering.
The third step is bundling discounts. Many companies offer discounts if you have your home or renters insurance with them.
The fourth step is mileage. Nowadays, with fewer commutes, you might be driving less. Simply reporting your annual mileage can change your quote.
The fifth step is using an app to track your driving habits. If you have fewer hard stops and speeding incidents, you may qualify for discounts, but if you're concerned about privacy, be sure to read the terms carefully.
The sixth step is to evaluate whether collision and comprehensive coverage are still necessary for older vehicles. If the cost of coverage feels higher than the value of the car, it might be time to reconsider.
Finally, ask directly about available discounts. Discounts for defensive driving courses, accident-free periods, and automatic payments can sometimes be overlooked if you don't mention them.
However, be cautious about minimizing your liability limits just to save money. In the event of a serious accident, $25,000 may not be sufficient.
A few phone calls and online quotes should be enough. I try to mark my calendar a couple of months before renewal to compare options.
 JiRunningMan

 Soy Angelino |
 SKy Face |
 gleeful |
 forevergee |
 mortrix |
 New Kids Young |
 Living in America and Writing Essays |
 Information on All Regions of the United States |
 ovelion |
 zen zeng |
 loveyom |
 Coastal city |
 Spaghetti Flying Religion |
 My Town My Way Blog |
 holy cow |
 endone |
 starline |
 Where is a really nice neighborhood? |
 Real Estate |
 Forest Gump |
 Real Estate Investment Korean American |
 Dollydori, Lover of Movies |
 dmzline |
 travelo |
 American Food Information & Calories |
 Splendid Mission |
 sparklingo |
 Watch Walker |
 autumn |