
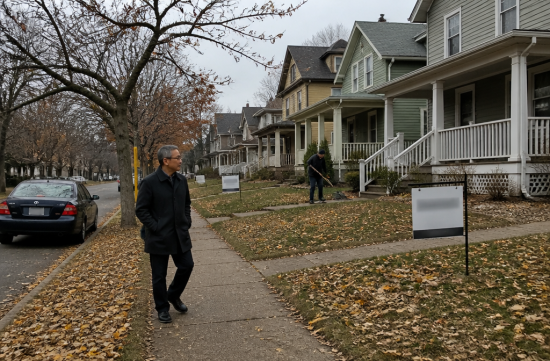
Although October has ended, the sales statistics for October have not yet been released. The Minnesota REALTORS monthly data is typically published in mid-next month, so the most recent transaction indicators available are the confirmed September figures as of October 12.
Therefore, this article will summarize the September transaction indicators, October rental prices, and October mortgage rates. Please keep in mind that the reference points differ.
To get straight to the point, prices are mostly stable, but inventory has definitely increased. More sellers are entering the market while the pace of buyers has slowed, creating a typical pause in the market.
For the 16-county Twin Cities metro area, the median transaction price in September was $395,000. This represents a 1.3% increase from a year ago, so it is essentially considered stable.
In the same month, closed sales totaled 4,049, down 3.1%. Pending transactions, which are in the contract stage, numbered 3,541, a decrease of 11.7%. This figure is noteworthy as it serves as an early indicator of closed transactions for October and November.
On the other hand, inventory is piling up. The metro inventory stands at 12,411 homes, an increase of 11.2%, and the absorption period has lengthened to 3.2 months compared to a year ago.
The average time homes spend on the market has also increased by 9.1% to 48 days. Sellers received about 97.7% of the listing price, indicating a significant departure from the bidding wars seen in previous years.
Now, let's compare Minneapolis and St. Paul side by side. The two cities are separated by a river, but this fall's trends have shown quite different patterns.
The median transaction price in Minneapolis for September was $350,750, up 0.2%. Closed sales increased to 352, a rise of 2.6%.
In St. Paul, the median price dropped to $299,950, down 1.2%, and closed sales fell to 222, down 5.9%. St. Paul has seen a decline in both price and transaction volume.
New listings tell a different story. Minneapolis saw a decrease to 562 listings, down 1.1%, while St. Paul experienced an increase to 392 listings, up 6.2%.
In terms of inventory, Minneapolis has 1,136 homes, up 10.7%, while St. Paul has 672 homes, up 12.9%. The absorption periods are 3.4 months for Minneapolis and 3.1 months for St. Paul.
The market stay duration was 55 days for Minneapolis and 42 days for St. Paul. St. Paul, with its lower prices, is still selling faster.
In summary, Minneapolis is maintaining prices while transactions continue, whereas St. Paul is seeing an increase in inventory with slightly declining prices. Even within the Twin Cities, there seems to be a bit more room for negotiation in St. Paul.
Now, let's move on to rentals. The November report from Apartment List reflects October prices, showing the overall median rent in Minneapolis at $1,454.
When broken down by bedroom count, one-bedroom units average $1,313, while two-bedroom units average $1,699. This represents a 0.9% decrease from the previous month and a 2.4% increase from a year ago.
St. Paul's median rent is $1,384, making it one of the lowest in the metro area. St. Paul also saw a 0.9% decrease over the month.
The overall median rent in the metro area was $1,532, while the national median was $1,384. Minneapolis sits slightly below the metro average but a bit above the national average.
From fall to winter, moving demand typically decreases, so it's common for rents to dip slightly month-to-month. However, annual trends still show increases, making significant reductions unlikely during lease renewals.
This fall's market weight has actually been influenced by interest rates. According to Freddie Mac's weekly survey, the average rate for a 30-year fixed mortgage was 6.65% on August 20, but it rose to 7.40% by October 8 and 15.
It then slightly decreased to 7.32% on October 22 and 7.24% on October 29, but these levels remain significantly higher than summer rates. It makes sense to look at this as a backdrop for the double-digit decline in pending transactions.
When interest rates rise by nearly 0.6 percentage points, the price of homes that can be managed with the same monthly payment drops noticeably. Thus, while the price tags remain the same, fewer people are signing contracts.
So, which is better: buying now or waiting? From a buyer's perspective, it is clear that the current market, with ample inventory and time to negotiate, is favorable.
There is now more room to request closing cost assistance or repair credits than in the past. However, given the burden of interest rates, it's important to remember that plans to refinance later if rates drop are not guaranteed.
For investors looking for rental income, the calculations are tighter. Matching cash flow with Minneapolis rental levels at a 7% interest rate is challenging, while areas like St. Paul with lower purchase prices are relatively less burdensome.
If you are preparing to relocate from another state, I would recommend renting for the first year to experience the neighborhood firsthand. The current slight decline in rents month-to-month makes it a reasonable time to negotiate lease terms.
In my opinion, there is no rush to make a decision, nor is there a reason to sit back and wait. If you find a home you like, it would be wise to negotiate calmly on price and terms, considering the interest rate burden.
The October sales statistics will be posted on the Minnesota REALTORS website in mid-November. Once the numbers are available, we will revisit whether the decrease in pending transactions has led to a real decline in closed sales.
 GlowHeadAnne
 midnightroadwalker1949



 Choco Choco Star |

 gentle |

 neapolis |

 moo moo |
 ultron78 |
 U.S. Weather Bureau News |
 marydo |
 Minnesota Lakes and Clouds |

 Minnesota Sonata N |
 See It |
 memorabilia |
 H Leader |
 Carolina border |
 xylora |
 linex |
 Victory 1988 |
 washington mom |
 Deep South Mississippi |
 moomoon |
 hexora |
 jammybear |
 chiobase |
 jondol |
 US Regional Information Blog |
 tredolo |
 panda express |
 luido |
 norazoo |