
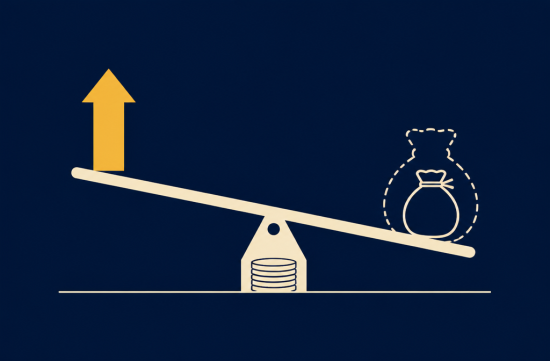
These days, I've been hearing a lot about parents' pensions from those around me. They received a retirement packet at work, which asked them to choose between a lump sum payment or monthly payments for life.
However, I was surprised to hear that the lump sum amount this year is lower than the estimate they received last year for the same pension. I thought the company had reduced it, but it turns out the culprit was the interest rate.
Today, I will explain this structure as simply as possible, step by step. If you have a defined benefit (DB) pension from your company, I hope you read this at least once.
First, let's start with the basics. A lifetime annuity is a method of receiving a fixed amount of money every month until death after retirement.
A lump sum is when you receive the present value of all those future monthly payments in one go. The key point is this present value calculation.
When converting future money into today's money, a discount rate, or interest rate, is applied. The higher the interest rate, the smaller the future dollar amount is calculated in today's terms.
So, when interest rates rise, the lump sum amount decreases even though the monthly annuity remains the same. The point is that the amount received monthly does not change.
Now, what interest rate is used? Private company pensions calculate the minimum lump sum amount based on three segment rates announced monthly by the IRS according to Section 417(e) of the tax code and the IRS mortality table.
The first segment applies to money received within five years, the second to money received between five and twenty years, and the third to money received after twenty years.
When looking at actual numbers, the differences become quite apparent. According to IRS guidelines, the interest rates for August 2025 were 4.20%, 5.29%, and 6.08%.
However, the interest rates for July 2026 rose to 4.62%, 5.62%, and 6.51%, with all three segments increasing. Particularly, the third segment, which applies to distant future payments, saw a significant jump.
Those who have a long time until retirement or who receive a lump sum at a young age are more affected by the third segment. This means they are more sensitive to changes in interest rates.
According to consulting firm Mercer, a 1% point difference in interest rates can cause a 10-15% change in the lump sum. When you see the numbers, it's much larger than expected, right?
One important thing to know is the lookback month. Each company has rules in their plan regarding which month's interest rate to apply and how long to fix that rate.
For example, if a plan changes its interest rate every January, then the payment for 2026 will use the rate from the end of 2025, and the payment for 2027 will use the rate from the end of 2026.
If the interest rate at the end of 2025 was lower than it is now, it means that those who start receiving payments before the end of the year could receive a larger lump sum. Timing can make a difference in money.
So, I would definitely request written estimates from the HR team or plan administrator based on both before and after the reset date. Comparing them makes the decision much easier.
Besides interest rates, there are other factors to consider. If you receive a lump sum directly into your account, 20% will be withheld for federal income tax.
If you do a direct rollover from the plan to an IRA, you can avoid this withholding. However, you will have to pay taxes when you withdraw from the IRA later, and required minimum distributions (RMD) will apply starting at a certain age.
Texas has no state income tax, so the tax burden is lighter compared to other states. However, federal taxes remain the same, so you need to pay attention to whether to rollover or not.
If you are married, you will also need your spouse's consent. Choosing a lump sum means giving up the survivor benefit for your spouse, so you need a signed consent form in front of a notary or plan representative.
The advantage of a lifetime annuity is the peace of mind that comes from knowing you won't run out of money even if you live a long time. Even if the market fluctuates, the amount you receive each month remains the same.
If the company faces difficulties, the federal agency PBGC guarantees up to a certain limit. As of 2026, the maximum monthly guarantee for a single pension at age 65 is $7,789.77.
On the other hand, most private pensions do not account for inflation. The same amount will have less purchasing power over time, which is a disadvantage.
The appeal of a lump sum is that you can manage it directly and pass it on as an inheritance. However, the risks of investment losses and living too long fall entirely on you.
Honestly, I find it a bit disappointing that such an important choice is left solely to individual financial knowledge. It would be nice if companies explained the interest rate structure more clearly.
To summarize, when interest rates rise, lump sums decrease while monthly annuities remain the same. First, check the lookback month and fixed period of our plan.
Then, get estimates from both points in time for comparison, and consider taxes, spousal consent, health status, and other income sources together.
However, since taxes, life expectancy, and family situations vary from person to person, be sure to consult a certified financial planner or tax professional before making a final decision.
If I didn't have sufficient other retirement income, I would likely lean towards the lifetime annuity. The peace of mind that comes from receiving a steady monthly income is greater than one might think.
 SodaQueen
 LightYard


 puddingcat |
 American Politician Community |
 memorabilia |
 orvian89 |
 looksee 78 |
 action blog 101 |
 Shintongbangtong Shin Naerin James Park |
 4 Runner x100 |
 California Information News |
 Korea Dan Kim |
 Missouri Kings News Information |
 Going Once |
 monica hong |
 Tainami American Travel Story |
 tarve7 |
 Something is popping in the situation |
 chiobase |
 homan |
 The Yellow |
 love ya |
 virex |
 U.S. Weather Bureau News |
 korvex93 |
 nougatpop |
 milkyotter |
 sun walker |
 Hawaii Tourist Information |
 savannah choi |
 glimmer |
 Hot Seat Driver |