
Many people think, "I'll just use COBRA for 18 months and delay Medicare for later," when they quit their job around their 65th birthday. Honestly, when I first heard this, it sounded like a pretty reasonable plan.
But after looking into the data, I found out this is the most dangerous combination. To put it simply, COBRA does not provide a valid reason to delay enrolling in Medicare Part B.
Let me explain why, step by step. The key point is the number 8 months.
Medicare has a system called the Special Enrollment Period, or SEP, which allows you to delay Part B while you have employer insurance. However, the condition is that it must be a group insurance based on "current employment."
COBRA is a continuation of the same insurance after retirement, so even though it looks the same, it is not considered employer-based insurance under Medicare rules. This one difference completely changes the calculations.
The SEP starts 8 months from the first month after you quit your job or the month after your employer-based insurance ends. This clock runs the same whether you enroll in COBRA or not.
So if you retire and use all 18 months of COBRA before applying for Part B, the 8-month window has already closed long ago. This is the part that many people misunderstand.
Also, if you are around 65, there is the Initial Enrollment Period. It lasts for a total of 7 months, 3 months before and 3 months after the month of your 65th birthday.
If your retirement falls within this 7-month window, it's best to apply for Part B then. There's no need to go through the SEP.
What happens if you miss the window? You can only enroll during the General Enrollment Period, which runs from January 1 to March 31 each year.
Starting in 2023, the rules have changed so that if you enroll in GEP, coverage begins on the first of the following month. There's no longer a gap until July like before, but there can still be a coverage gap for several months in between.
The real issue is the penalties. According to SSA, for every full 12 months you could have enrolled in Part B but didn't, your premium increases by 10%.
The scarier part is that this is not temporary; it continues to apply as long as you keep Part B. You can think of it as a lifelong penalty.
Let's look at the numbers. The standard premium for Part B in 2026, as announced by CMS, is $202.90 per month, with an annual deductible of $283.
If you enroll 2 years late and incur a 20% penalty, that adds $40.58 to your monthly premium. That's $486.96 for a year.
Moreover, the penalty is based on the standard premium for that year, so if premiums go up, the penalty amount increases as well. The 2027 premium has not been officially announced by CMS yet, so I won't include numbers here.
It's not just the penalties that are a problem. If you use COBRA while eligible for Medicare, in many cases, COBRA becomes a secondary insurance that pays after Medicare.
But what if you didn't enroll in Part B? COBRA may not cover the portion that Medicare was supposed to pay. That gap becomes your responsibility.
Some COBRA plans are designed to pay only the remaining amount as if Medicare had already paid its share. This varies by plan, so you must confirm this in writing.
There are even cases where COBRA mistakenly pays as primary and later asks for that amount back. If this happens during a year with high medical expenses, it can be a real disaster.
So what should you do? Here's the order I recommend.
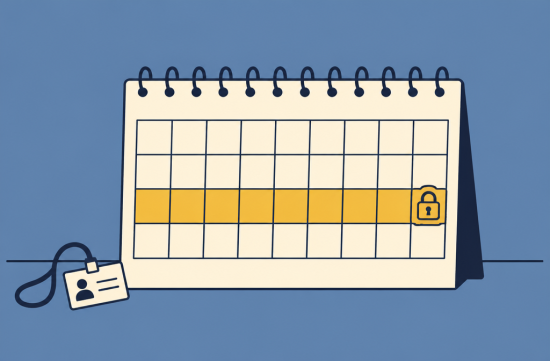
First, once your retirement date is set, mark the 8-month deadline on your calendar starting from the following month. This date is the key, not the COBRA period.
Second, check with your company's HR about exactly when your employer-based insurance ends. It's also helpful to get the employment verification document (CMS-L564) needed to apply for Part B from SSA.
Third, if you plan to keep COBRA, ask the plan in writing how it coordinates payments with Medicare. Sometimes people use COBRA alongside Medicare for services like dental or vision that Medicare doesn't cover.
If you're in Oklahoma, you can get free counseling from the Medicare Assistance Program (MAP) run by the Oklahoma Insurance Department. The toll-free number is 1-800-763-2828.
Of course, results may vary depending on your spouse's employer insurance or the number of employees, so be sure to check with a MAP counselor, SSA, or a professional based on your individual situation.
Personally, I think this system is a bit unfriendly. It's not easy to catch this trap just by looking at the COBRA information.
However, the rules themselves are clear. I believe it's better to manage my deadlines rather than expect the government to take care of it for me.
If it were me, I would apply for Part B the moment my retirement date is set and consider COBRA only as a supplemental option. There's no reason to carry the risk of a lifelong 10% penalty.
 SkyStudio

 puddingcat |
 American Politician Community |
 memorabilia |
 orvian89 |
 looksee 78 |
 hazelnut |


 Information on All Regions of the United States |
 daisypat |
 tarve7 |
 Something is popping in the situation |
 chiobase |
 homan |
 The Yellow |
 love ya |
 virex |
 U.S. Weather Bureau News |
 korvex93 |
 nougatpop |
 milkyotter |
 sun walker |
 Hawaii Tourist Information |
 savannah choi |
 glimmer |
 Hot Seat Driver |
 Thou Thou |
 Supplemental Security Income (SSI) Information |
 Breaking Bad Drama |
 San Jose Pop |