
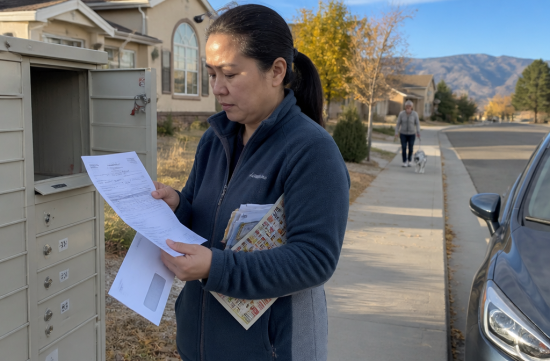
Recently, I've started receiving insurance company notices in my mailbox. That envelope detailing how much next year's premiums will increase—everyone has received it, right?
I opened the envelope and paused for a moment. So this time, I decided not to procrastinate and to properly compare the 2027 plans.
To get straight to the point, if you're choosing individual insurance in Colorado, I recommend starting with the Colorado Option plan. Let me explain why step by step.
First, let's look at the numbers. The Colorado Division of Insurance announced the final premiums for 2027 on September 22.
The individual insurance market is expected to rise by an average of 10%, while the small group market is projected to increase by 14%. The national median is 15%, so it's relatively less of an increase.
The Colorado Springs area (Rating Area 2) has been announced with an average increase of 9.7%. This figure also reflects the effect of the state reinsurance program, which has lowered premiums in this area by 13.5%.
Still, a 10% increase is not a small number. Since it's a monthly payment, it really adds up over the year.
Now, let's clarify what the Colorado Option is. It's a state government standardized plan that was introduced in 2023.
Insurance companies selling individual plans are required to offer this plan in every county they operate. It comes in bronze, silver, and gold tiers.
The key point is that the benefit structure is standardized. Since the basic coverage framework is the same regardless of the insurance company, it allows for an apples-to-apples comparison.
If you've compared regular plans, you know how confusing it can be. Deductibles, copays, and coinsurance vary widely, making it hard to compare even with a chart.
The Colorado Option simplifies that comparison process by about half. Ultimately, you only need to focus on premiums and networks.
The second reason is the $0 cost-sharing for certain services. According to the insurance department's announcement, this plan offers $0 for primary care visits and mental health counseling.
Moreover, this copay applies even before meeting the deductible. This means you won't have to pay the full cost of a visit if you go to the doctor for a cold at the beginning of the year.
This is especially significant for those considering high-deductible bronze plans. Even if you don't visit the doctor often, you'll likely need to go at least once or twice a year.
The third reason is the premium cap mechanism. By law, this plan must gradually reduce premiums compared to 2021 levels, aiming for a 15% reduction by 2025.
After that, the rate of premium increases is designed to be tied to the national medical inflation rate. This structure makes it difficult for insurance companies to raise rates arbitrarily each year.
Of course, there are opposing views. Insurance companies and hospitals worry that price pressures could lead to narrower networks.
I think this concern has merit. So rather than saying the Colorado Option is the definitive answer, I suggest using it as a starting point.
In fact, it has gained quite a bit of popularity. During the 2025 open enrollment, 47% of Connect for Health Colorado enrollees chose this plan.
This year, the situation is more complicated. The enhanced premium tax credit that has been in place since 2021 has expired.
Instead, the state's Colorado Premium Assistance will cover part of the costs. Enrollees receiving assistance are estimated to see an average monthly increase of about $20 compared to 2026.
Without this support, the average monthly increase would have exceeded $69, which is more than three times the difference. I was honestly a bit surprised by those numbers.
Make sure to keep the dates in mind. The 2027 open enrollment starts on November 1 and runs until January 15 of next year.
To receive coverage starting January 1, you must enroll by December 15. If you enroll after that, coverage will begin on February 1.
This year, a new insurance company called Colorado Access is entering the individual market. With one more option available, it's worth checking if they are included in your local network.
Here's how I approach my comparisons. First, I check if my current primary care physician and hospital are in the network.
Next, I verify if my medications are on the formulary, and finally, I compare premiums side by side between the Colorado Option and regular plans of the same tier.
If you have ongoing medications or treatment plans, consult with your doctor or pharmacist to outline the necessary coverage first. You can also ask certified brokers from Connect for Health Colorado about plan details for free.
If it were me, I would start by looking at the Colorado Option silver or gold plans this year. The $0 primary care visits and predictable structure provide much more peace of mind over the course of a year than just a few dollars difference in premiums.
 DJWashington

 nixxon |
 LIZ Legal Information Blog |

 Karina's Blog |
 Jimbeam 88 |
 Taco Bell Candy Note Blog |
 Springs Korea |
 Questions about firearms while living in America |
 Colorado Lee |
 coloradoman |
 urbanmint |
 forestcloud |
 forever young |
 Arlington house |
 liquid asset |
 Who's watching? |
 eclipse |
 quietwave |
 Hajiwon Blog Hair Salon |
 hoosierdaddy |
 saffronroute |
 korvex93 |
 Mini Mee |
 Darnignac |
 vanilla |
 selvon |
 brownie |
 Star Blog |
 The Day the Sun Rises |
 sweetpop |