
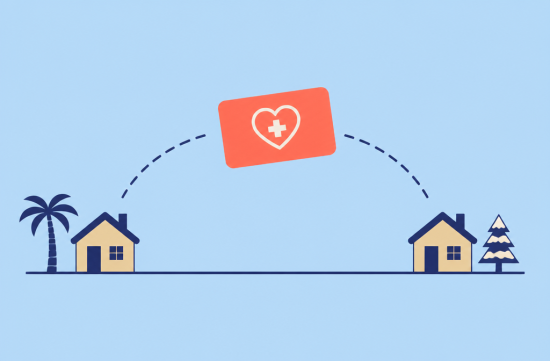
In winter, a desert home; in summer, a northern house. These days, I often hear a common question from snowbird seniors.
"My Medicare plan works when I'm in another state, right?" That's the question.
To be honest, I initially thought that Medicare Advantage was the same everywhere in the country. Because of that misconception, I once mistakenly helped someone compare plans, so today I want to clarify this properly.
The timing is just right. The annual Medicare enrollment period for choosing 2027 plans starts on October 15 and ends on December 7.
Any plan changes made during this period will take effect on January 1, 2027. If you miss December 7, you'll have to stick with your current plan for the entire next year, so be sure to mark it on your calendar.
First, let's look at the basics. Original Medicare, which includes Part A and B, can be used at any hospital that accepts Medicare anywhere in the U.S.
In contrast, Medicare Advantage plans usually have specific networks and service areas. If it's an HMO, coverage outside the service area is often limited to emergencies or urgent care, with few exceptions.
My mistake happened right here. I mentioned that a $0 premium HMO looked great because of its benefits, but the person spent five months a year in another state.
Ultimately, when they tried to get regular check-ups and specialist care there, they found that everything was blocked because it was out of network. Fortunately, there were no major health issues, but I really broke out in a cold sweat at that moment.
There's another rule to keep in mind. Most Medicare Advantage plans may terminate your coverage if you are outside the service area for more than six months.
Some plans do allow longer periods through visitor programs or travel benefits, but this varies by plan, so be sure to check the benefits summary before enrolling.
So, does that mean Advantage plans are not suitable for snowbirds? Not necessarily. PPO plans cover out-of-network care but usually come with higher out-of-pocket costs, so they can be an option.
However, it's best to directly call to confirm whether the doctors and hospitals you want to see in both areas accept that PPO, as website lists can sometimes be outdated.
A commonly recommended combination for those traveling between two areas is Original Medicare with a Medigap policy and a separate Part D drug plan. The biggest advantage is that there are almost no network concerns.
However, you need to calculate costs carefully. The standard monthly premium for Part B in 2026 is $202.90, and the annual deductible is $283.
On top of that, you'll have separate premiums for Medigap and Part D. So, the fixed monthly costs will definitely be higher than a $0 premium Advantage plan.
On the other hand, in years when you need a lot of care, Medigap might actually provide more peace of mind. Ultimately, it's a matter of whether you want to pay fixed costs or pay as you go.
Let's also touch on drug costs. The out-of-pocket maximum for Part D in 2026 is $2,100, but it will increase to $2,400 in 2027.
The maximum standard deductible for 2027 will also rise from $615 to $700, so be sure to check if your current medications are on the new plan's drug list. Remember that the monthly premiums do not count toward this out-of-pocket maximum.
There's one more trap here. You can switch from an Advantage plan back to Original Medicare during the annual enrollment period, but switching to Medigap may require a health assessment after the initial enrollment period.
So, thinking "I'll use Advantage for now and switch to Medigap later" might not be as easy as it sounds. You really need to be aware of this in advance.
For those with Medigap in California, there is some relief. There is a birthday rule that allows you to switch to a Medigap plan with the same or fewer benefits without underwriting within 60 days of your birthday.
If you travel abroad, keep this in mind as well. Several Medigap plans cover emergency care abroad after a $250 deductible, up to 80%, with a lifetime limit of $50,000.
This only applies to emergency care that starts within the first 60 days of your trip. Original Medicare generally does not cover overseas care.
If I had to choose, here's how I would do it. I would first write down the names of my primary care doctors and hospitals in both areas.
Next, I would input my list of medications into a Medicare plan comparison site, and finally, I would count the number of months I plan to stay in another area for the year. Just doing these three things will significantly narrow down the options.
In California, there is also a free Medicare counseling service called HICAP. It's a place where you can ask questions without the pressure of insurance sales.
Since premiums and coverage can vary greatly based on health status, income, and location, be sure to double-check with an expert before making a final decision. I hope you don't make the same mistake I did by being swayed by superficial benefits.
Have you ever faced difficulties with Medicare while traveling between two areas? Let us know in the comments what combination you are using.
 AlwaysPray


 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 AliAluAlo Blog |
 Sarah's Blog |
 Casa Mia |
 US Regional Information Local News |

 USA Hyundai Kia |
 selvon |
 brownie |
 Star Blog |
 The Day the Sun Rises |
 sweetpop |
 California Kangaroo |
 zanero |
 station |
 Static |
 Star Way |
 American Blog Forge |
 MMORPG Games |
 Then you must be spring |
 Spicy Immigration Life |
 zenvor16 |
 The 2000 |
 toclick |
 wexlin84 |
 Hairy Poppins |
 daisypat |