
Recently, I've been hearing a lot about parents' Medicaid situations. This year, a section was added to the renewal paperwork asking for bank balances. At first, everyone thought it was a mistake.
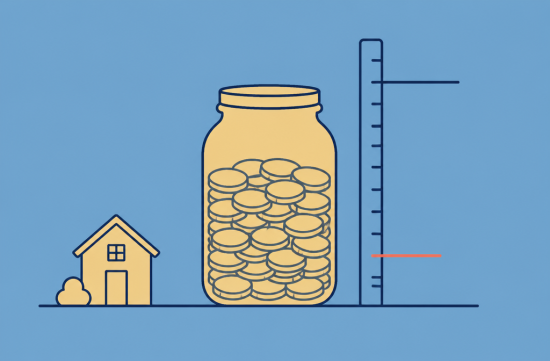
It's not a mistake. California's Medicaid asset limit has been reinstated as of January 1, 2026. It was eliminated in January 2024 and has returned after two years.
The basis for this is the 2025-26 budget bill, AB 116. The state government explained that this is a measure to address the budget deficit. Considering it was raised from $2,000 to $130,000 in 2022 and then completely eliminated, this is quite a significant shift.
The limit is set at $130,000 for individuals. For each additional household member, $65,000 is added, with a maximum of 10 members counted.
For couples, that means a limit of $195,000. However, adult children living with them do not count towards household size or asset calculations.
So, who qualifies? Those receiving Medicaid through non-MAGI programs, such as individuals over 65, those with disabilities, or residents of nursing homes.
General adult expanded Medicaid or children, which only look at income criteria, do not have asset assessments. Medicaid linked to SSI retains the original limit of $2,000.
The most common question is about homes. A single home that you actually live in does not count as an asset.
One car is also excluded. Household items like furniture and TVs are similarly exempt. So, even if home values have increased, as long as you continue to live there, you can worry less.
On the other hand, cash, checking and savings accounts, and CDs are all included. A second home, a second car, and land that is not lived on also count.
Retirement accounts can be a bit confusing. If you are regularly receiving distributions from accounts like an IRA, the account itself is excluded, but the distributions are counted as income.
If your parents are already receiving Medicaid, there's nothing they need to do right now. Their assets will be checked during the first renewal in 2026.
New applicants will be assessed immediately upon application. If they exceed the $130,000 limit for individuals, they will be denied.
If they exceed the limit, there are ways to spend down before renewal, such as home repairs, purchasing furniture, or paying off car loans.
However, caution is needed with long-term care like nursing homes. Transferring assets for less than their value can result in a delay in long-term care benefits for a certain period.
When applying for long-term care, Medicaid can look back at asset transfers up to 30 months prior. However, it has been clarified that transfers made between January 2024 and December 2025 will not be considered in the 2026 renewal.
But there's something even more important. The state budget confirmed this summer that the limit will change again in 2026-27.
Starting July 1, 2027, the limit will drop to $21,000 for individuals and $31,000 for couples. Compared to $130,000, that's nearly an 84% reduction, which honestly surprised me when I saw the numbers.
The governor's original May revision proposed a limit of $2,000 for individuals starting in January 2027. The state legislature rejected this and adjusted the amounts and timing, resulting in the current situation.
Both sides of the argument make sense. The state government estimates it will save $348.5 million from the general fund in the 2027-28 fiscal year.
On the other hand, senior organizations are concerned that individuals may lose care benefits due to a few thousand dollars they have saved over a lifetime. There are already forecasts that the number of IHSS users will decrease.
So, here's how I've organized things regarding my parents. First, I write down the balances and names on their accounts on one sheet.
Next, I categorize assets into exempt assets like their home, car, and retirement accounts, and those that count. Then, I mark the renewal date on the calendar.
If there's any possibility of needing long-term care, stop transferring money into the children's names for now. If the 30-month look-back applies, it could cause issues when it's actually needed.
Also, remember that estate recovery remains unchanged regardless of these changes. Even if the limits change, the posthumous recovery rules still apply.
If one spouse enters a nursing home, the spousal impoverishment rules protect the share of the spouse remaining at home. This part is complex, so be sure to ask the county office.
Given the complexity of the regulations and the varying outcomes based on individual situations, be sure to consult an elder law attorney or expert before making major decisions. In Orange County, you can receive Medicaid counseling from the Social Services Agency.
My conclusion is simple. Now is the time to organize your parents' assets and plan for care, with time until July 2027.
Budgets change every year, so it could be different in next year's negotiations. Still, if it were me, I would prepare based on the $21,000 limit rather than expecting it to change.
 MacaronTroupe


 vibranto |
 sparkling |
 oh my salami |
 saffronroute |
 You Only Live Once |

 Piano Teacher Blog |
 Kkikki Ppappa Shout Out Loud |
 Coco and Lulu |
 U.S. Weather Bureau News |
 American Airlines Mileage |
 laro90 |
 MEDBIO American Doctor Blog |
 SWAT TEAM BLK |
 DREAM BIG |
 frostbite |
 330 Forever My Love |
 El Dorado |
 dralix58 |
 Gorama Round |
 Skydiving |
 dreamport |
 Yellow Snowman |
 Toaster Pizza Magic Show |
 velvetnom |
 Anytime Journey |
 Mrs. Duluth |
 jaxter |
 Atlanta Mama |
 Baguette Blog |
 Tan Sol |