
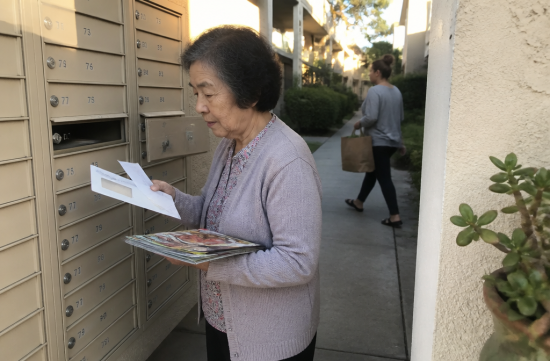
It's shocking to think that a letter mixed in with all the advertising mail in my mailbox could determine my hospital costs for the year. It's the rigidly named ANOC, or Annual Notice of Change.
If you are enrolled in a Medicare Advantage or Part D prescription drug plan, the insurance company must send this letter by September 30 each year. It outlines how your plan will change starting January 1 of the following year.
Someone once shared their experience with me via DM. They found that their copay for the blood pressure medication they take daily suddenly skyrocketed in the first month of the new year, leaving them waiting at the pharmacy counter for a long time.
It turned out that the medication had been moved to a different tier on the plan's formulary, and that information was clearly stated in the ANOC that had arrived the previous fall. The envelope had been sitting unopened in a drawer.
Oh, of course. Who reads every piece of mail from their insurance company? But this letter is one you need to pay special attention to.
That's because Medicare Open Enrollment runs from October 15 to December 7. During this period, you can freely change your plan, and any changes will take effect on January 1 of the following year.
So, the ANOC is like a study guide you receive before an exam. If you miss the deadline without reviewing it, you'll be stuck with the new conditions for an entire year.
So, where should you start when you open the letter? I recommend focusing on just five key areas.
The first is the monthly premium. The second is the deductible, which is the amount you must pay out of pocket before the insurance starts to cover costs.
The third is the copay for doctor visits and specialists, the fourth is the annual out-of-pocket maximum. The fifth, and most important, is to check if the medications you currently take are still on the formulary.
You also need to check the doctor and hospital network. If your primary care physician is out of network next year, the costs for the same services could change significantly.
Let's look at some numbers. According to CMS, the standard deductible for Part D in 2027 is set at $700, up from $615 this year.
On the other hand, the annual out-of-pocket maximum for prescription drugs is set at $2,400, an increase from $2,100 this year. If you exceed this limit, the cost of covered medications for the remainder of the year will be $0.
Having a cap is certainly good news. However, it's a bit disheartening that the cap itself has increased by $300 in just one year.
There is some good news, though. CMS predicts that the average monthly premium for Medicare Advantage in 2027 will drop to $12, down more than 16% from this year's $14.37.
But here's the twist: just because the average is going down doesn't mean your plan's premium will decrease.
Your premium might stay the same, but your copays could increase, or additional benefits like dental or vision coverage could be reduced. The average is just that—an average; the numbers on your letter are your actual numbers.
So, my recommended approach is simple. Lay out your ANOC and write down the list of medications you actually used this year and the number of doctor visits you made.
Then, go to Medicare.gov's Plan Finder and enter the names of your medications. It will allow you to compare the estimated total costs of your current plan with other plans side by side, helping you avoid the mistake of choosing based solely on premiums.
If September 30 has passed and you haven't received your letter, call the plan directly using the number on the back of your insurance card. Many plans also allow you to access it online.
If you're overwhelmed by English documents, consider using HICAP, California's free Medicare counseling program. They don't sell specific insurance plans, so you can get relatively neutral explanations.
You can also call 1-800-MEDICARE and request a Korean interpreter. A single phone call could change your medication costs for the year, so it's worth your time.
If you happen to miss the December 7 deadline, it's not completely over. Medicare Advantage enrollees have another opportunity to change their plan between January 1 and March 31.
However, this is a limited opportunity for Advantage enrollees, so it's much more convenient to sort things out in the fall.
Of course, the right plan varies greatly depending on individual health status, medications, and income conditions. Since it differs for everyone, be sure to confirm with a HICAP counselor or expert before making your final decision.
Here's my take: rather than waiting for the government to do more, the most reliable savings come from properly reading the information you already have.
The insurance company has fulfilled its obligation to send the letter, and now it's up to us to read it. It may sound harsh, but that's the reality.
This weekend, take a moment to dig through your mailbox or drawer. If you find a thick envelope from your insurance company, set aside just 20 minutes with a cup of coffee to go through it.
And don't forget to ask your parents or elderly friends if they've opened that letter. Just asking, "Did you open that letter?" can make a bigger difference than you might think.
 redriverwalker2003


 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 AliAluAlo Blog |
 Raccoon Ramen Night |
 DREAM BIG |
 Shoot Me |
 Information on All Regions of the United States |
 Cap Com |
 nixxon |
 kevin Kim |
 beerdreamer |
 Kims Spring |
 White bunny |
 Kansas City Representative Singer |
 shadow 007 |
 sun walker |
 Choco Choco Star |
 midnight blue |
 honeypot |
 summer |
 adventure77 |
 flexible |
 Shintongbangtong Shin Naerin James Park |
 truepixel |
 Kathy's Blog |
 Hae Naem |
 quatspace |