
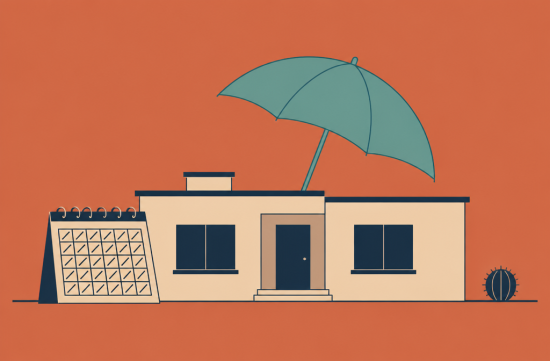
By mid-November, the lights come back on in the Palm Springs villa community. This year, I've heard several stories about finding water stains on the ceiling after opening the door to a house that had been closed all summer.
When such incidents occur, most people think they have insurance, so it should be fine. However, when they actually file a claim, they often find themselves in trouble due to the unfamiliar term "vacant home clause."
From my long observation of the local market, I've noticed that villa owners pay close attention to their roofs and air conditioning but rarely read these few lines in their insurance policies. Today, I will focus on that aspect.
The standard terms of HO-3 type homeowners insurance commonly used in the U.S. include a clause stating that if a home has been continuously vacant for more than 60 days prior to a loss, some compensation may not be provided.
A typical example is vandalism, or intentional damage and glass breakage. If someone breaks a window and damages the house, but it had been vacant for over 60 days prior, this part may not be covered.
The 60-day period is merely a standard guideline. Some insurance companies set it at 30 days, so you should check how many days are specified in your policy.
Many people get confused about the difference between "vacant" and "unoccupied." While both seem to mean empty, they are treated differently in insurance.
Generally, a house that still has furniture and belongings but is temporarily empty is considered unoccupied. A house that has neither people nor belongings is closer to being vacant.
Therefore, many interpretations suggest that a fully furnished villa is typically not regarded as vacant. However, it is common for policies not to define these two terms separately, so in case of a dispute, the court will ultimately make a judgment based on their general meanings.
Another point to be cautious about is that some policies combine vacant and unoccupied into an exclusion clause. If this is the case, even a furnished villa may be subject to this exclusion if left empty for an extended period.
The attitude of California courts is also worth noting. In a 2020 California appellate court case involving a commercial building, it was determined that the 60 days are counted backward from the date of loss, regardless of the insurance start date.
In that case, water damage occurred just 57 days after the insurance began, yet the vacant home exclusion clause was applied. The argument that it hadn't been 60 days since the insurance started did not hold up.
In 2023, the Federal Ninth Circuit Court also ruled that such exclusion clauses are valid if they are clearly and prominently stated. It is safer to assume that what is written in the policy will be enforced.
Water damage also needs to be considered separately. The standard terms state that damage caused by frozen pipes while the house is vacant will only be compensated if reasonable measures were taken to maintain heating or shut off water and drain the pipes.
In desert areas, the risk of freezing may seem remote. However, the key point of this clause is whether the owner fulfilled their duty of care while the house was vacant. The insurance company will judge based on that effort.
Consider a scenario where someone leaves with the main valve open and the washing machine hose bursts. If no one notices for months, not only will the damage increase, but issues of negligence in management will also be examined.
Therefore, my advice to villa owners is straightforward. First, call your agent to get written confirmation of how many days your policy defines as vacant and how it defines vacant versus unoccupied.
If you plan to exceed the specified number of days, the next step is to ask if there are additional options like a vacant home permit or vacant home endorsement. It's better to pay a little more in premiums than to leave a gap.
Before leaving, I recommend making it a standard practice to shut off the main water valve. However, if there is a fire sprinkler system in the house, shutting off the water may also deactivate it, so consult with a plumbing professional first.
Installing a leak detector can send alerts to your phone. Stopping mail and package deliveries is also a way to reduce signs of vacancy.
If possible, ask a trusted neighbor or a home watch service to check on the house regularly. Keeping a record of visit dates and photos can serve as evidence of management when filing a claim later.
If you plan to rent out the property while it's vacant, the situation changes. Many standard homeowners insurance policies do not cover rental activities, so you need to check for rental endorsements or separate products.
Sometimes, people leave while construction is ongoing. Some policies do not consider a house under construction as vacant, but the wording varies by insurance company, so you'll need to ask about this in advance as well.
In recent years, renewing insurance in California has become more challenging. Keep in mind that if a claim is denied due to the vacant home clause, it could affect your next renewal.
Terms vary by company and policy. The information summarized today reflects a general structure, and the exact application should be confirmed through your own policy and agent.
In my opinion, for those who leave their villas vacant for months, it is far more beneficial to clearly understand the vacant home criteria than to save a little on premiums. Accidents tend to happen when no one is around.
As the season approaches, I encourage you to review your policy alongside opening your home. You will feel much lighter when you lock up and leave next summer.
 SourPickle
 LuckyStone77


 Dolly |
 B.I.G. Victor |
 Amber H |
 uplifted |
 Dr. Kelso |
 Sarah's Blog |
 US Regional Information Local News |
 Hawaii Tourist Information |
 savannah choi |
 glimmer |
 Hot Seat Driver |
 Thou Thou |
 Supplemental Security Income (SSI) Information |
 Breaking Bad Drama |
 San Jose Pop |
 Gook Rule |
 UCLA Captain |
 Asparagus Blog |
 Joseon Dynasty Seal Enthusiasts |
 zestorbit |
 Lemon Kim |
 Noodle Noodle |
 blueman |
 Alabama Bang |
 Soy Angelino |
 puddingcat |