
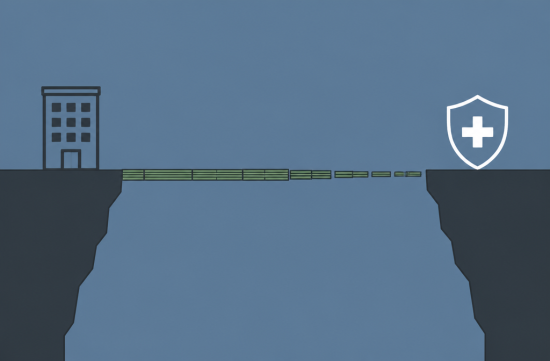
These days, I often hear that companies are offering buyout packages. They are asking employees in their mid to late 50s to leave voluntarily in exchange for several months' salary.
From the perspective of the recipient, the prospect of receiving a lump sum can be enticing. However, when you break down the numbers, you may find that what you actually keep is less than expected, and there are definitely things you will lose.
So today, I want to outline the calculation steps I actually take when I receive an offer. Don't make decisions based on gut feelings; at the very least, confirm these four factors with numbers.
The first is taxes. Buyouts or severance pay are treated as regular wages according to IRS guidelines, specifically as supplemental wages.
When a company pays this separately, they often withhold federal income tax at a flat rate of 22%. This 22% rate will remain the same in 2026, and any amount exceeding $1 million in a year will be taxed at 37%.
Additionally, Social Security and Medicare taxes, as well as California state income tax withholding, will apply. Just because you have a $100,000 package doesn't mean you'll see $100,000 deposited into your bank account.
More importantly, the 22% is not the final tax rate. If the package is added to your income for the same year, your taxable income will increase, and you may owe more taxes the following April.
So be sure to ask whether you should set your retirement date for the end of December or push it to early January, and whether it's possible to negotiate receiving the payment in installments instead of a lump sum. Just shifting your income to a year with lower earnings can make a significant difference in taxes.
The second factor is health insurance. Honestly, the scariest number in early retirement in your 50s is not taxes, but insurance premiums.
Medicare starts at age 65, so how you cover the years before that is crucial. If you continue your company insurance through COBRA, you can usually maintain it for up to 18 months.
However, with COBRA, you have to pay the portion that the company used to cover, which can lead to being billed for up to 102% of the total premium. If you only think about the amount you were paying from your paycheck, you might be in for a shock.
In California, if you have a fully insured plan, you may be able to extend coverage through Cal-COBRA for a total of 36 months after federal COBRA. During this period, premiums can rise to 110%, and depending on the type of plan, you may not qualify, so be sure to check with HR.
There is also a way to go through Covered California, but starting in 2026, things will change. The federal enhanced premium subsidy will end at the end of 2025, and if your income exceeds 400% of the federal poverty line, you will lose the subsidy entirely.
For an individual, that threshold is $62,600. In the year you receive a buyout, the package amount can easily push you over that limit, so it's safer to calculate as if you'll be paying full price for insurance that year.
The third factor is your 401(k). Many people make mistakes here.
There is a Rule of 55. If you leave your job in the year you turn 55 or later, you can withdraw money from that company's 401(k) without incurring the 10% early withdrawal penalty, even if you are under 59 and a half.
However, this only applies if you leave money in that company's plan. The moment you roll it over to an IRA, this benefit disappears, and you will still owe regular income tax even without the penalty.
I once moved my 401(k) to an IRA without thinking much about it when I changed jobs, and later, when I urgently needed money, I couldn't access it due to the penalties. I regret not asking HR just once about it.
So if you are leaving in your mid-50s, don't rush to roll over your 401(k). Keeping it there during times when you might need funds is much more flexible.
The fourth factor is Social Security. For those born after 1960, the full retirement age is 67.
If you apply at 62 after receiving a buyout and your income stops, your monthly benefit will be reduced by 30% for life. Someone who would receive $2,000 a month at 67 will only get $1,400 if they apply at 62, and this reduction will not be recovered later.
One more thing to keep in mind: according to California EDD guidelines, severance pay itself does not affect eligibility for unemployment benefits.
However, wages in lieu of notice or continued salary payments instead of a layoff notice are considered wages and may reduce unemployment benefits. A voluntary buyout may be treated as a resignation, so check the payment details with EDD.
Finally, there are timing rules when signing. If a company offers a group retirement incentive to employees over 40 and requires them to sign a waiver of age discrimination claims, federal law (OWBPA) mandates that the company provide a review period of 45 days and a withdrawal period of 7 days after signing.
That 45 days is not a courtesy from the company; it is guaranteed by law. During that time, it is not too late to consult with a tax advisor or financial planner to review the numbers.
In summary, my calculation method is as follows: subtract the insurance premiums until age 65 from the after-tax package amount, and then see if you can delay Social Security until age 67 with the remaining funds.
If that works out, then lean towards accepting the offer; if not, reconsider. If you are confident in finding your next job, a buyout can be a bonus, but if not, it could turn out to be a more expensive early retirement than you think.
If the numbers are unclear, I would choose to wait. However, since taxes and pensions can vary greatly depending on personal circumstances, be sure to consult with a professional before making a final decision.
 SteveRespect


 Asparagus Blog |
 MBTI Detective Agency |
 summita |
 neroyo |
 American Food Information & Calories |
 Old English |
 US Embassy |

 Archaic Kim |

 Hawaii Tourist Information |
 savannah choi |
 glimmer |
 Hot Seat Driver |
 Thou Thou |
 Supplemental Security Income (SSI) Information |
 Breaking Bad Drama |
 San Jose Pop |
 Gook Rule |
 UCLA Captain |
 US Regional Information Local News |
 Joseon Dynasty Seal Enthusiasts |
 zestorbit |
 Lemon Kim |
 Noodle Noodle |
 blueman |
 Alabama Bang |
 Soy Angelino |
 puddingcat |