
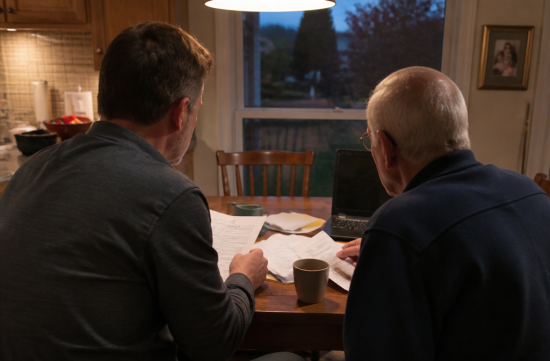
Last weekend, I went for a walk on the local trail with my family, and when we returned, there was a thick envelope on the dining table addressed to my father-in-law. It was labeled Annual Notice of Change.
This is a notice informing about changes to the insurance for the upcoming year. My father-in-law pushed it aside, saying it was in English, and eventually, I, his son-in-law, ended up reading it all evening.
As I read through it, I realized this was not just a document to overlook. The Medicare annual enrollment period starts on October 15 and ends on December 7, and the changes made will take effect on January 1, 2027.
So, I organized a list of things to consider before October 15. I hope this helps those who are managing their parents' insurance.
First, let's look at the major crossroads. Original Medicare consists of Part A and B, which are directly operated by the government, and a separate Part D plan for prescription drugs.
Many people take out private supplemental insurance, known as Medigap, to fill in the gaps. The advantage is that even though the premiums are higher, you can relatively freely go to any Medicare-accepting hospital nationwide.
Medicare Advantage, on the other hand, is sold by private insurers as a bundled product that typically includes Parts A, B, and often D. There are plans with low or no monthly premiums, and they may offer additional benefits like dental or vision coverage.
However, you usually have to stay within a defined network of hospitals, and many times, you need prior authorization to see a specialist. There's a reason why they appear cheaper.
If you are considering Advantage, the first number to look at is the annual out-of-pocket maximum. The maximum set by CMS for 2027 is $9,850 for in-network care, and $14,800 if you include out-of-network care like PPOs.
This is just the maximum allowed by law, and actual plans often set lower limits. Even comparing two or three plans side by side, you can see significant differences in these numbers.
Changes are also coming for prescription drug costs. The annual out-of-pocket maximum for Part D will increase from $2,100 this year to $2,400 in 2027.
The standard deductible will rise from $615 to $700. Once you reach the maximum, any remaining covered drugs for that year will have a $0 out-of-pocket cost, which remains unchanged.
Honestly, the introduction of a maximum is a welcome change, but seeing it increase slightly each year is unsettling. For those living on a fixed income, $300 is not a small amount.
So, I started by rewriting the list of medications my father-in-law takes. Each plan has a different list of covered drugs, and even the same drug can have a different tier, which significantly affects costs.
There are about three things to check in the notice. First, see if your current doctor and hospital will still be in the network next year.
Next, check if the medications you are taking are still on the list or if their tiers have changed. Finally, see how much the copays and out-of-pocket maximums have increased.
Insurance companies are reportedly continuing a trend of reducing additional benefits or completely withdrawing from counties where they are not profitable. If you have received a notice of plan termination, you must choose a new plan during this period.
One part that surprised me the most is that I thought switching from Advantage back to Original would be easy at any time, but Medigap is a different story.
If you miss the protected enrollment period, the insurance company can conduct a health assessment and either deny your application or charge you a higher premium. For those with pre-existing conditions, this can be a decisive factor.
There are exceptions. If you start with Advantage when you first receive Medicare, you have the right to switch back to Original and purchase Medigap without underwriting within 12 months.
Illinois has one additional rule. Medigap enrollees between the ages of 65 and 75 can switch to a plan with the same or lower coverage from the same insurer without underwriting for 45 days from their birthday each year.
However, this applies only to those who already have Medigap, and it is not a regulation that applies to those switching from Advantage. Many people around me have been confused by this difference.
If you regret your decision in January, the path is not completely blocked. Advantage enrollees can switch to another Advantage plan or return to Original Medicare between January 1 and March 31.
If comparing plans feels overwhelming, I recommend SHIP, a free counseling program run by the Illinois Department on Aging. They do not sell insurance, and you can reach them at 1-800-252-8966.
Using the plan finder on Medicare.gov to input the names of medications and pharmacies is also a good idea. I entered my father-in-law's medications and prepared questions before the SHIP consultation.
If you are considering changing medications or adjusting dosages, be sure to consult with a doctor or pharmacist, as this is separate from insurance comparisons. You don't want treatment to be compromised just to save a few bucks on premiums.
In my opinion, if you are currently healthy and find premiums burdensome, Advantage can be a reasonable choice. However, if you have pre-existing conditions or anticipate needing to switch later, I would lean more towards Original Medicare with Medigap.
The decision ultimately depends on each person's health and circumstances. That evening, going through the documents with my father-in-law over a cup of coffee was perhaps the most useful time we've spent this fall.
 AcusWorld

 LIZ Legal Information Blog |

 Karina's Blog |
 Jimbeam 88 |
 Taco Bell Candy Note Blog |
 Splendid Mission |
 My Beloved Hometown Hwagae Market |
 Arlington house |
 Chicagonian |

 Epoca News |
 Sammy Beach |
 Bliss O |
 blue ocean |
 greenlight |
 Watanaka Karametibaksa |
 castle |
 xelton52 |
 carefree |
 vrixen73 |
 AZ Road Master |
 Victory 1988 |
 summita |
 business lim |
 Colorado Lee |
 Make My Day |
 Fros Pro |
 lioness |
 La Bean |
 American History This and That |
 Monte Sori |