
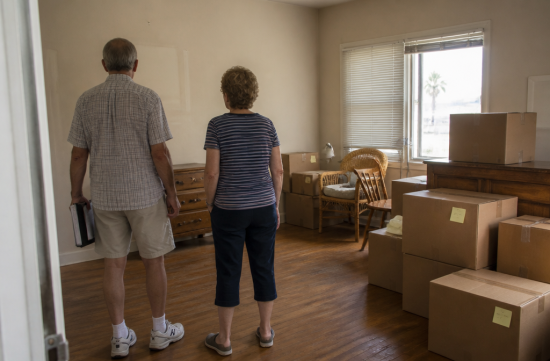
So, today I want to share a realistic perspective. Many people think that selling a large house and moving to a smaller condo after retirement will leave them with a significant amount of cash.
However, when they actually crunch the numbers, many find that they have less left over than expected. Let's break down why that is.
For example, if you sell a house you bought for $300,000 a long time ago for $1,000,000 now, the simple profit is $700,000.
The first thing to consider is capital gains tax. Thanks to federal tax law Section 121, if you've owned the home for more than two years and it was your primary residence, you can exclude some of the profit from taxes.
The limit is $250,000 for singles and $500,000 for married couples filing jointly. This amount is not adjusted for inflation, so it will remain the same even in 2026.
So in the example above, if you're a couple, $200,000 will be subject to tax. If you're single, it's $450,000. Many people are already surprised at this point.
Wait! In California, capital gains are not treated favorably and are taxed as regular income. The structure of adding state tax on top of federal tax makes the impact even greater.
Fortunately, there are deductions available. Costs incurred when selling the house or improvements made while living there, like a roof replacement, can be deducted from the profit calculation.
So, old receipts can actually be worth real money. If you've thrown them away, I recommend looking for bank records or permit records now.
The second factor is the real estate commission. Starting August 17, 2024, according to the NAR agreement, the buyer's agent commission will no longer be displayed in MLS and will be negotiated for each transaction.
While it's called negotiation, in reality, sellers often still bear the cost of the buyer's commission. For a $1,000,000 house, a 1% difference in commission can mean $10,000.
The third factor is transfer tax. In LA County, the tax is $1.10 for every $1,000 of the transaction, so for a $1,000,000 sale, it would be $1,100.
Long Beach does not have a separate city transfer tax like LA, so it's somewhat better. If it were in LA city, you would also have to consider Measure ULA.
Additionally, there are escrow fees, title insurance, repair costs before listing the house, and staging costs. Each of these may seem small, but together they can add up to a significant amount. Especially with older homes, it's common to be asked for repair credits if issues are noted during inspection.
The fourth and most important factor is the property tax on the new home. Due to Prop 13 in California, the longer you've owned a home, the lower the assessed value is compared to the market value.
If you simply buy a new home, it will be reassessed based on the purchase price. This means that even though the house is smaller, the property tax can actually increase, which is quite surprising.
Wait! If you overlook this, you might really regret it. If you are over 55, you can transfer the assessed value of your old home to your new home under Prop 19.
This has been in effect since April 1, 2021, and you can do this even if the counties are different within California, and you can use it up to three times in your lifetime.
The condition is that you must purchase the new home within two years before or after selling the old home. If the new home is more expensive than the old one, the difference will be added to the assessed value.
The comparison criteria also vary by timing. If you buy before selling, it's considered 100%, within a year after selling it's 105%, and in the second year, it's 110%.
So if you sell for $1,000,000 and move to a condo worth $600,000, you can carry over the existing assessed value. However, the application is not automatic; you must apply directly to the county assessor.
Finally, there are the costs of moving itself. When moving to a smaller home, you may not be able to take all your furniture, leading to expenses for disposal and purchasing new items.
If it's a condo, there will also be new monthly HOA fees. If you only look at the difference in home prices, these fixed costs are often overlooked. After retirement, with fixed income, monthly expenses can feel scarier than a lump sum of cash.
To summarize, the order is as follows. First, calculate the profit and the tax exclusion limit. Then subtract the commissions, transfer taxes, and additional costs.
Next, consider the property tax on the new home based on Prop 19, and include monthly fixed costs like HOA fees. This is how you arrive at the actual amount left over.
The tax situation varies by individual circumstances, so be sure to consult a tax professional or expert. The scope of recognized improvement costs can differ from case to case.
If it were me, I would consult a tax professional before listing the house and schedule the new home contract to align with the Prop 19 period. It would be too unfortunate to miss out on tens of thousands of dollars by rushing.
Downsizing your home is definitely not a bad choice. It reduces management burdens and lightens your lifestyle. However, it's important to look at the numbers realistically in advance.
What about you? If you encountered unexpected costs while downsizing, please let me know in the comments!
 LeaveOnAvg


 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 AliAluAlo Blog |
 Coastal city |
 Information on All Regions of the United States |
 Korean Blog |
 Leapfrog Move |
 sylven |
 Sammy Beach |
 Bliss O |
 blue ocean |
 greenlight |
 Watanaka Karametibaksa |
 castle |
 xelton52 |
 carefree |
 vrixen73 |
 AZ Road Master |
 Victory 1988 |
 summita |
 business lim |
 Colorado Lee |
 Make My Day |
 Fros Pro |
 lioness |
 La Bean |
 American History This and That |