
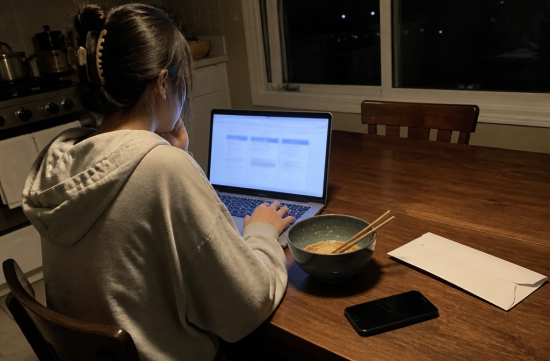
At 11 PM, I put water on for ramen and stopped with my spoon while reading the news on my phone. Even though it's the same health insurance in New York, the requested increase rates from insurers range from 1.4% to 52.1%.
Think about it: the price of a single pack of ramen is going to increase by more than half in a year. That's just an absurd number.
So, I had my late-night snack while summarizing the news today. I hope those using individual plans take a look at this.
First, let's see who determines these numbers. In New York, insurers must request approval from the Department of Financial Services (DFS) to raise next year's premiums.
The DFS announced the final approval results for 2027 premiums on September 4. The average request from insurers in the individual market was 20.6%, but it was cut down to 6.0%.
For small group plans, which are group insurance for small companies, the average request of 23.7% was reduced to 8.0%. The DFS stated that this saved a total of $1.6 billion across both markets.
Looking only at the individual market, that means a reduction of 71% from the requests. Consumer groups noted that the average request was the highest in the last seven years.
Now, let's talk about the gap mentioned in the title. The insurer with the lowest request was CDPHP, based in Albany, which requested a 1.4% increase for individual plans.
The highest request came from UnitedHealthcare, which asked for a 52.1% increase. It's surprising to see such a difference in numbers, even though it's the same state and individual market.
However, the final results are different. CDPHP requested 1.4% but was approved for a freeze with no increase.
UnitedHealthcare's request of 52.1% was reported to be reduced to 8.1%. Still, that's quite a difference compared to those that were frozen.
In the same neighborhood, MVP Health Care requested a 10.7% increase for individual plans, and that was approved as is. Many people in Albany use MVP, so this is a bit painful.
CDPHP isn't the only one that was frozen. Emblem's HIP, IHBC, and MetroPlus also received approvals for 0% increases on individual plans.
For those with group insurance through their companies, the numbers are different. CDPHP's small group requested 14.1% and was approved for 9.7%.
MVP Health Plan's small group requested 19.6% and received 13.6%, while MVP Health Service Corp. requested 12% and got 5.6%. Highmark requested 9.2% but was frozen.
This means that while CDPHP was quiet in the individual market, it raised rates in the small group market by nearly single digits. The results can vary depending on the market.
So why did insurers want to raise rates like this? They cited rising medical costs, drug prices, hospital expenses, increased usage, taxes, and fees as reasons.
According to reports, New York's healthcare spending is about 30% higher than the national average. Looking at that number, it seems scarier than delivery fees for late-night snacks.
The consumer group HCFANY also pointed out the expiration of federal subsidies and the influx of people into the individual market. They estimated that based on the approved increase rates, people would end up paying about $600 more a year, or $50 more a month.
Of course, this is an average estimate, so it doesn't mean my premium will increase exactly that much. The impact varies depending on plan tier, age, and whether one qualifies for subsidies.
When I saw this news, my first thought was that during the fall open enrollment, I might end up losing out if I just auto-renew.
Even for the same bronze or silver plans, the increase rates can range from 0% to double digits among different companies. It seems right to compare the 2027 prices side by side on the NY State of Health website.
However, just switching based on premiums can be risky. It's more important to check if your hospital is in the network and if your medications are covered.
Especially if you have medications you take regularly, make sure to consult with your doctor or pharmacist to check the prescription drug list before changing plans. If one medication is missing, the savings on premiums can disappear in an instant.
If it's hard to compare on your own, there are free consultation services available. The Navigator program guided by HCFANY can be reached at 888-614-5400.
For those using group insurance through their companies, it's also a good idea to ask your HR department about next year's increase rates in advance. The amount deducted from your paycheck can vary depending on the company's share.
Honestly, I think it's fortunate that regulations have managed to cut down the increases this much. However, it's also true that costs are rising for insurers, so I think this tug-of-war will continue every year.
If I were in your shoes, I would definitely start by comparing options this fall. If a frozen plan covers all my doctors and medications, there's no reason to stick with a plan that's going up by double digits.
The ramen is all cooked, but tonight's study session was a success. For my next late-night snack, I'll go for tteokbokki after finishing my comparisons.
 MelonWeather
 KikiLook

 LIZ Legal Information Blog |

 Karina's Blog |
 Jimbeam 88 |
 Taco Bell Candy Note Blog |
 Splendid Mission |
 Tennis City |

 Entip |
 Gold Bar |
 Dolly |
 business lim |
 Colorado Lee |
 Make My Day |
 Fros Pro |
 lioness |
 La Bean |
 American History This and That |
 Monte Sori |
 U donn |
 Sarah's Blog |
 Holy Cow |
 monster |
 houston mama |
 Reggae Party |
 Thou Thou |
 Tennessee Land |
 custardnew |
 Chimhanbang Korea ACU |
 See South Carolina |
 dorex |