
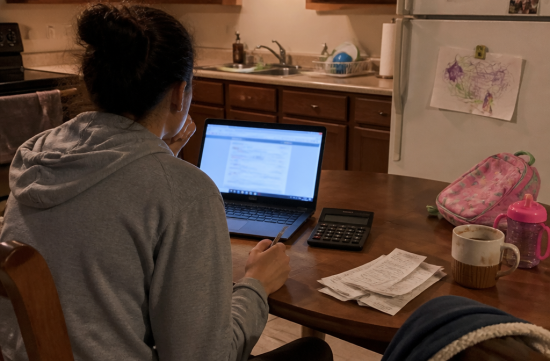
Last week during lunch, a senior colleague suddenly shouted while looking at a benefits email. "The Dependent Care FSA is $7,500! Wasn't it originally $5,000?"
That's right, it was originally $5,000. It had been that way since 1986, which honestly surprised me.
With the One Big Beautiful Bill Act signed on July 4, 2025, this limit increased to $7,500 starting January 1, 2026. If a couple files separately, each can claim $3,750.
However, upon further investigation, I found that there are quite a few things to consider before simply saying, "Just raise it." Since it's open enrollment season, let's break it down step by step.
First, the basics. The Dependent Care FSA is an account where you set aside pre-tax dollars from your paycheck to be reimbursed later.
Eligible expenses include care for children under 13, or for a spouse or dependent who needs assistance. Daycare, after-school programs, and summer day camps are typical examples.
On the other hand, overnight camps or tuition for kindergarten and above are not eligible. Additionally, both spouses must be working or studying.
Looking at the numbers, it becomes clear. If you're in the 22% federal income tax bracket, with FICA at 7.65%, fully utilizing the $7,500 means you'll pay $2,223 less in taxes over the year.
Tennessee has no state income tax, so there's no state tax savings. However, the federal tax and FICA savings are still significant.
According to the Tennessee Commission on Children and Youth's 2025 State of the Child report, the median cost for infant center-based care was $13,926 per year. It's disheartening to hear that it's more expensive than state university tuition.
For families paying this level of childcare costs, reaching $7,500 is quite easy. This is why increasing the limit is likely beneficial.
But here's the first trap! Just because the limit has increased doesn't mean all companies will automatically allow $7,500.
The law sets a maximum limit, but the actual limit is determined by the company's Section 125 plan document. The company may have decided to keep it at $5,000, so check the maximum amount on the enrollment screen.
The second point concerns those with higher salaries. Companies must pass a nondiscrimination test each year, and if only high-income employees are contributing, they may fail the test.
As of 2026, if your previous year's salary exceeds $160,000, you will be classified as a highly compensated employee. In this case, the company may reduce contributions during the year, so keep that in mind.
The third point is the most important. You cannot double-dip with the federal Child and Dependent Care Tax Credit.
The limit for eligible expenses for the tax credit is $3,000 for one child and $6,000 for two or more children. However, the amount you receive tax-free through the FSA reduces this limit.
So, if you have two children and fill the FSA to $7,500, the amount you can claim for the tax credit becomes $0. This is where the calculations can get tricky.
Under the same law, the tax credit rate also increased to a maximum of 50% starting in 2026. If your adjusted gross income is $15,000 or less, the rate is 50%, and for incomes between $43,001 and $150,000 for married couples, it's 35%.
For a couple with two children and a combined income between $43,001 and $150,000, in the federal 12% bracket, the savings from the FSA of $7,500 would be $1,473, while the maximum tax credit could be $2,100.
In this case, the tax credit is actually larger. However, this credit is not refundable, so you need to have enough tax liability to receive the full amount.
On the other hand, if you have one child, the tax credit is 35% but capped at $1,050, so for most families, the FSA is more advantageous. Families with higher incomes that see their credit rate drop to 20% will also find the FSA to be better.
The fourth point is the use-it-or-lose-it rule. Unlike health FSAs, Dependent Care FSAs do not allow carryover, and some companies may only offer a grace period of up to 2 months and 15 days.
Additionally, you can only get back the balance you have accumulated, so if you pay a large registration fee in January, you will receive reimbursements over several months. Be sure to consider your cash flow in advance.
So, my recommendation is as follows. First, calculate your expected childcare expenses based on receipts for next year and check your company's limit.
Then, compare the tax savings from the FSA and the tax credit side by side. Make your decision before the enrollment deadline, as once you decide, you cannot change it during the year without a qualifying life event like marriage or childbirth.
Honestly, $7,500 feels insufficient compared to childcare costs exceeding $13,000. It's not indexed to inflation, so in a few years, it will likely become an outdated figure. I believe childcare support needs to be much more robust than this.
Still, it's important to take advantage of what you can receive now. Since every household has different incomes and filing methods, if you're unsure, be sure to check with a tax professional or your company's HR benefits representative.
I even created a calculation sheet for my colleague. I encourage you all to take just 10 minutes during this open enrollment period to not just copy last year's numbers!
 VelvetTrail75


 morvex37 |
 Ari Songhan American Immigration Life |
 Bearded Strawberry Smoothie |
 Heart Ticker |
 Duck Duck Go |
 U.S. Weather Bureau News |
 cloudnest |
 ttano |
 Reggae Party |
 Thou Thou |
 Tennessee Land |
 custardnew |
 Chimhanbang Korea ACU |
 See South Carolina |
 dorex |
 Taek Jun |
 Choi Cho |
 Anova US Beauty Information |
 whiskerbread |
 Yo Lock Me Up |
 pecantop |
 self-evaluation |
 |
 stalion |
 anchor |
 Smile Face |
 The Long Shot |
 Anjollinya Blog |