
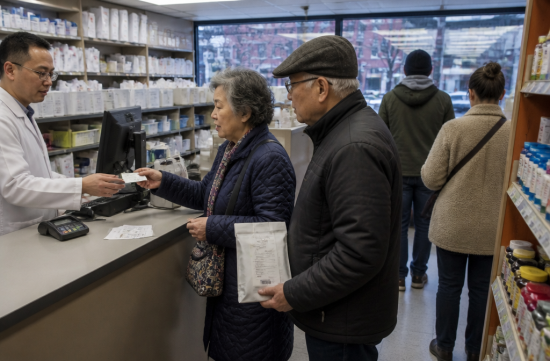
This morning, while sitting at my favorite café in Bed-Stuy with a latte, I overheard two elderly gentlemen at the next table discussing prescription drug costs. One of them sighed, mentioning that the Medicare drug plan premiums had gone up again, and the other asked if he had tried EPIC.
I had only heard the name before but didn't know much about it. So, I came home and slowly read through the New York State Department of Health materials.
EPIC stands for Elderly Pharmaceutical Insurance Coverage. It's a prescription drug assistance program for seniors run by New York State, and it's not a replacement for Medicare Part D but rather an additional layer of supplemental insurance.
The eligibility criteria are simpler than you might think. You must be over 65 and not receiving full Medicaid in New York State.
The most surprising part was the income limits. As of 2026, singles can have an annual income of up to $75,000, and couples can have a combined income of up to $100,000 to qualify.
I thought it was a program exclusively for low-income individuals, but it's actually quite broadly accessible. However, it's worth noting that these limits are not new this year; they have been maintained for some time.
Income is based on the previous year's total income. So, if you exceeded this limit last year, you might not get approved this year, and I've heard that this is the most common reason for denial.
There's one essential requirement: to receive EPIC benefits, you must be enrolled in a Medicare Part D drug plan.
The structure works like this: Part D calculates first, and after meeting the Part D deductible, EPIC covers the remaining out-of-pocket costs.
Additionally, there are quite a few medications that EPIC covers that are not originally covered by Part D. This seems to be an advantage that isn't widely known.
The plans are divided into two categories based on income: the Fee Plan and the Deductible Plan.
The Fee Plan applies to singles with an annual income of $20,000 or less and couples with a combined income of $26,000 or less. There's an annual fee based on income brackets, with the lowest bracket for singles costing $8 per year and the highest costing $230.
The fee can be paid all at once or divided into quarterly payments. Those receiving full Medicare Extra Help are exempt from this fee.
Fee Plan enrollees also receive support for their Part D premiums. In 2026, EPIC will cover up to $58.82 per month.
If your income is higher than that, you'll go into the Deductible Plan. There's no enrollment fee, but you'll need to pay for your medications out-of-pocket until you meet a set deductible for the year.
The deductible range is quite broad. For singles, it ranges from $530 to $2,430, and for couples, it ranges from $650 to $3,215, depending on income.
One point that can be confusing is that the money spent during the Part D deductible phase does not count towards the EPIC deductible.
There is some premium support available in the Deductible Plan as well. If singles earn $23,000 or less or couples earn $29,000 or less, EPIC will cover the average premium level of the basic Part D plan.
If your income exceeds those amounts, you'll pay your own premiums, but EPIC will reduce your deductible by about $706 per year. I found this approach reasonable as it lowers the threshold instead of giving direct cash assistance.
If you exceed the deductible or are in the Fee Plan, your copay for each prescription will be set at either $3, $7, $15, or $20. The higher the cost of the medication, the higher the copay, but the key point is that it won't exceed $20.
This year, there have also been changes to Part D itself. In 2026, the maximum Part D deductible will be $615, and the annual out-of-pocket maximum will be $2,100.
You might think that with the new cap, EPIC is no longer necessary, but I see it differently. Reducing the monthly copays on the way to that $2,100 threshold can make a significant difference.
You can apply at any time throughout the year. When you enroll in EPIC, you'll also receive a special enrollment period to choose a Part D plan, and nowadays, online applications are available.
Right now is the annual Medicare enrollment period. You can change your Part D plan until December 7, making it a perfect time to review EPIC alongside it.
For inquiries, you can call the EPIC helpline at 1-800-332-3742. If you're uncomfortable with English, it's also a good idea to ask someone from your local senior center or HIICAP counseling office to accompany you.
Of course, the calculations can vary significantly based on your income structure, the medications you take, and other insurance, so be sure to consult with a representative or expert to confirm based on your personal situation. It's a program with many variables, so just looking at a few numbers isn't enough to make a decision.
Honestly, I think it's a shame to miss out on something you qualify for simply because you didn't know about it. Many retirees fall within the combined income limit of $100,000.
I felt fortunate to overhear that conversation between the gentlemen at the café. In a time when every dollar counts, saving several tens of dollars on medication is a significant deal. If you know anyone who might qualify, it would be nice to let them know.
 SunnyTrail98




 memorabilia |

 orvian89 |

 looksee 78 |

 vivavida |

 MEDBIO American Doctor Blog |
 newyorker 101 |
 Softember |
 Encyclopedia of New York and Surrounding Areas |
 wishi |

 My Love DS |
 Hardworking CPA |
 People Moon |
 Carolina border |
 korian87 |
 dancing in the rain |
 bravo777 |
 yolo1990 |
 Valley Hong |
 zentra95 |
 abox |
 Belgray Miscellany |
 Spaghetti Pasta Fan |
 softmoony |
 Karina's Blog |
 Moscow Kim |
 steadyo |
 Michigan Enthusiast |
 Shinbaram Dr. Blog |