
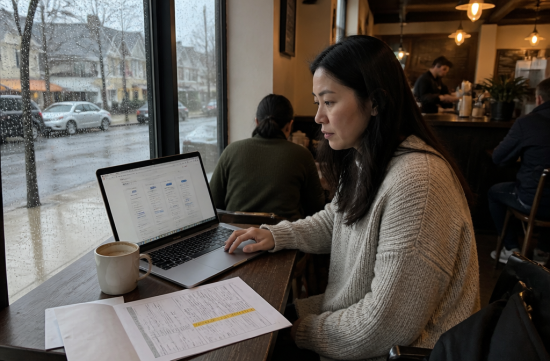
This morning, I set down a latte and opened my inbox to find a notice about my insurance renewal. Suddenly, my coffee tasted a bit bitter.
As a freelancer without company insurance, I find myself visiting the Get Covered New Jersey site around this time every year. This year, the numbers were alarming right from the start.
The New Jersey Department of Banking and Insurance (DOBI) announced on October 15 that the average increase in the individual insurance market for 2027 is 19.8%. Almost 20%! At first, I thought I had misread it.
This figure is a weighted average combining individual plans sold both inside and outside the marketplace, based on amounts before subsidies. This means the actual amount coming out of my pocket can vary from person to person.
For reference, the final increase rate for the 2026 plans was 16.6%. This marks two consecutive years of double-digit increases.
There are significant differences among insurance companies. AmeriHealth has a relatively low increase of 17.0%, while Horizon is at 15.3%.
On the other hand, Oscar is increasing by 29.3%, and UnitedHealthcare is raising rates by 35.7%. Ambetter from WellCare of New Jersey is at 20.8%.
Depending on which insurance company you are currently with, the impact can feel completely different. If you, like me, have a habit of just clicking auto-renew, this year you must stop and compare your options.
I was also curious about why the rates are rising so much. The state government cited rising medical and prescription drug costs, as well as a worsening risk pool.
The background for the deteriorating risk pool is that the federal government did not extend the enhanced premium tax credits. When healthy individuals drop out due to high costs, the remaining enrollees face higher premiums.
In fact, the number of enrollees has decreased. As of January 31, 2026, there were 509,192 enrollees, but by June 30, that number had dropped to 434,700, a loss of 74,492 people.
If we start discussing politics, it could go on forever, but honestly, regardless of who is right, the burden ultimately falls on the enrollees, which is the most bitter part. From an observer's standpoint, I just hope a realistic solution comes out quickly.
However, there is a hopeful aspect. New Jersey's own subsidy, NJ Health Plan Savings, is available to individuals with household incomes up to 600% of the federal poverty level.
This means you don't need to panic just by looking at the sticker price on the chart. When you input your income, your actual burden might be less than you think.
The site's Shop and Compare tool shows estimated premiums by entering your zip code, date of birth, and income. You can do this without logging in, so it can be completed while enjoying a cup of coffee.
The enrollment period is from November 1, 2026, to January 31, 2027. Although the deadline is at the end of January, when you start is crucial.
Following the usual method, if you enroll by December 31, coverage begins on January 1, and if you enroll in January, it takes effect on February 1. Please check the site for the exact start date for 2027.
If you feel overwhelmed doing this alone, there are places to get help. This year, 33 local organizations received over $5.1 million in navigator grants, and they offer consultations in more than 10 languages across 21 counties.
Phone consultations are available at 1-833-677-1010 (TTY 711). I want to emphasize that even parents who find English challenging can request language support.
There are also changes related to immigration status. Starting January 1, 2027, to receive financial assistance, you need to have a qualifying immigration status, and some lawful residents will be excluded from support.
According to federal law H.R. 1, only green card holders, entrants from Cuba and Haiti, and COFA migrants will continue to be eligible for support. Those on visas should definitely check their own situations separately.
Another important point not to forget is that New Jersey still has a health insurance mandate. If you don't have insurance without an exemption, you will face a penalty when filing taxes.
If you completely avoid getting insurance due to rising premiums, you risk facing both penalties and hospital bills. That's a scenario I really want to avoid.
When changing plans, don't just look at the premiums; also check if your current doctors are in the network and if your medications are on the formulary. It's best to confirm this with your doctor or pharmacist.
Plans with lower deductibles may have higher monthly premiums, while those with lower monthly premiums may have higher costs when visiting the hospital. Reflecting on how many times you visit the hospital in a year can make the choice a bit easier.
If I were you, I would grab a corner seat at a café this weekend and start with Shop and Compare. My goal is to make a decision before mid-December.
Just like going out on a rainy day without an umbrella leaves you soaked, if you don't prepare your insurance in advance, you'll find yourself panicking when you really need it. This winter, let's tackle this somewhat tedious task with a strong cup of coffee by our side.
 TongkiDodge

 United States Army |
 premium |
 The Emperor Must Grow |
 squidogame |
 daddyyo |

 gardener 007 |
 loveyom |
 Delicious Food Finder |

 My Love DS |
 Hardworking CPA |
 People Moon |
 Carolina border |
 korian87 |
 dancing in the rain |
 bravo777 |
 yolo1990 |
 Valley Hong |
 zentra95 |
 wishi |
 abox |
 Belgray Miscellany |
 Spaghetti Pasta Fan |
 softmoony |
 Karina's Blog |
 Moscow Kim |
 steadyo |
 Michigan Enthusiast |
 Shinbaram Dr. Blog |