When playing a fighting game, there are moments when you think your health bar still has some left, only to get knocked out in one combo. This summer's news about the New York Essential Plan felt just like that.
As of July 1, the income range of 200-250% of the federal poverty line has been removed from the Essential Plan. The number reported in the news exceeds 450,000.
I've received quite a few messages from people asking, "Do I no longer have insurance?" So, I've organized the information I've confirmed.
First, let's discuss why this happened. Due to the federal budget law of 2025, many legal immigrants lost their eligibility for premium tax credits, significantly reducing the funding for the Essential Plan.
As a result, the state government has discontinued the 1332 waiver that expanded coverage to 250% and reverted back to the original structure of the Basic Health Program. CMS approved this in March of this year.
There is some good news, though. About 1.3 million people with incomes below 200% will continue to maintain their Essential Plan.
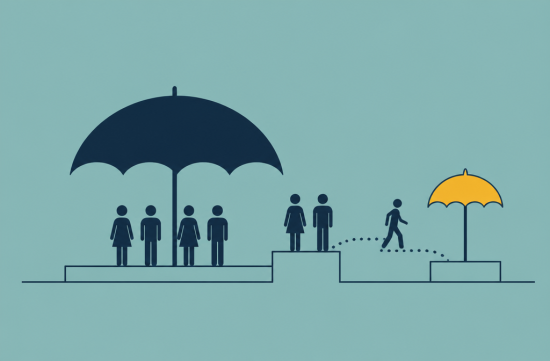
The problem lies with those in the higher range. Individuals earning between 200% and 250% now have to transition to the marketplace's Qualified Health Plans (QHP).
In gaming terms, it's like being forced to switch from a free skin to a paid season pass. The Essential Plan had no premiums, but now they may face monthly premiums along with deductibles.
Fortunately, those in this income range can receive cost-sharing reductions (CSR) if they choose a silver plan. Even if bronze looks cheaper, be sure to compare it with silver first.
For reference, this threshold varies based on household size. For a one-person household, the 200% threshold is around $31,920 annually, but it increases with more family members.
However, there is a more concerning number. According to one report, fewer than 60,000 people have newly enrolled in QHPs since July.
Of course, some may have switched to employer-sponsored insurance, so we can't definitively say everyone is uninsured. Still, the difference is so significant that it honestly surprised me.
So, what should you do now? I think the quickest way is to check three things in order.
First, recalculate whether your income truly exceeds 200%. If your work has decreased this year or your household size has changed, you might fall back below 200%.
Applications for the Essential Plan and Medicaid can be submitted year-round, regardless of the open enrollment period. If your income has changed, there's no reason to wait.
Second, if your income still exceeds 200%, go to NY State of Health and get a quote for a QHP. Many people assume it will be expensive and don't even check.
However, there are some cautionary points. Federal additional subsidies will end by the end of 2025, reducing the amount of subsidies available compared to before.
Eligibility for tax credits can also vary based on immigration status. If your family has a mix of green card holders, work visa holders, and other statuses, be sure to consult with a marketplace navigator or certified navigator.
When looking at quotes, don't just focus on the monthly premium; also consider the deductible and the maximum out-of-pocket costs. Choosing a plan solely based on a low premium and then regretting it after a hospital visit is a common mistake.
Third, if you have options for employer-sponsored insurance, take another look. Some may have passed on company insurance in the past because the Essential Plan was cheaper, but the calculations have changed now.
And don't miss the upcoming open enrollment season. If you miss it, you can only enroll if you have a special enrollment reason.
The exact dates can change every year, so check the marketplace announcements directly. Many people end up missing out because they relied on others' calculations.
One more thing: if you have a pre-existing condition or are on medication, be sure to check how each plan covers your prescriptions. Discussing your necessary medications with your doctor or pharmacist can make comparisons much easier.
I also saw a flyer for free insurance consultations posted at a local Korean market. There are free navigator services available that offer support in Korean, so make sure to take advantage of them.
Personally, I think this change was just too sudden before taking anyone's side. I understand there are financial issues, but removing 450,000 people all at once feels like getting hit with a finishing move without any cooldown.
However, if you sit back and do nothing, it will truly be game over. Everyone has heard how much an emergency room bill can be if you go uninsured.
In summary, recalculate your income, get a quote from the marketplace, check your employer insurance, and mark the open enrollment dates on your calendar.
It may sound difficult, but once you start, it's like a four-quest mission. Completing them one by one will be quicker than you think.
This round may have started unfavorably, but there are still rounds left. Let's make sure to enter the next round with our insurance health bars fully charged.
 HousekeepMemo


 daddyyo |
 Top Beaches |
 Diana Blues |
 Dragon Lee |
 Churros Train Conductor |
 newyorker 101 |
 Franco Family |
 glimmer |
 rapids |
 Softember |
 mykiwi blog |
 Maria Mom |
 Watch for possible danger |
 northpeak |
 Far East Movement |
 Light of the World |
 mariashin |
 lavender |
 Bridgo |
 Tamfa Fan |
 Sunny Sunday |
 mini hometown |
 torvia |
 Chichiki Chicago Train |
 Univ Student |
 See It |
 Con Cheese |
 softmoony |