
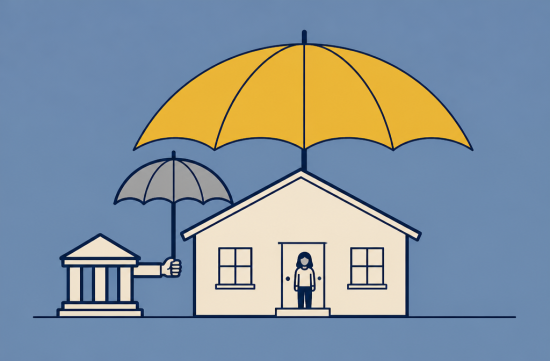
When you receive the closing documents, there's one item that often makes you pause: Owner's Title Insurance.
"I thought I already had title insurance when I got my mortgage; do I need to get another one?" This is one of the most common questions I hear during consultations.
To put it simply, the two types of insurance may have similar names, but they protect different interests. Therefore, having one does not automatically cover the other.
When buying a home with a mortgage, the bank almost always requires a Lender's Policy, which is the Lender's Title Insurance. This insurance protects the bank's loan amount.
According to the Consumer Financial Protection Bureau (CFPB), when a property dispute arises, the primary responsibility lies with the homeowner. The lender's insurance only compensates for issues that affect the bank's loan.
On the other hand, Owner's Insurance protects the buyer's ownership rights and interests. It is not legally required and is optional.
So, what situations would highlight the difference? Let's look at a few commonly mentioned scenarios.
Sometimes, liens for unpaid taxes or construction bills from previous owners are discovered late. There may also be cases where an heir who was missed during the inheritance process appears and claims a share.
Issues like forged signatures or incorrectly recorded boundaries that were not caught during the title search can also arise. When such problems occur, the key question becomes who will bear the legal costs and losses.
These issues often occurred long before I purchased the home, so even if the current owner did nothing wrong, they can still arise. It's challenging to catch every problem, especially those not recorded.
If you have Owner's Insurance, the insurance company will handle legal defense and compensation. Without it, the burden falls entirely on the homeowner.
The cost structure is also worth noting. Owner's Insurance is not a monthly premium; it is a one-time payment made at closing.
The coverage period is long. Lender's Insurance ends when the loan is paid off, but Owner's Insurance remains in effect as long as you or your heirs hold ownership of the home.
In Tennessee, title insurance premiums are set based on rates reported by each insurance company to the state insurance department. The amount varies depending on the home price and the insurance company, so checking the estimate is the best way to get accurate information.
If you purchase both types of insurance together, a simultaneous issue rate may apply, often making it cheaper than buying them separately. Be sure to ask about this.
One confusing aspect is that, according to CFPB regulations, the Loan Estimate shows the lender's insurance at the full price before any discounts, while the owner's insurance is listed separately, which can make it appear more expensive than it actually is.
Therefore, instead of being surprised by the numbers on the documents, it's better to request the actual total amount combining both insurances from the title company.
In Tennessee, it is common for sellers to cover the buyer's Owner's Insurance premium in existing home transactions. However, this is not legally mandated and can vary based on contract negotiations.
There are also local industry explanations that suggest buyers often bear the cost for new homes. Ultimately, it's important to clearly state in the contract who will pay when making an offer.
If the seller is covering the cost, there's really no reason to hesitate. Since it won't cost you anything, there's no need to forgo the protection.
If the buyer has to pay directly, there are a few considerations to weigh. If it's a cash purchase, there won't even be lender's insurance, making Owner's Insurance the only safety net.
Recent local trends indicate a heightened awareness of property fraud. The Hamilton County Register of Deeds offers a free Property Fraud Alert service.
If you register, you will receive email notifications when documents are recorded in your name or address. However, it only alerts you to documents recorded after registration, and previous service subscribers must re-register.
The county register has also advised to be cautious of mail that appears to come from a government agency under the name Clerk's Property Office. If something seems suspicious, it's safest to contact the register directly.
The alert service helps you become aware of issues quickly, but it does not compensate for any losses incurred. In this regard, it serves a different purpose than Owner's Insurance.
To summarize, here's the order of checks: First, see who is responsible for paying the Owner's Insurance premium in the contract.
Next, obtain an actual estimate from the title company that reflects the simultaneous issue rate. Finally, compare the amounts in the Closing Disclosure with the estimate.
Personally, even if the buyer has to pay, I tend to recommend getting Owner's Insurance. The one-time cost provides coverage for as long as you own the home, and there aren't many alternatives. Additionally, even if you refinance later, the Owner's Insurance remains in effect, which is another advantage.
While the amount may not be large compared to the home price, the difference it makes when issues arise can be significant. I hope you don't overlook this item before closing.
 AppleCopter
 SilverMoon72


 B.I.G. Victor |
 Amber H |

 uplifted |

 Dr. Kelso |

 silents |
 banleaf |
 silverfox |
 quietwave |
 U.S. Weather Bureau News |
 Choco Mint Creator |
 strawberry |
 US Regional Information Local News |
 USA Business News |
 Blondee |
 E whisper |
 Potato House |
 freshmint |
 Ansaso |
 Golado |
 babybay |
 honeycom |
 French Macarons |
 Exploring American Life Information |
 Sunshine Blog |
 Community Cross |
 Sayonara H |
 What can make money? |
 Information Search LifeMAN |
 morvex37 |
 neontrail |