
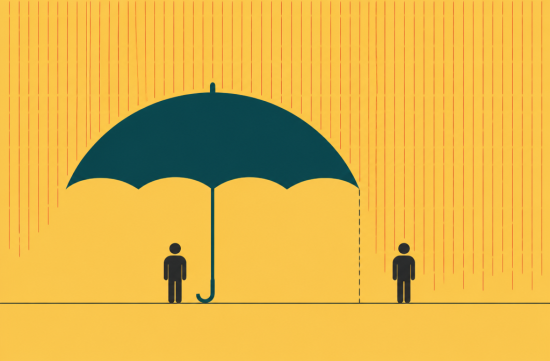
It's that time of year again when the insurance renewal notices arrive. As I open the envelope, my eyes are drawn first to the premium numbers rather than the coverage details.
According to healthinsurance.org, the average premium for individual health insurance in Louisiana will increase by 18.1% in 2027, before accounting for subsidies.
This is slightly higher than the preliminary estimate of 17.3%. In 2026, premiums also rose by an average of 23.7%, marking two consecutive years of double-digit increases.
Compared to the national average, this is significant. The median increase rate for insurance applications analyzed by KFF was 15% nationwide.
The variation among companies is even greater. Ambetter is at 24.5%, UnitedHealthcare at 21.1%, Blue Cross at 14.4%, HMO Louisiana at 13.7%, CHRISTUS at 13.4%, and AmeriHealth Caritas at 10.5%.
Within the same state, the difference between the highest and lowest rates can be as much as 14 percentage points. This discrepancy will be quite important later on.
Why is this happening? KFF identifies the rising costs of medical care, including hospital expenses, as the primary reason.
This is compounded by the expiration of enhanced subsidies at the end of 2025. If the burden of premiums causes enrollees to drop out, the average health status of those remaining declines, which in turn affects the rates.
The exodus in Louisiana is evident in the numbers. The actual number of paying enrollees dropped from 264,790 in 2025 to 195,759 by February 2026, a decrease of 26%.
Interpretations vary. KFF attributes the drop primarily to the end of subsidies, while the Trump administration emphasizes the impact of purging fraudulent enrollees.
I believe both perspectives have some validity. However, considering that KFF experts estimate the number of fraudulent enrollees to be in the hundreds of thousands rather than millions, it seems the weight leans more towards the subsidy side.
Now, to the main point. Will subsidies help mitigate this 18% increase? My answer is that it varies significantly depending on income brackets and the chosen plans.
The premium tax credit is not a program that simply reduces premiums by a certain percentage. It provides support based on the difference between the local benchmark, which is the second-lowest silver plan price, and the amount you are responsible for based on your income.
Therefore, when the benchmark increases, the subsidies also rise. You can think of it as when the river rises, the levee must also be raised.
For example, consider a single-person household with an income of $50,000, which is 313% of the 2026 poverty line of $15,960. According to IRS tables, the burden rate for the 300-400% range is 10.22%, so my share based on the benchmark would be $426 per month.
If we assume the benchmark is $700 per month, the subsidy would be $274. Even if this price rises by 18.1% to $827, my share remains $426, and the subsidy increases to $401.
Of course, it's not free. The burden rate in this range will rise from 9.96% in 2026, meaning that for the same income, my share will increase from $415 to $426. An increase of $11 is about the cost of a couple of tacos, so that's manageable.
The problem arises at the cutoff point. If your income exceeds 400% of the poverty line, which I calculate to be $63,840 for an individual or $132,000 for a family of four, the subsidy drops to $0.
Above this threshold, you bear the full brunt of the increase. If a $700 plan rises by 18.1%, that's an additional $127 per month, or $1,520 over the year. This is particularly painful for self-employed individuals with fluctuating incomes or older couples facing high premiums.
The second issue is automatic renewal. Since subsidies follow the benchmark, if my plan increases more than the benchmark, that difference becomes my responsibility.
The third issue is income forecasting. The repayment cap for excess subsidies will disappear starting in the 2026 tax year. People will start to feel this impact during tax reporting early next year.
The fourth issue is immigration status. Starting in 2027, credits will be limited to lawful permanent residents, individuals from Cuba and Haiti, and some COFA residents. Refugees and asylum seekers can purchase insurance but will not qualify for credits.
The fifth issue is Medicaid. Beginning in 2027, a work requirement of 80 hours per month (or a monthly income of $580) will be imposed. If you fail to meet this requirement, you will not be eligible for marketplace credits.
Nonetheless, low-income individuals will receive significant protection. In 2026, 91% of enrollees qualified for subsidies, with an average subsidy of $674 per month, and the average net premium for those eligible was $82 per month.
If your income is below $39,900 for an individual or $82,500 for a family of four, you should also consider the cost-sharing reductions associated with silver plans. If you only look at monthly premiums and choose bronze plans, you may miss out on these benefits.
The timeline is set by CMS, running from November 1 to January 15, 2027. If you select by December 15, coverage starts on January 1; if you choose afterward, it begins on February 1.
If I were in your position, I would reassess my income for next year. Instead of relying on automatic renewal, I would compare this year's plan side by side with the benchmark on HealthCare.gov.
If I'm near the 400% threshold, I would consult a tax advisor to see if there's room to adjust my income through retirement account or HSA contributions. Before changing plans, I would confirm that my current doctors and medications are still covered, and if I'm in treatment, I would discuss it with my doctor or pharmacist for safety.
In summary, if you choose a plan near the benchmark below 400%, the 18% increase will mostly be covered by subsidies. If you exceed that threshold, there will be no assistance.
This article is based on data available until early November, and the 18.1% figure is an average. Your specific numbers will need to be calculated directly. Those who know where the levee breaks will get less wet.
 SleepIsBest

 United States Army |
 premium |
 The Emperor Must Grow |
 squidogame |
 daddyyo |
 berrypup |
 ORAVEZIN Oppa |
 mochifox |
 panda express |

 citrus pop |
 DO Main TODAY |
 korvex93 |
 tacobunny |
 B.I.G. Victor |
 Conflite Teacher |
 cyvera80 |
 Springs Korea |
 Runner Kim |
 Physical Laws and Science |
 Lansinger |
 honey honey |
 dictionary |
 silverleaf |
 Bany T. |
 Korea Forever |
 wavey |
 Valley Bang |
 Enjoying Samba at Home |
 Goroke Geureoke News |