
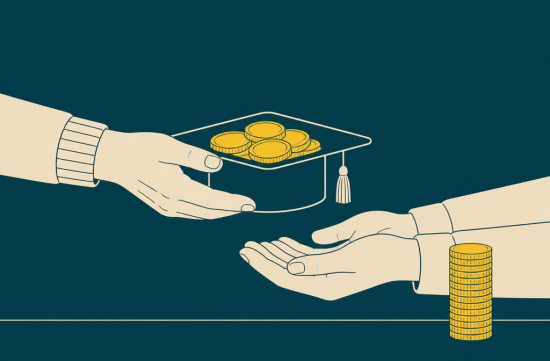
Last week, a friend of mine cautiously asked me while we were having coffee. Her in-laws set up a 529 plan to help with their grandchild's college tuition, but she heard that withdrawing that money could negatively affect FAFSA.
I used to think the same way until a few years ago. However, this regulation has changed, and you can now relax your worries quite a bit.
To put it simply, using a 529 plan in the name of grandparents for tuition does not count against FAFSA calculations. However, there are exceptions depending on the school, so I'll clarify that part as well.
First, it's easier to understand if we look at how the old regulations worked. Grandparent-owned 529 plans were never counted as assets on FAFSA.
The issue arose when money was withdrawn. The amount taken from the grandparent's account for tuition was considered the student's untaxed income, which had to be reported.
If the student's income exceeded a certain deduction amount, up to 50% of it was factored into the aid calculation. So, if grandparents generously contributed $10,000, the need-based grant could be reduced by that amount the following year.
For a while, advice was common to hold off on using grandparent 529 plans until the student was in their junior or senior year of college. This was a sort of strategy to use the funds at a time when they wouldn't affect the last FAFSA.
This changed due to the FAFSA Simplification Act. The revised form has been in effect since the 2024-25 FAFSA.
The new form no longer asks about cash support or expenses paid on behalf of the student by third parties. Therefore, there is no longer a section to report money withdrawn from a grandparent's 529 plan as student income.
In summary, neither the balance of the grandparent-owned account nor the tuition paid from it needs to be reported on FAFSA. This is commonly referred to as the grandparent loophole.
For reference, 529 plans owned by parents still count as parental assets on FAFSA. However, parental assets are factored in at a lower rate, so it's not something to be overly concerned about.
The FAFSA for the 2027-28 academic year has already opened. The legally mandated deadline is October 1, but the Department of Education opened it earlier, marking the earliest opening ever.
There is an important exception to note. This applies to schools that use the CSS Profile.
The CSS Profile is a separate financial aid application operated by the College Board, primarily used by private colleges for their own scholarships. It tends to ask much more detailed questions about family finances.
These schools may ask separately about grandparent support or outside assistance and calculate based on their own criteria. So, just because it's fine on FAFSA doesn't mean it's fine at all schools.
If you have a list of schools your child is applying to, be sure to check the financial aid office guidelines for each school. The way they ask can vary slightly, so it's best to ask directly for the most accurate information.
There's also some tax information that grandparents should know. Money contributed to a 529 plan is considered a gift to the grandchild under tax law.
The annual federal gift tax exclusion limit for 2026 is $19,000 per recipient. This is the same amount as in 2025.
There is also an option to contribute five years' worth of exclusion limits at once. Based on 2026, this means up to $95,000 is possible, but a gift tax return must be filed, so it's advisable to consult with a tax professional beforehand.
Additionally, there are no limits on direct payments made to the school for tuition, separate from the annual gift tax exclusion limit. Sending tuition directly without going through a 529 plan is also an option.
If you live in Pennsylvania, be sure to take advantage of the state income tax deduction. Pennsylvania allows contributions to a 529 plan to be deducted from taxable income up to the federal gift tax annual exclusion limit per beneficiary.
As of 2025, this limit is $19,000, and contributions to 529 plans from other states are also eligible for the deduction. Just remember that rollover amounts from other 529 plans are not eligible for the deduction.
The application of deductions for direct contributions by grandparents may vary based on individual circumstances. It's recommended to check with the Pennsylvania Treasury's 529 guidelines or a tax expert.
The reason I welcome this change is simple. It seemed odd that the desire to help grandchildren could actually lead to a disadvantage.
Especially in our Korean families, it's quite common for grandparents to contribute to tuition. I believe it's a good thing for the entire family that this generosity won't be diminished by the system.
If I were in this situation, I would first determine whether the schools my child is applying to only use FAFSA or also require the CSS Profile.
If it's a school that only uses FAFSA, I would feel comfortable using the grandparent 529 from the first year. If there are schools that require the CSS Profile, I would check their criteria first before deciding when to use the funds.
Also, it's surprisingly important to discuss this topic with family in advance. Deciding who will contribute how much and when can help reduce confusion when the tuition bill arrives.
Since regulations can change in the future, I recommend checking the guidance on studentaid.gov each year when applying. If you know anyone else facing similar concerns, feel free to share this article with them.
 DeliveryFam


 Round and Round Children's Song Kingdom |
 new sugar |
 Way to easy |
 Magic Cabbage School of Martial Arts |
 Vacation on Hawaii |
 gleeful |
 bubblo |
 blueman |
 BOOM BOOM BOOM |
 Splendid Mission |
 sparklingo |
 Watch Walker |
 Soy Angelino |
 autumn |
 K-POP TV News |
 cortiva6 |
 Nevada Teppanyaki |
 aerion99 |
 Golado |
 Maximum Pro |
 Joyce blog |
 Atlanta Business Information |
 Ansaso |
 Soft Feeling That Feeling |
 assa man |
 Yugo Girl I'm So Hot |
 nexaro |
 Experiences Living in America |
 arsnack |