
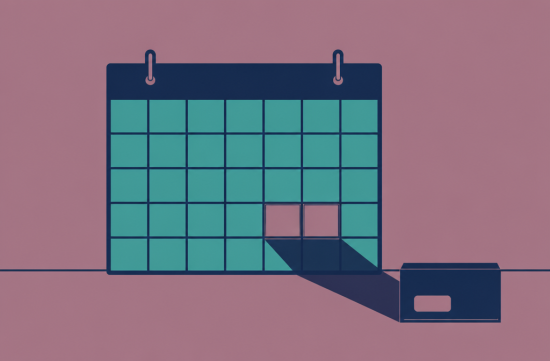
In the autumn evenings, the shadows of fallen leaves stretch long across the neighborhood streets. There's something that quietly follows like those shadows, only to suddenly reveal itself in the spring.
That something is New Jersey's uninsured penalty. Many people believe it has already disappeared at the federal level, so they are often surprised when they see it for the first time during state tax filing.
I heard about this a few years ago from a friend. They had been working as a freelancer and their insurance briefly lapsed, resulting in a state tax refund that was much lower than expected.
The individual mandate penalty under federal Obamacare has been $0 since 2019. However, New Jersey created its own law in 2018 to continue this system at the state level.
The official name is Shared Responsibility Payment, abbreviated as SRP. The law is called the New Jersey Health Insurance Market Preservation Act.
According to the New Jersey Department of Treasury, you must pay this amount for any month you and your family went without minimum essential coverage.
The calculation method involves choosing the larger of two options. One is a flat fee of $695 per adult and $347.50 per child, with a family maximum of $2,085.
The other option is 2.5% of the household income that exceeds the New Jersey filing threshold. The higher your income, the larger this amount will be.
However, there is also a cap. It is limited to not exceeding the average annual premium of the bronze plans in New Jersey.
According to an example provided by the Department of Treasury for the 2025 tax year, individuals can owe a minimum of $695 and up to a maximum of $4,908. I paused for a moment when I first saw those numbers.
This amount is not billed separately; it is included in the state income tax return, NJ-1040. If you are due a refund, it will be deducted from that amount first.
If you owe taxes, it is noted that penalties and interest will apply just like regular state income tax. This means it's not something you can simply overlook.
However, it's not mandatory to pay. There are several reasons for exemption.
First, individuals whose income is below the state filing threshold are automatically exempt from the penalty. In this case, no separate application is needed.
There is also a short gap exemption. If your insurance was lapsed for less than three months, you qualify, but remember that only one gap per year is recognized.
This provision is likely the most realistic safety net for freelancers or employees who have a month or two of gaps while transitioning jobs.
There is also an exemption for affordability. According to the Department of Treasury, if the lowest bronze plan or employer insurance exceeds 8.05% of household income, it is considered unaffordable.
Households with income below 138% of the federal poverty line, citizens who have been abroad for more than 330 days, and periods of incarceration are also exempt.
If you have faced hardships such as homelessness, eviction, domestic violence, family death, disaster, bankruptcy, or medical debt, you may consider applying for a hardship exemption.
Exemptions can be applied for using the online exemption application from the Department of Treasury, and you must report the exemption number on Schedule NJ-HCC when filing NJ-1040.
So, what you need to do right now is simple. Go through your calendar month by month to see if there were any months without insurance this year.
If there was a gap, check in advance if the reason qualifies for an exemption and gather the relevant documents. It's common for one or two documents to go missing if you wait until tax season to look for them.
The Department of Treasury's website also has a calculator to estimate potential penalties. The figures for this year will be updated later, so check back right before filing.
If you still don't have insurance, take a look at the state government marketplace, Get Covered New Jersey. Last year, open enrollment was from November 1 to January 31.
Based on that timeline, if you enrolled by December 31, coverage started on January 1, and if you enrolled by January 31, coverage began on February 1. Be sure to check the official site for this year's schedule.
According to state guidance, 8 out of 10 enrollees here qualify for premium assistance. The threshold may be lower than you think.
To find out which plan suits your medications or treatments, it's advisable to consult with your doctor or pharmacist. For personal matters like exemption eligibility, confirming with a tax professional is the most reliable approach.
I would choose to avoid creating gaps rather than just trying to avoid penalties. I believe it's better to spend that $695 on peace of mind for the year than to carry it like a shadow.
Before the leaves all fall, take a moment to pull out your insurance card from the drawer. Your spring tax paperwork will be much lighter.
 LuckyForest82

 LIZ Legal Information Blog |

 Karina's Blog |
 Jimbeam 88 |
 Taco Bell Candy Note Blog |
 Splendid Mission |
 morninpo |
 dewyo |

 breezem |

 silverleaf |
 eatontown blog |
 Kansas City Representative Singer |
 shadow 007 |
 sun walker |
 Choco Choco Star |
 midnight blue |
 honeypot |
 summer |
 adventure77 |
 flexible |
 Shintongbangtong Shin Naerin James Park |
 truepixel |
 Kathy's Blog |
 Hae Naem |
 quatspace |
 Marisol |
 Glassroom |
 Granola |
 joyfull yang |
 Olivia's Blog |
 Living in America and Writing Essays |