
Last week, while choosing a container of pollock roe at the local Korean market, I ran into an acquaintance. As soon as I greeted him, he sighed heavily. He mentioned that after retiring, his income had significantly decreased, but his Medicare premiums had actually increased.
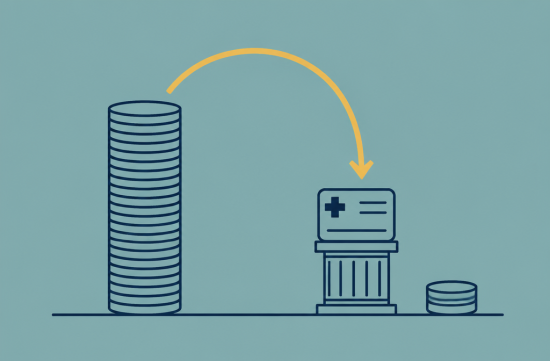
As I listened, I learned that the culprit was IRMAA. Its official name is Income-Related Monthly Adjustment Amount, which is an additional charge on Medicare premiums based on income. While delicious pollock roe can be a rice thief, this feels more like a wallet thief.
The key issue is the time lag. The Social Security Administration (SSA) determines this year's premiums based on income from two years ago. The 2026 premiums will be based on 2024 income, meaning the tax return filed last year for 2024 is the reference.
This creates a problem for those who worked full-time until 2024 and retired last year. Their current income has dropped significantly, but their premiums are calculated based on what they earned during their peak earning years.
Looking at the numbers makes it clear. The basic Part B premium for 2026 is $202.90 per month. If the modified adjusted gross income (MAGI) for 2024 exceeds $109,000 for individuals or $218,000 for couples, IRMAA kicks in.
In the first bracket, for individuals earning between $109,001 and $137,000, or couples earning between $218,001 and $274,000, the Part B premium rises to $284.10 per month. Additionally, there is a separate charge of $14.50 for Part D.
As the brackets increase, the rates rise sharply. For individuals earning between $137,001 and $171,000, the Part B premium is $405.80, and for those earning between $171,001 and $205,000, it is $527.40.
For incomes from $205,001 to $500,000, the premium is $649.20, which is more than three times the basic premium.
I was a bit shocked when I first saw this table. If your income exceeds the threshold by just $1, the entire rate for that bracket applies, which can feel quite unfair for those near the boundary.
Fortunately, there is a way out. If your income has decreased due to a significant life change recognized by the SSA, you can request a recalculation based on your recent income.
There are eight recognized reasons. These include marriage, divorce or annulment, and the death of a spouse. It also covers work stoppage due to your own or your spouse's retirement, as well as reduced work hours.
The remaining three reasons are somewhat rare. They include losing income-generating property due to fire or disaster, a company pension being suspended or reduced, and receiving a settlement due to employer bankruptcy or restructuring.
Many people get confused here. If you sold a house and had a large capital gain, or if you sold stocks and your income spiked, these do not fall under the eight recognized reasons. Such one-time income is generally not accepted as grounds for an appeal.
The application form is SSA-44. You can obtain it from the SSA website, fill it out with your reason, date, and expected reduced income for the year, and attach supporting documents.
If retirement is the reason, documents like your retirement confirmation from your company or your last pay stub can be useful. For a spouse's death, a death certificate is needed, and for divorce, an official court document is required.
You can submit the application by mail or by visiting a local Social Security office. Decisions typically take a few weeks to a couple of months. When sending original documents, be sure to ask how you will get them back.
Timing is also important. You can submit SSA-44 anytime within the year the reason occurred, and if the reason happened in the last three months of that year, you can submit it by March 31 of the following year.
If SSA-44 is denied, it's not the end. You can submit a request for reconsideration using form SSA-561 within 60 days of receiving the denial notice. If that doesn't work, you can escalate to a hearing with an administrative law judge.
Regardless of the reason, the SSA can sometimes make mistakes with the numbers. If you corrected your tax return but it hasn't been reflected, or if there was an error in IRS data, you can request a reconsideration based on that, so check the numbers on your notice first.
Since it's October, I'll mention timing again. The 2027 premiums will be based on 2025 income. The new year's premiums and IRMAA brackets are usually announced in the fall, and those affected will receive an SSA notice around the end of the year.
Returning to my acquaintance, he worked throughout 2024 and retired last spring. This fits perfectly as a reason for work stoppage, so I advised him to gather his retirement documents and apply.
If approved, the newly calculated premium will apply, and any excess amount already paid will be adjusted. Even a difference of $80 per month adds up to $960 in a year, so it's worth gathering a few documents.
However, everyone's income structure and tax reporting methods vary, so results will differ. It's advisable to check with a tax professional or Medicare consultant based on individual circumstances.
For those who find English documents daunting, you might consider using SHIP, a free Medicare counseling program run by the state government. It operates in New Jersey as well, and it's worth asking if they provide translation support.
If I were in his shoes, I would mark the end of the year on my calendar. Check the SSA notice, submit SSA-44, and remember the 60-day reconsideration deadline. Just remembering these three things could save you hundreds of dollars.
That day, my acquaintance bought two containers of pollock roe. He jokingly said that if he gets a refund on his premiums, one container is mine, so I made sure to remember that promise.
 TalkVibe

 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 AliAluAlo Blog |
 Living in New Jersey blog |
 breezelove |
 Anytime Journey |
 Korea News Economic News |

 honeypot |
 summer |
 adventure77 |
 flexible |
 Shintongbangtong Shin Naerin James Park |
 truepixel |
 Kathy's Blog |
 Hae Naem |
 quatspace |
 Marisol |
 Glassroom |
 Granola |
 joyfull yang |
 Olivia's Blog |
 Living in America and Writing Essays |
 Piano Teacher Blog |
 bearcup |
 explorer |
 dictionary |
 Mr Bull Jung |