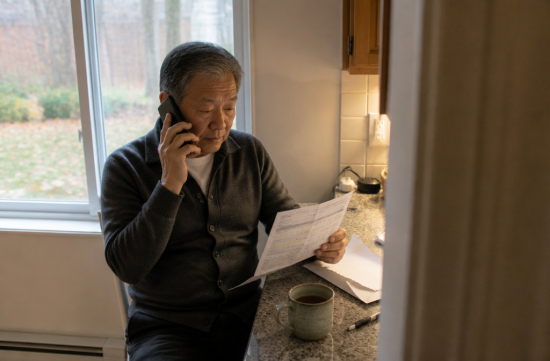
Last week, I opened my credit card statement and my hand stopped. There was a charge for several hundred dollars more than usual, and upon closer inspection, it was the annual fee. It stood out among my grocery purchases.
Since this is a charge that comes once a year, I often forget about it until I encounter it on my statement. So this time, I decided not to let it slide and to call the credit card company.
There is something called a retention offer. This refers to the benefits that credit card companies offer to retain customers who are considering canceling their cards.
Typically, these come in the form of credits that refund part of the annual fee, bonus points, or additional rewards if you spend a certain amount. There isn't a fixed table for this; it varies depending on the type of card and your usage history.
At first, I was skeptical. I wondered what a single phone call could change.
However, my thoughts changed when I saw the numbers. According to a survey released by the financial comparison site LendingTree in September of this year, 94% of cardholders who requested a waiver or reduction of their annual fee in the past year were successful.
In a similar survey last year, the success rate was 95%. This means that more than nine out of ten people manage to get something each year.
What's even more surprising is that not many people are making these requests. The same survey indicated that this year, the number of people requesting waivers has actually decreased, suggesting that remaining silent could lead to losses.
The timing of your call is important. It's best to call after the annual fee has actually been charged on your statement.
Before the charge, customer service representatives often do not flag you as a potential cancellation risk. It's only when the money has left your account that it signals you might actually leave.
Another thing to keep in mind is the refund period. American Express has a policy that if you cancel within 30 days of the statement closing date that shows the annual fee, they will refund it.
Other credit card companies have similar grace periods, but the duration varies by company and can change. It's safest to check your card's member agreement or contact customer service first. If you miss the deadline, you may not get a refund even if you cancel.
There's no need to elaborate too much. I simply said this:
The annual fee has been charged, but I'm considering whether to keep this card since I don't use it as much as I used to. I'd like to know if there are any benefits that could help me keep it.
The representative asked me to hold for a moment and then transferred me to the cancellation department. This is where the real game begins, and sometimes the first representative can find benefits for you.
In my case, I was offered additional points if I spent a certain amount within three months. While it didn't cover the entire annual fee, it was a condition I could accept using my usual spending.
If you're not satisfied with the offer, you can ask if there are other options available. There's no need to be rude; just asking calmly is sufficient. There are many experiences where people received different offers when they called back a few weeks later.
If nothing comes up, consider asking about downgrading. This means switching to a no-annual-fee card from the same issuer.
Downgrading keeps your account intact, unlike cancellation. Your credit history remains uninterrupted, and your credit limit stays active, which is less of a burden on your credit score. Be sure to ask if you can keep the points you've accumulated as well.
If you close the card entirely, your total credit limit decreases, which can increase your utilization rate. The older the card, the greater this impact, so it's best to keep cancellation as a last resort.
There are also some points to be cautious about. If you've received a retention offer on the same card within the last year, it's often the case that another offer won't come up.
The same applies if you've had the card for a short time. If you ask for benefits right after receiving the sign-up bonus, the card issuer may not be pleased.
And if you do receive an offer, make sure to write down the conditions. If you don't confirm the usage period, amount, and point accumulation timing, things could change later.
You can also inquire through an app chat that keeps a record of the conversation. However, it's often reported that the cancellation defense department is more frequently reached by phone.
Looking back, the call didn't take more than 15 minutes. That 15 minutes opened up a way to recover a significant portion of the annual fee, which is rare when calculated by the hour.
Honestly, making these calls can be a hassle. After going through several automated responses, you might feel like hanging up midway. It can also be daunting to argue with a representative.
However, this isn't a negotiation; it's something you can rightfully ask for as a customer. Credit card companies know that retaining existing customers is cheaper than acquiring new ones.
If I were you, I would call right in the month the annual fee is charged. If you delay and miss the refund period, you lose a negotiation card, so today, when I opened my statement, is the best day to act.
 SilverTrail84

 holy cow |
 Soy Angelino |
 SKy Face |
 gleeful |
 forevergee |
 Glow Yo |

 Amber H |
 zymit |
 Anytime Journey |
 Living in New Jersey blog |
 Way to easy |
 limestone |
 oster |
 daddyyo |
 neapolis |
 seadoll |
 ansdal |
 Vivid U.S. Regional Information |
 Vasila's Newlywed Blog |
 Arizona Cowboy |
 merry merry |
 Hoorah Ooorah |
 Fragile Me |
 Rowland Mama |
 foxtree |
 bayaa |
 loveyom |
 Coastal city |
 Spaghetti Flying Religion |
 My Town My Way Blog |