
These days, whenever ObamaCare comes up in conversation, everyone lets out a sigh. Many were shocked when they received their insurance premium notices this year, and now there's news that rates will rise again next year.
To get straight to the point, we are looking at another double-digit increase this time. So, I've gathered some important things to consider before the open enrollment period starts on November 1.
KFF analyzed the rate filings from 276 insurance companies nationwide, and the median increase is 15%. Most insurers have requested increases between 10% and 20%.
What's even more surprising is last year's numbers. The confirmed median increase for 2026 was 20%.
KFF pointed out that if this trend continues, premiums will have risen by more than a third in just two years. Honestly, salaries haven't increased by that much.
Texas is no exception. There are quite a few insurers in the individual market requesting double-digit increases.
The reasons cited by insurers include rising medical costs and drug prices, as well as the end of additional subsidies. The enhanced premium tax credit that was available during COVID will end by the end of 2025.
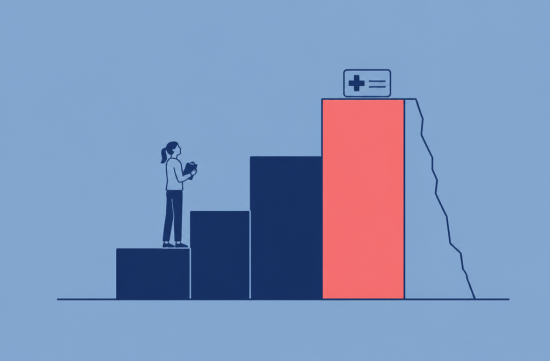
This is a significant change. Starting in 2027, insurance will only receive subsidies for income levels between 100% and 400% of the federal poverty line.
For a single-person household, 400% is $63,840. If you exceed this threshold by even $1, the subsidy will not gradually decrease; it will drop to zero. This is known as the subsidy cliff.
Additionally, starting from the 2026 income year, there will be no cap on the amount you have to pay back if you received too much in subsidies.
This means that if you reported a low income but then received a bonus or side income at the end of the year, you might have to pay back the excess when filing your taxes. This is something to be very cautious about.
People in Texas should pay special attention. Cigna and Baylor Scott & White will exit the Texas marketplace by the end of 2026.
If you are using plans from these two companies, you must choose a new plan this year. If you do nothing, the system may automatically switch you to another plan, but there's no guarantee that your primary care physician or medications will be covered.
So, what should you do before November 1? I'll list the steps in the order I recommend.
The first step is to realistically estimate your income for next year. Pull out last year's tax return and factor in any job changes, promotions, or side income plans.
If you are near the 400% threshold, you can lower your MAGI by increasing contributions to your 401(k) or HSA. However, since individual situations vary, it's advisable to confirm this with a tax professional.
The second step is to organize a list of the hospitals you visit and the medications you take. When you change plans, the network changes, so having this list will help you compare quickly.
The third step is to not only look at premiums but also consider deductibles and out-of-pocket maximums. A low monthly premium bronze plan could end up being more expensive for someone who frequently visits the hospital.
As a side note, starting in 2026, marketplace bronze and catastrophic plans will allow HSA enrollment. If you choose a high-deductible plan, it's worth considering the combination of tax benefits with an HSA.
The fourth step is to check the deadlines. Open enrollment runs from November 1 to January 15, 2027.
However, to have coverage starting on January 1, you must enroll by December 15. If you enroll after December 16, coverage will begin on February 1.
Originally, there was a federal regulation to move the deadline to December 15, but in June, a Maryland federal court blocked that change. Subsequently, CMS confirmed that the original schedule would remain.
Finally, if you have employer insurance options, consider comparing them during this time. Company insurance might be better than you think.
I personally find this situation quite frustrating. The burden is heavier for those who are sick or have ambiguous incomes.
While we can't change the system overnight, we can prepare. My belief is that we should not lose in the battle for information.
If comparing plans in English feels overwhelming, getting free assistance is also an option. You can find local navigators at HealthCare.gov, and you can call the marketplace call center to request interpretation services.
If I were you, I would finish estimating my income and organizing my hospital and medication list by the end of October, and start comparing plans in the first week of November. The site tends to slow down right before the deadline, and appointment slots fill up quickly.
Especially for Cigna or Baylor Scott & White members, don't delay. The chances that the automatically assigned plan will suit you are lower than you might think.
While we can't stop the premium increases, we can make the least painful choice for our situation. Let's make sure to carefully prepare this year.
 CupRamenArmy
 Real214Estate


 kuku 100 |
 novent |
 Silent Sea |
 Pointy |
 Idaho's Sumi's House |
 Hajiwon Blog Hair Salon |
 Make My Day |
 Texas Migration Story |
 Helpful Life Stories |
 Coding Elf |
 Nando Raldo |
 American Man in a Mask |
 wendra |
 silver |
 bada2002 |
 horizon |
 Nanana Nanana Nanana |
 victoria jung |
 Kkikki Ppappa Shout Out Loud |
 Lululala |
 Toaster Pizza Magic Show |
 Utah, the Most Livable State |
 nortrix |
 Mau Nui |
 novapixel |
 fixed |
 AL ALASKA |
 amola |
 History Repeats Itself |