
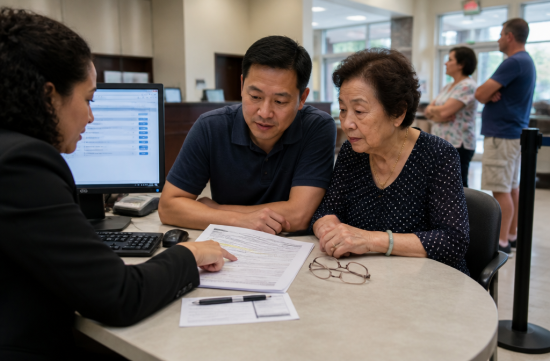
Did you know that something as simple as signing at the bank can lead to lawsuits between siblings later on? Adding a child's name to a parent's bank account is a common choice in Korean families.
When parents struggle with English documents or are in the hospital, this seems like the easiest way to help pay bills. I've seen many families do this, often at the suggestion of a bank employee without much thought.
However, a closer look at Florida law reveals that this convenience comes with significant hidden costs. Today, let's break down these issues one by one.
The first issue is ownership. Once a joint account is established, the child becomes not just an agent but a co-owner of the funds.
Legally, any co-owner can withdraw the entire balance. From the bank's perspective, both are considered equal owners, even if the money was saved by the parents over a lifetime.
The second issue is inheritance, which I personally find the most concerning. Florida Statute 655.79 presumes that if an account has two or more names, upon the death of one owner, the remaining owner receives everything.
This means that even if a will states that three children should share equally, the child whose name is on the account can take all the money. The account title takes precedence over the will.
Of course, this presumption can be overturned. It can be proven otherwise with evidence of fraud, undue influence, or clear and convincing proof of different intentions.
The problem is that this proof must be established in court. By then, the parents have already passed away, and siblings may end up hiring lawyers to fight over it.
The third issue is the child's debts. If a co-owning child is sued or has debts, creditors may be able to access that account.
Similar concerns arise if the child goes through a divorce. The parents' money could become entangled in unrelated disputes.
The fourth issue is Medicaid. When applying for Medicaid due to nursing home costs, joint accounts can complicate asset assessments.
Medicaid long-term care assessments have a look-back period of five years. If there are records of the child withdrawing money from the account, it may be considered a gift.
Let's also touch on taxes. Simply adding a name to an account does not immediately constitute a gift under IRS guidelines.
A gift is considered complete when the child actually withdraws money for personal use. The annual gift tax exclusion for 2026 is $19,000 per recipient.
Exceeding this limit does not mean immediate tax payment, but a gift tax return must be filed. It's good to remember that record-keeping is necessary.
Deposit insurance is another surprising point. The FDIC protects joint accounts up to $250,000 per co-owner.
If there are multiple joint accounts at the same bank, the total is aggregated for that limit. If the account balance is significant, it's worth calculating.
So what are the alternatives? Florida has a system called a convenience account, based on Statute 655.80.
This account is maintained in the name of one parent, and the child is designated as an agent who can only make deposits and withdrawals. Ownership remains with the parent.
The key difference is that there are no survivor rights. When the parent passes away, the money goes into the estate and is divided according to the will.
The Consumer Financial Protection Bureau (CFPB) also recommended accounts without survivor rights as a good alternative in their report on preventing elder financial exploitation. It's quite impressive that a public agency mentioned this.
Another option is a durable power of attorney. This allows parents to retain ownership while granting the child limited authority.
The power of attorney can cover not just bank accounts but also other asset management, making it quite versatile. However, it's wise to check in advance as different banks have varying forms and procedures.
Designating a pay-on-death (POD) beneficiary is another method. During their lifetime, only the parents can use the account, and after their passing, it transfers to the designated person.
If it were me, I would open a convenience account for everyday management and handle larger assets with a power of attorney and a will. I believe this combination allows for both convenience and fairness.
In Korea, it's natural to entrust bank accounts to family, but U.S. law views titles much more strictly. This gap seems to lead to frequent disputes in Korean families.
Inheritance, Medicaid, and taxes can vary greatly depending on family circumstances, so I recommend consulting a Florida elder law attorney or tax professional. If you already have a joint account, consider inquiring about the account type with your bank now.
 joyfulcitybuilder2006
 HeartSkyFox

 saffronroute |
 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 Yes Dorian |
 Kyo Sho |

 Tamfa Fan |
 Splendid Mission |
 Nando Raldo |
 American Man in a Mask |
 wendra |
 silver |
 bada2002 |
 horizon |
 Nanana Nanana Nanana |
 victoria jung |
 Kkikki Ppappa Shout Out Loud |
 Lululala |
 Toaster Pizza Magic Show |
 Utah, the Most Livable State |
 nortrix |
 Mau Nui |
 novapixel |
 fixed |
 AL ALASKA |
 amola |
 History Repeats Itself |