
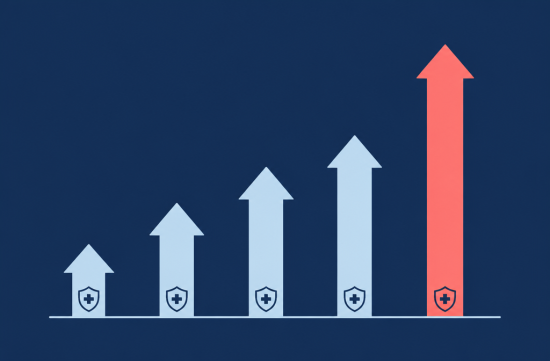
While having lunch, a coworker showed me their phone. It was news that Obamacare premiums are going up again next year, and when I saw the numbers, I thought I was going to choke on my kimbap.
Since I have company insurance, it doesn't directly affect me, but I immediately thought of my self-employed friends and the older members of my church who run businesses. So this time, instead of looking for luck, I decided to look for numbers.
According to the Michigan Department of Insurance and Financial Services (DIFS), the average rate increase request for individual insurance in 2027 is 14.2% from 10 insurers. This is before applying any subsidies.
The important thing here is the word "request." This is the number that insurers have submitted to raise rates, and the final rates will be confirmed after review by the state government.
According to ACASignups, which tracks rate disclosure data, the average was recalculated to 14.5% based on the final documents updated at the end of September. So whether it's a request or the final number, we're talking about rates in the 14% range.
Now, how much do the rates differ by insurer? This is where it gets really interesting.
The lowest request came from Priority Health at 11.1%. The highest was from UnitedHealthcare Community Plan at 25.5%. That's more than double the difference within the same state.
The Blue Cross family, which has the most enrollees in Michigan, also needs to be looked at separately. Blue Cross Blue Shield of Michigan requested 12.93%, while Blue Care Network requested 12.45%.
Oscar requested 11.9%, and Health Alliance Plan (HAP) requested 12.6%. McLaren Health Plan submitted 16.25%, and Alliance Health and Life requested 14.05%.
Looking at all these numbers, it seems that the average of 14% hides quite a lot. Depending on which company's plan you use, the experience can vary significantly.
So why are rates going up like this? The common reason cited by insurers is the end of enhanced federal subsidies.
The enhanced premium tax credits created during COVID expired at the end of 2025. After that, the average medical costs for remaining enrollees are expected to rise as healthier individuals leave the insurance market.
In fact, Blue Cross Blue Shield of Michigan noted in their documents that they expect individual enrollment to drop by more than 30% by 2027. This is a significant change from the insurers' perspective.
Rising medical and drug costs are also contributing factors. Blue Cross indicated that they expect medical and drug costs to rise by 10% by 2027.
Speaking of subsidies, there's one more thing to note. With the end of enhanced subsidies, a so-called "subsidy cliff" has re-emerged, where those earning over 400% of the federal poverty line will receive no subsidies at all.
If your income is near this threshold, the cliff may be scarier than the rate increase. How you estimate your income can significantly affect your subsidies.
On the other hand, if you are receiving subsidies, the "14% increase" won't directly appear on your bill. Subsidies adjust based on the benchmark plan price, so the actual burden will vary for each person.
So before panicking or feeling relieved just from the news headline, it's best to get an estimate based on your plan.
The open enrollment for 2027 plans starts on November 1 at healthcare.gov. To receive coverage starting January 1, you must enroll by December 15.
Given the legal issues surrounding the final registration deadline, be sure to check the announcements on healthcare.gov before applying.
What I realized while putting this together is that automatic renewal is the most dangerous option. If you do nothing, your current plan will carry over, which could be from a company with a high rate increase.
If I were in your shoes, I would check the 2027 prices for my current plan in early November and compare two or three other insurers in the same metal tier side by side.
It's important to look at more than just the premium; you should also consider deductibles and out-of-pocket maximums. There are plans where the monthly premium is low, but you end up paying much more when you go to the hospital.
You should also check if your regular hospital and primary care physician are in the network. It's surprisingly common to switch to a cheaper plan and find that you can't see your regular doctor.
If you take regular medications, make sure to check if those medications are included in the new plan's formulary, and if you're unsure, consult with your doctor or pharmacist to confirm alternative medications as well.
Be thorough in re-estimating your income. If you underestimate your income for next year, you could end up having to pay back subsidies during tax season, and don't assume there are limits on the amounts refunded like before.
If you're overwhelmed by English documents, finding a free enrollment assistant (Navigator) can be a good option. You can search for them by region on healthcare.gov.
Honestly, every year around this time, I sigh at the news about premiums, but this year, the differences among insurers make it a worthwhile year to compare.
A four-leaf clover won't be seen if you just sit still in the grass. Insurance is the same. You have to dig around to find that little luck of a plan that has risen less.
 ChouDoor

 Old English |
 nixxon |
 LIZ Legal Information Blog |

 Karina's Blog |
 Jimbeam 88 |
 Granola |
 aaoaa |
 juniper |
 oflare |

 AL ALASKA |
 amola |
 History Repeats Itself |
 Doori Ark |
 Rainbow Bridge to the Sky |
 Sunny Fullerton |
 U.S. Weather Bureau News |
 GOGO SING |
 Gold Bar |
 Banana Style Life |
 Tesla X |
 urbanmint |
 forestcloud |
 forever young |
 Arlington house |
 liquid asset |
 Who's watching? |
 eclipse |
 quietwave |