
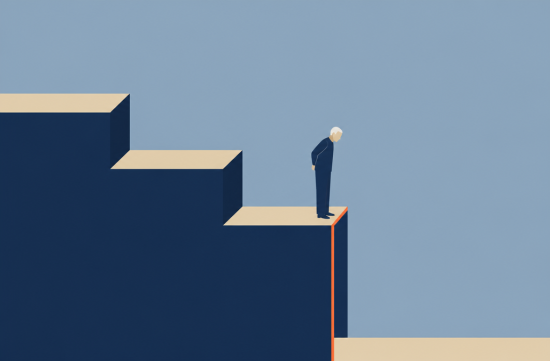
Recently, at a church fellowship meeting, an elder quietly asked me about something. Last year, there was almost no tax on his pension, but this year, after withdrawing a bit more from his IRA, he noticed a significant increase in taxes.
Looking at the numbers together, the reason became clear. He had fallen into the "cliff" zone of New Jersey's retirement income exemption, known in English as the Pension Exclusion.
Many people are surprisingly unaware of this. So today, I will carefully outline how this system works and where people tend to stumble.
First, let's start with the basics. According to the New Jersey Division of Taxation, this program allows certain retirement income, such as pensions, annuities, and IRA withdrawals, to be excluded from state income tax calculations.
There are two qualifications. You must be at least 62 years old on the last day of the tax year or have received a disability determination under Social Security.
Additionally, your total income must be $150,000 or less for that year. This is the key point of today's discussion.
If your total income is below $100,000, you can use the maximum exemption limit. For joint filers, it's $100,000; for singles and heads of household, it's $75,000; and for married individuals filing separately, it's $50,000.
If your total income is between $100,001 and $125,000, the exemption decreases as a percentage. For joint filers, 50% of taxable pension income is exempt; for singles, it's 37.5%; and for married individuals filing separately, it's 25%.
Between $125,001 and $150,000, the exemption decreases further. Joint filers get 25%, singles get 18.75%, and married individuals filing separately get 12.5%.
And if you exceed $150,000 by even $1? The exemption drops to zero. It doesn't gradually decrease; it just cuts off completely.
For example, if a couple filing jointly has a pension of $80,000 and a total income of exactly $150,000, they would receive a $20,000 exemption, which is 25% of $80,000.
However, if the same couple's investment income increases their total income to $150,100, the $20,000 exemption disappears entirely. Their income increased by $100, but their taxable income increased by over $20,000.
Honestly, when I first saw the table, I was a bit shocked. This structure is referred to as a cliff in tax terms, and it truly lives up to its name.
Therefore, timing your income after retirement is crucial. If IRA withdrawals, capital gains from selling a house or stocks, and part-time income all occur in the same year, it's easy to cross this threshold.
If I were in that situation, I would roughly add up my income around October each year. If I'm near the threshold, delaying large withdrawals or sales until January of the following year could make a significant difference.
There is good news as well. New Jersey does not impose state income tax on Social Security benefits.
Additionally, individuals aged 62 or older with earned income below $3,000 can use the Other Retirement Income Exclusion if they haven't fully utilized their pension exemption limit. However, there are specific conditions, so be sure to check the instructions on that year's tax return.
What if only one spouse is over 62? Even if filing jointly, the exemption only applies to the qualifying spouse's pension or IRA withdrawals.
There is also a bill proposing to change the $150,000 threshold. In the 2026-2027 session, A3824 and S3689 were introduced to eliminate the income cap and allow the first $150,000 of pension income to be fully exempt, with 50% exempt above that amount.
There are also bills like A1611 that propose to eliminate the income cap altogether. However, as of the time I checked, none of these have passed. For now, you should plan based on the current $150,000 threshold.
To share my thoughts briefly, I believe this cliff structure needs to be fixed. It doesn't seem fair that a $100 difference can lead to thousands of dollars in taxes.
However, I'm not sure if the solution should necessarily be to eliminate the cap. If high-income individuals receive benefits, it could drain the state budget, and that burden would ultimately shift to other services.
Personally, I think a phase-out approach, where the exemption gradually decreases as income rises, would be the most realistic. This would protect middle-class retirees while also reducing financial burdens.
In summary, total income below $100,000 allows for maximum exemption, up to $150,000 allows for partial exemption, and above that, there is no exemption.
If you're near the $150,000 mark, consider timing your withdrawals and asset sales carefully. A one-year difference can lead to significantly different outcomes.
Taxes can vary greatly depending on individual circumstances. Before making major decisions, I recommend consulting a tax advisor or financial expert.
That day, the elder mentioned he would reconsider his withdrawal plans for next year. I also learned a lot from this opportunity. If you know someone in a similar situation, please share this article with them.
 BlueSummit74


 MEDBIO American Doctor Blog |
 Burbank Lee |
 vibranto |

 sparkling |
 oh my salami |
 Margarine Daebimama |
 choi family |
 santo melon |
 eatontown blog |
 Real Estate |
 Forest Gump |
 Real Estate Investment Korean American |
 Dollydori, Lover of Movies |
 dmzline |
 travelo |
 American Food Information & Calories |
 Splendid Mission |
 sparklingo |
 Watch Walker |
 Soy Angelino |
 autumn |
 K-POP TV News |
 Nevada Teppanyaki |
 aerion99 |
 Golado |
 Maximum Pro |
 Joyce blog |
 Atlanta Business Information |