
Last week, while having brunch with a friend, we talked about her mother. "I heard my mom gets a $6,000 deduction, does that just come automatically?" she asked, and I paused for a moment.
To put it simply, it is automatic, but the amount is reduced based on income. So now, in October, is a great time to check.
This deduction is part of the senior deduction included in the One Big Beautiful Bill Act that passed last year. According to the IRS, if you are over 65, you can receive an additional $6,000 deduction per person.
The applicable period is from the 2025 to 2028 tax years. The key point is that it is not a permanent program but a limited-time offer for four years.
If both spouses are over 65, each can receive $6,000, totaling up to $12,000. As of this year, if you turn 65 by December 31, you qualify.
Many people are also unaware that this is separate from the existing additional standard deduction for those over 65. As of 2026, the existing additional amount is $2,050 for singles and $1,650 per person for couples.
So, for a single senior, the structure is the basic standard deduction of $16,100 plus $2,050, and then an additional $6,000 on top of that. Just looking at the numbers, it seems quite legitimate.
And you can receive this deduction whether you itemize or not. This means that those who itemize due to mortgage interest or property taxes have no reason to miss out.
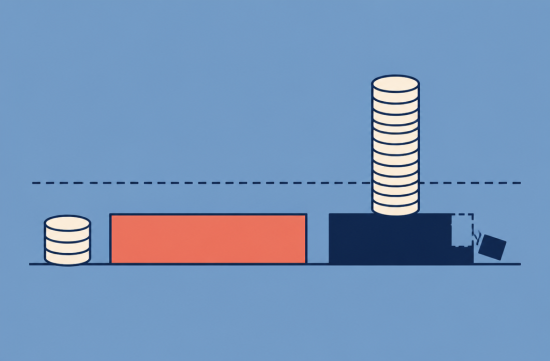
The issue is the income limit. If your MAGI exceeds $75,000 for singles or $150,000 for married couples filing jointly, the deduction is reduced by 6% of the excess amount.
For example, if a single person has a MAGI of $85,000, the excess of $10,000 will reduce the deduction by $600, resulting in a total deduction of $5,400.
If a couple has a MAGI of $170,000, the excess of $20,000 will reduce the deduction by $1,200 each, resulting in $4,800 per person, or a total of $9,600.
Once singles reach $175,000 or couples reach $250,000, the deduction is completely eliminated. For those in this range, a small change in year-end income can make a significant difference.
Here, MAGI can generally be considered the same as AGI. Only those with special items like foreign income will have a slightly higher amount.
My friend's mother was right on this threshold. With her pension, IRA withdrawals, and stock sales combined, it seemed she would slightly exceed $75,000.
So the real question was, "What can we do in the remaining two months of the year?" I'll summarize the methods I found.
The first is the timing of additional withdrawals from the IRA. If the money isn't needed this year, simply delaying it until January can lower this year's AGI.
The second is a Roth conversion. The amount converted counts as income for that year, so for those near the deduction threshold, it might be better to reduce the conversion amount or spread it over multiple years.
The third is capital gains from selling stocks or funds. Deferring realized gains to next year or offsetting them with losses can change the numbers.
The fourth is the QCD for those over 70.5 years old. A qualified charitable distribution sent directly from an IRA to a charity does not count as AGI.
The QCD limit for 2026 is $111,000 per person. It can also be used to satisfy RMDs, making it a great tip for those who regularly donate to churches or organizations.
One thing to be cautious about is that if other income increases, the taxable portion of Social Security benefits may also increase, so those on the threshold may see a more significant effect than expected.
Also, couples filing separately cannot receive this deduction at all. A valid Social Security number is also required.
The deduction is calculated on Schedule 1-A, so if you are filing yourself, make sure you don't overlook this form. It seems some people miss it, thinking the software will handle everything.
Of course, this is a general explanation of the structure, and results can vary significantly based on individual circumstances, so be sure to check with a tax professional or CPA. Especially with Roth conversions, it should be considered in conjunction with long-term planning.
Personally, I find it a bit disappointing that this program ends in 2028. For those living on fixed incomes, a $6,000 deduction is a significant amount.
Since it was created, I think it would be great if it could be made permanent or if it could be structured to benefit low-income seniors more directly. Deductions only matter to those who pay taxes.
In any case, what needs to be done now is simple. Add up the income received so far this year, and if you're near $75,000 or $150,000, take action before December.
If I were in that situation, I would probably check my bank app and investment accounts this weekend before my parents' 1099 forms come out. My friend ended up sitting down with her mother that weekend to do the calculations.
 CoinGirl


 vibranto |
 sparkling |
 oh my salami |
 saffronroute |
 You Only Live Once |

 garlic bread |
 Popular Song Exciting Song |
 Yo Lock Me Up |
 California Information News |
 gleeful |
 Burbank Lee |
 Olivia's Blog |
 Bushing Around Life |
 Active |
 Cherokee Rose |
 Kor. Master |
 Holey Moley |
 Conflite Teacher |
 Hodong Prince Over Flex |
 Mist inn |
 citrus pop |
 Onion Ring |
 phoenixia |
 viewtop |
 loverun |
 Kim Do Sun |
 SEVEN SEVEN |
 yentra |
 Make My Day |