
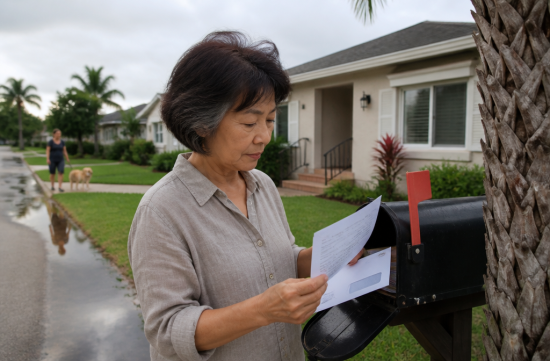
These days, the air on my morning walk feels a bit different. When the humid breeze blows, the expressions of the neighbors start to relax. They look like they can finally take a breath.
However, a few days ago, a neighbor lady mentioned something that stuck with me. She said that since the season is almost over, she was thinking of just canceling her flood insurance. I found myself stopping in my tracks.
Let's start with the calendar. The Atlantic hurricane season officially lasts until November 30. Being mid-October means we are still right in the middle of the season.
People in this neighborhood remember. Hurricane Ian made landfall on September 28, 2022. We learned the hard way that we can't let our guard down just because it's fall.
There's a bigger trap to consider. The National Flood Insurance Program (NFIP) run by FEMA typically requires a 30-day waiting period for new policies to take effect. This means that if you rush to get coverage after a storm warning, it might already be too late.
There are exceptions, like when you sign up at the same time as closing on a loan. But that's not a common situation for retirees living alone. So, canceling and then trying to get coverage again can be riskier than you might think.
And there's one important fact you need to know. Standard homeowners insurance does not cover flood damage. Wind damage and water damage are covered by completely different policies.
There are also limits on what you can receive through the NFIP. The maximum for a residential building is $250,000, and for personal property, it's $100,000. If your home is worth more than that, it might be worth looking into private flood insurance as well.
If you have Citizens insurance, you need to pay extra attention. The phased mandatory schedule set by the state legislature is nearing its end. Most residential policies that include wind coverage are affected.
Starting in 2024, coverage for homes valued at over $600,000 will be required, and in 2025, it will apply to homes valued at over $500,000. As of January 1 of this year, homes valued at over $400,000 must have flood insurance. And by January 1, 2027, all remaining policies will be included.
The required coverage amount must be equal to or greater than the Citizens home coverage or the NFIP maximum of $250,000. Policies for condo unit owners, renters' personal property, and those without wind coverage are exceptions. Check the first page of your policy to see where you stand.
We can't overlook the news from Washington either. The NFIP has been surviving on short-term extensions since the 2017 fiscal year. The temporary budget law signed on September 2 has extended it until December 11 this time.
This is important because if reauthorization doesn't happen by that date, new enrollments and renewals will stop. Existing policies will remain in effect until their expiration date, but those whose renewal date falls around that time may experience a gap in coverage.
Honestly, this part is a bit frustrating. It seems wrong to keep the safety net for so many households on a few-month extension. I believe long-term reauthorization is necessary, regardless of political affiliation.
There's good news too. The city of Fort Myers received a Class 6 rating in FEMA's Community Rating System (CRS). As a result, since October of last year, city NFIP policyholders have been receiving a 20% discount on their premiums.
This city had been stuck at a Class 9 rating with a 5% discount since 2020. Considering that, it's quite a significant change. City officials have stated it's the highest rating ever achieved.
Citizens, Cape Coral, Sanibel, Bonita Springs, and unincorporated Lee County are at a Class 5 rating with a 25% discount. Fort Myers Beach lost its rating after Ian but regained a Class 5 rating. A 25% discount applies to policies issued or renewed after April 1 of this year.
So, when you receive your renewal notice, make sure to check if the discount has been properly applied. The numbers can be more different than you might expect.
If you're planning to sell or rent your home, there's one more thing. Florida has expanded flood disclosure requirements starting October 1, 2025. Sellers must disclose not only the insurance claim history but also any flooding damage they were aware of during their ownership.
When renting for more than a year, landlords must provide a flood disclosure form before the lease is signed. If this is overlooked and the tenant's belongings get significantly damaged, it could be grounds for contract termination. Keeping good records of insurance is ultimately about protecting your property.
So, what should you do now? First, pull out your flood insurance policy and check the renewal date. If it's around December 11, it's a good idea to handle the renewal paperwork in advance.
Next, consider the coverage amount. If you've remodeled or construction costs have risen, the previous amount may no longer be sufficient. Also, check if you have separate personal property coverage.
If you're a Citizens policyholder, verify whether your home coverage amount is subject to the mandatory requirements starting in January. If it is and you don't have flood insurance, there could be issues with renewal.
Finally, take a round of photos inside your home. Capture the condition of appliances, furniture, and walls. This is invaluable evidence when it comes time to file a claim.
Insurance structures and tax issues vary by individual circumstances, so be sure to consult with an insurance agent or expert. Especially for those living on a fixed income, it's wise to balance insurance costs with coverage.
That day, I told the neighbor lady, it's easy to cancel, but it takes 30 days to get coverage again. I can still picture her nodding in understanding.
The cool breeze of the season is truly appreciated. But if it were me, I would use this season as a time for checks rather than cancellations. Water doesn't wait for the calendar.
 casanova

 saffronroute |
 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 Joyce 77 |
 Blog Korea |
 Jimbeam 88 |

 Way to easy |
 Your Curiosity Resolved |
 Chino Min |
 nexabyte |
 moonshine 7 |
 Sunset Oregon |
 victoria 68 |
 golfmaster |
 Montgomery Mom |
 squidogame |
 Noodle Noodle |
 Rhode Island Good People |
 Big North |
 Famous Attractions in the United States |
 Jin Soo V |
 Starbucks Reserve Roastery Closure |
 peppermint |
 Stable Co. |
 Purple Moons, |
 International Court |