
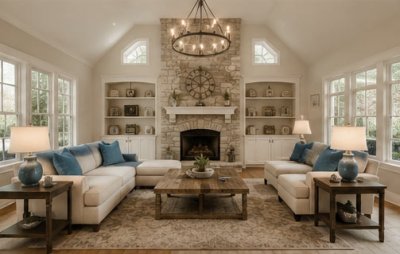
I've seen many buyers who fall in love with a property during an open house near Preston Hollow and decide on the spot. There have been cases where buyers were so taken by the kitchen island and natural light that they made an offer without any inspection clause. Ultimately, after the contract was signed, issues like foundation cracks and old plumbing were revealed, leading to thousands of dollars in additional repair costs.
Looking at the recent market in Dallas, it's risky to make decisions based solely on emotions. According to Zillow, the average home value in Dallas is $311,326, which is a 2.7% decrease from the previous year (as of July 2026), but the median price of homes sold is much higher at $494,900 (as of August 2026, based on 5,343 transactions). This indicates that there is a significant price variation depending on the neighborhood, even within the same time frame. Redfin data shows that the average market exposure time is 41 days. This means it's not the hyper-competitive market it used to be, reducing the urgency to act impulsively based on emotions.
Nevertheless, one area where first-time homebuyers often overlook is budgeting. Many focus only on the mortgage principal and interest, neglecting property taxes, homeowners insurance, and maintenance costs. Texas has no state income tax but relatively high property taxes; according to worldpopulationreview.com, the average effective tax rate in the state is 1.63%, and it can go up to 1.81% depending on the county (according to tax-rates.org). For a home priced around $490,000, the annual property tax could be around $8,000, which must be included in the monthly budget.
Skipping the inspection is also a common mistake. Even though the market exposure time has increased, homes in good school districts or those that have been well remodeled still attract multiple offers. In such moments, if buyers rush and remove all conditions, they may discover issues only after the contract is signed, as seen in previous examples.
Closing costs can also be underestimated. Typically, they range from 2% to 5% of the sale price, meaning for a home priced around $490,000, you might need between $10,000 and $25,000. If you only prepare funds for the down payment and neglect to set aside money for closing costs, you could find yourself short on funds at the last minute.
The most fundamental issue is the habit of looking at properties without mortgage pre-approval. If you find a home you love and then check loan terms, you may miss the timing for a competitive offer. Since comparing rates from multiple lenders takes time, it's safer to get pre-approved by at least three lenders before you start house hunting. Even with the same credit score, the rates offered by lenders can differ by more than 0.2 percentage points, so if you decide based only on the first lender's terms, you could end up with a significantly higher total interest burden over a 30-year mortgage.
I've also seen buyers pour all their reserves into the down payment. Unexpected expenses, such as air conditioning or water heater failures, often occur shortly after moving in. Instead of maximizing the down payment, it's more stable to keep some reserves for the first few months after moving in.
It's also important to consider commuting distance and resale potential. I've seen many cases where buyers regret their decision after a few years due to job changes or school changes for their children, simply because they were drawn to the kitchen or natural light. It's better to assess whether you plan to live there for at least five years and whether the neighborhood has consistent demand in the resale market.
When looking into school districts preferred by Korean families, refer to ratings from GreatSchools or Niche, but keep in mind that school boundaries change frequently, so it's advisable to verify the assigned school for the specific address before purchasing. It's not uncommon for assigned schools to differ even with just one street in between in Dallas.
This article is not investment or legal advice, and tax and loan conditions may vary by county and individual circumstances, so it's recommended to consult with a professional before finalizing any contracts.
 AssaultMon
 GymGhost



 |

 Premium Gas Camp |

 CA Real Estate |

 cheesepup |

 breezem |
 Aura-Infused WACAM |
 Gupabal MissKorea |
 NEXT ROUND |
 Giant Squid and Sweet Potato Soup |
 Best Frozen Yogurt |
 Sammy Beach |
 Bliss O |
 blue ocean |
 greenlight |
 Watanaka Karametibaksa |
 castle |
 xelton52 |
 carefree |
 vrixen73 |
 AZ Road Master |
 Victory 1988 |
 summita |
 business lim |
 Colorado Lee |
 Make My Day |
 Fros Pro |
 lioness |
 La Bean |
 American History This and That |
 Monte Sori |