
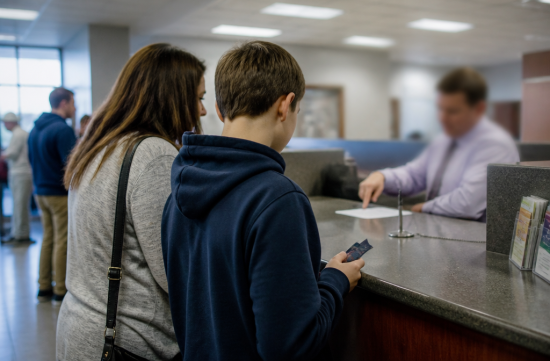
This morning, while waiting for my latte at a local café, I inadvertently overheard a conversation at the next table. They were trying to open their child's first account, and the bank employee asked whether they wanted a checking or custodial account, which left them confused.
Honestly, I was also unsure about the difference between the two. So, I ordered another cup of coffee and did some research.
To put it simply, the two serve completely different purposes. One is a wallet for everyday use, while the other is more like a gift box that is set aside in the child's name.
First, let's look at the minor checking account. Typically, a parent is a joint account holder.
For example, the Chase High School Checking account is aimed at teenagers aged 13 to 17 at the time of account opening, with a parent or guardian as a joint owner. There are no monthly maintenance fees.
There are also products for younger children. The Chase First Banking account is for kids aged 6 to 17, but the parent must be the account owner and must have a Chase checking account to open it.
The advantage of these accounts is that the child can make purchases with a debit card in their name and parents can view spending through the app. It's perfect for practicing money management.
However, there's something to keep in mind. Since it's a joint account, parents can withdraw the money, and legally, it's hard to consider it solely the child's money.
Now, let's talk about custodial accounts. Commonly referred to as UTMA accounts, these are managed by an adult, but the child is the owner of the money from the start.
Here's an important point: once money is deposited, it is treated as a gift to the child and cannot be withdrawn.
The custodian must use the money solely for the benefit of the child. This means it cannot be used for the parent's car payments or living expenses.
Additionally, custodial accounts can include not just bank deposits but also investments in stocks or funds through a brokerage. Many families consider this option for money they plan to set aside for a long time.
So, when does the child gain control? According to New Jersey UTMA law, money deposited as a gift during the child's lifetime is generally transferred to the child when they turn 21.
If the depositor specifies otherwise, it can be transferred at an earlier age between 18 and 21. It's a good idea to check the paperwork when opening the account.
I was also curious about depositor protection. According to FDIC guidelines, UTMA accounts in the form of bank deposits are considered the child's individual accounts and are protected up to $250,000.
The custodian's own deposits, even at the same bank, are calculated separately. This was a reassuring aspect.
Moving on to taxes, I need a bit more coffee. Any interest or dividends generated in a custodial account are counted as the child's income.
According to IRS guidelines, in 2026, the first $1,350 of unearned income for the child is tax-free, and the next $1,350 is taxed at the child's rate. Income exceeding $2,700 is taxed at the parent's rate, known as the kiddie tax bracket.
We also need to check the amount that can be deposited in a year. The annual gift tax exclusion limit for 2026 is $19,000 per recipient, so as long as you stay within that limit, there's no gift tax reporting requirement.
What surprised me the most was the impact on college financial aid. Custodial accounts are considered the child's assets for FAFSA purposes.
Student assets are assessed at a maximum of 20%, while parent assets are assessed at a maximum of 5.64%. This means that the same amount of money can significantly affect financial aid calculations depending on whose name it's in.
Therefore, if college funding is the goal, many articles recommend comparing other options like a 529 plan. It's important to evaluate what fits your family's situation.
The parents at the next table were also deep in thought about this point. It was surprising to me that money set aside in the child's name could potentially be detrimental to scholarship calculations.
To summarize, if the goal is to manage allowance and practice using a card, a minor checking account is the way to go.
If you want to grow money given as gifts like New Year's money or congratulatory gifts for the child, a custodial account is more suitable. However, you must accept that the child will have full access to the money once they reach a certain age.
Each product has different age requirements, fees, and whether a parent account is needed, so be sure to check the bank's official guidelines before opening an account. The impact on taxes or financial aid can vary based on individual circumstances, so consulting a tax professional is advisable.
One more tip: when opening a checking account, it's a good idea to take your child to the branch. Hearing the staff's explanation and receiving the card firsthand can be a valuable learning experience.
If it were me, I would start with a checking account to help the child get a feel for spending money, while keeping larger sums separate for management. It seems crucial to keep spending and saving money distinct.
To put it succinctly, like espresso, keep the wallet and gift box separate. When it comes to your child's first account, if you're confused, start by clarifying the purpose.
 SbuxFake

 morvex37 |
 Ari Songhan American Immigration Life |
 Bearded Strawberry Smoothie |
 Heart Ticker |
 Duck Duck Go |
 quiet river |
 chocolate |
 Living in New Jersey blog |
 Uptown |

 newyorker 101 |
 coffeee |
 |
 Christopher |
 sylven |
 Sammy Beach |
 Bliss O |
 blue ocean |
 greenlight |
 Watanaka Karametibaksa |
 castle |
 xelton52 |
 carefree |
 vrixen73 |
 AZ Road Master |
 Victory 1988 |
 summita |
 business lim |
 Colorado Lee |
 Make My Day |