
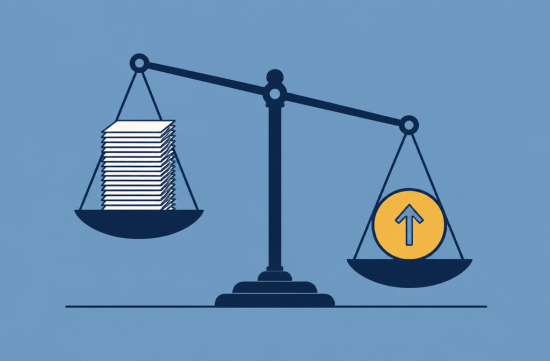
A while ago, a friend of mine sighed while buying me coffee. She had spent weeks preparing her tax returns, bank statements, and business plans perfectly, only to have her SBA loan rejected.
When I asked if she had missed any documents, she said no. The bank representative's explanation was brief: the numbers didn't add up.
That statement lingered in my mind, so I spent a few days researching. To cut to the chase, the real reason for rejections is often more about numbers and structure than the volume of paperwork.
The first thing that gets scrutinized is cash flow. Banks look at the debt service coverage ratio, commonly referred to as DSCR.
In simple terms, it measures how much more money is left over from the business compared to the principal and interest that needs to be paid over a year. Industry data suggests that most lenders set a benchmark between 1.15 and 1.25 times.
This means if you owe $100, you should have between $115 and $125 left over. Even with a good credit score, falling short of this ratio is the most common reason for rejection.
My friend's store had decent sales, but she had inflated her expenses to reduce taxes, resulting in a low net profit on paper. Tax savings and loan assessments are essentially working against each other.
The second factor is the credit score. In fact, the SBA does not officially set a minimum personal credit score.
However, in practice, each lender has its own criteria, and many expect scores around 680. Ultimately, even though it's the same SBA loan, the threshold varies depending on which bank you approach.
There's also a recent change. The FICO SBSS score requirement of a minimum of 155 for small 7(a) loans under $350,000 has been eliminated as of March 1, 2026.
Does that make it easier? Not necessarily. While the SBA has removed the requirement, banks will still conduct their own assessments, and many may continue to look for that familiar score.
The third factor is how much of your own money you are putting in. Starting June 1, 2025, the SOP 50 10 8 requires that new businesses and business acquisitions contribute at least 10% of the total project cost as equity.
Here, a new business refers to one that has been operating for less than a year and is generating revenue. The 10% is based on the total cost, including acquisition price, fees, operating capital, and closing costs, not just the loan amount.
There is a way to cover this amount with a seller note from the seller, but it must be under a complete standby condition where neither principal nor interest is paid during the loan term, and only half of the required equity is recognized.
And the part that will resonate most with our Korean community is the fourth factor: the citizenship requirement for owners.
According to SBA policy announcements, starting March 1, 2026, to qualify for 7(a) and 504 loans, 100% of the direct or indirect owners must be U.S. citizens or nationals, and the primary residence must be in the U.S.
If a permanent resident holds even 1% of the equity, the entire business is excluded from eligibility. This also applies if ownership is indirect through a holding company or trust.
This is an issue that cannot be resolved no matter how well the paperwork is prepared. If a couple jointly owns a business and one is a permanent resident, they need to check the equity structure before applying.
Honestly, I find this aspect a bit disappointing. There are many permanent resident business owners who have diligently paid taxes and maintained their stores in the community, and I think this will feel like a significant barrier in practice, regardless of the intent of the policy.
Of course, I understand the need for strict qualifications given that these loans are government-backed. However, I hope no one loses time and money due to a lack of awareness about the changes.
One more thing: the new operating guideline SOP 50 10 8.1 was announced on August 14 and will apply to SBA loan applications starting October 1. Announcements like the citizenship requirement and the elimination of the SBSS score have been consolidated in this guideline.
In particular, there are many reports that the requirements for business acquisition loans have become more stringent, so if you are looking to buy a store, it's a good idea to recalculate based on the latest standards.
So what should you do first? I would check three things before gathering paperwork.
First, the identities and equity percentages of all owners. Second, the debt service coverage ratio calculated based on the most recent tax returns. Third, how much cash I have on hand, not borrowed money.
If you've already been rejected, ask the bank for specific reasons. Depending on whether it's due to cash flow, credit, or eligibility, the next steps can vary significantly.
In Missouri, there are free consulting services available through the Small Business Development Center (SBDC) and the SCORE mentoring program. If you ask them to review the numbers before going to the bank, it can help reduce unnecessary trips.
My friend is currently reorganizing her books from this year. She learned that numbers come first, not paperwork, and she smiled while saying that. I hope all the business owners preparing for this will hear good news this time.
 SilverStar

 Investment Beginner Company Information Encyclopedia |
 Always Dreaming of Big Success |
 happy 9 |
 coloradoman |
 pintos |
 Savion |
 U.S. College Admission Information |

 Flying Shooting Star |
 mortrix |
 Lim Ario |
 American Food Information & Calories |
 Hawaii Maui Kahului |
 calvorn |
 fernando park |
 newyorker 101 |
 coffeee |
 |
 Christopher |
 sylven |
 Sammy Beach |
 Bliss O |
 blue ocean |
 greenlight |
 Watanaka Karametibaksa |
 castle |
 xelton52 |
 carefree |
 vrixen73 |
 AZ Road Master |
 Victory 1988 |