
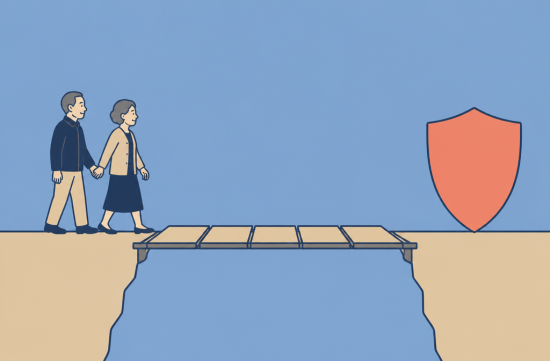
These days, I hear a common concern from those around me. Parents who have finally received their green cards after the immigration process are now worried about hospital bills.
I initially thought that if they were over 65, they would automatically qualify for Medicare. But that's not the case at all.
Medicare has specific residency requirements for immigrants. To qualify, they must have lived in the U.S. as a permanent resident for five consecutive years.
The key point here is the five years as a permanent resident. Time spent in the U.S. on a visitor visa or student visa does not count toward this five-year requirement.
And even after completing the five years, it's not the end of the story. If they haven't worked and paid taxes in the U.S., meaning they lack sufficient work credits, they won't be able to receive Part A for free.
As of 2026, if they have less than 30 quarters of credits, the premium for Part A will be $565 per month. That's an increase of $47 from last year.
The standard premium for Part B will be $202.90 per month in 2026. Combined, that's over $700 a month for each person. Honestly, I was a bit stunned when I saw these numbers.
So what do they do before the five years are up? This is when the insurance gap occurs. Just one visit to the emergency room during this time can lead to frightening bills, so it's important to prepare in advance.
If they live in California, the first place to look is Medi-Cal. California allows those who have been permanent residents for less than five years to qualify for full-scope Medi-Cal if they meet other conditions.
This is a program funded by the state government, and it's a really helpful system. I believe this is a role that the public sector should fulfill.
However, the conditions have tightened a bit starting this year. Beginning January 2026, there will be asset limits for Medi-Cal for seniors and disabled individuals.
The limit is $130,000 for individuals, and it increases by $65,000 for each additional household member. Typically, the home they live in is excluded from the asset calculation.
If the parents sold their house in Korea and came here, it's likely that their savings exceed this limit. In that case, Medi-Cal would be difficult to obtain. It's a good idea to review their bank balances before applying.
Also, check on dental coverage. Starting July 2026, some groups, including adults who have been permanent residents for less than five years, will lose Medi-Cal dental benefits.
The second option is Covered California, which is the Obamacare marketplace. Those who do not yet qualify for Medicare can purchase plans here even if they are over 65. They won't be denied coverage due to age.
Depending on their income, they may also qualify for premium tax credits. If the parents have little income from the U.S. aside from their Korean pension, how they report that income can significantly affect the outcome.
Starting in 2027, federal law will change, and some legal residents will no longer be eligible for marketplace subsidies. However, permanent residents will still be eligible for subsidies.
Under the same law, Medicare eligibility will also be narrowed to specific statuses like that of permanent residents. Parents who received their green cards through family sponsorship fall into this category, so there's no need to be overly worried.
One more thing to keep in mind is the Affidavit of Support, I-864, that the child signed when sponsoring them.
There is a notice that if they receive benefits like Medi-Cal, they may be asked to reimburse the sponsor for costs in certain cases. How this is applied can vary by case, so it's essential to consult an immigration attorney or the county office before applying.
As they approach the five-year mark, it's also crucial not to miss the deadline. The Medicare application period starts from the time they meet the residency requirement.
If they apply for Part B late, they may incur a lifetime late penalty. Before the five years are up, they won't have any eligibility, so there's no penalty, but that changes once they become eligible.
So, I would recommend marking the date they received their green card on the calendar. A few months before the five-year mark, I would schedule an appointment at the Social Security office.
To summarize: for the first five years, rely on Medi-Cal or Covered California.
If they have significant assets, lean towards the marketplace. As the five-year mark approaches, prepare for the Medicare application.
If they lack work credits, consider whether to purchase Part A or just enroll in Part B first.
All of this will vary based on the parents' income, assets, and residency history. Since individual situations differ, it's safest to confirm with a professional.
I believe that the decision to bring parents over is a tremendous act of love. I sincerely hope that this love doesn't get overshadowed by worries about hospital bills, and that you plan together well before their arrival.
 Stone94



 You Only Live Once |
 Texas Real Estate Blog |
 zentar |
 seouljung |
 AliAluAlo Blog |
 OC Real Estate Business Information |
 UNI Lover |
 Runner Kim |
 American Food Information & Calories |
 ringwinds |
 Hawaii Maui Kahului |
 calvorn |
 fernando park |
 newyorker 101 |
 coffeee |
 |
 Christopher |
 sylven |
 Sammy Beach |
 Bliss O |
 blue ocean |
 greenlight |
 Watanaka Karametibaksa |
 castle |
 xelton52 |
 carefree |
 vrixen73 |
 AZ Road Master |