
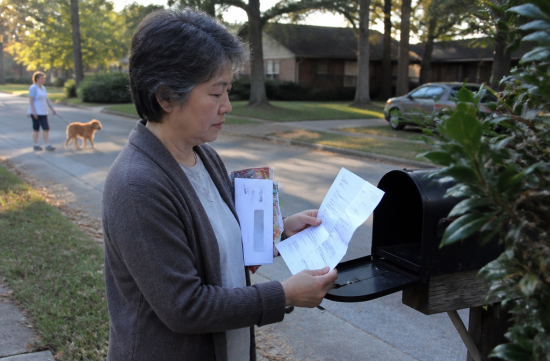
Last week, someone I know brought me an envelope. It was a letter from the insurance company stating that the Medicare Advantage Plan they are currently using will not be available in 2027.
They looked pale and asked, "So does that mean I will lose my insurance starting in January?"
To cut to the chase, the insurance won't completely disappear. The Medicare eligibility itself remains intact. However, if you do nothing, you could end up at a disadvantage, so I will outline the steps to take today.
Many people are receiving such letters these days. This fall, several major insurance companies announced they would be discontinuing Advantage Plans in certain counties starting in 2027.
According to federal regulations, insurance companies that do not renew their plans must notify subscribers at least 90 days before the termination date of December 31. Therefore, this non-renewal letter is expected to arrive by October 2.
First, you need to understand what happens if you do nothing. You will automatically revert to Original Medicare, which includes Part A and B, on January 1.
Hospital coverage will continue, so it's not an immediate crisis. The problem arises afterward.
If your previous plan included drug coverage, you will find yourself without Part D as soon as you switch to Original Medicare. This is a significant gap for those who take medication monthly.
Moreover, if you go without drug coverage for a certain period, you will incur a late enrollment penalty when you later sign up for Part D. This penalty follows you indefinitely, so it should not be taken lightly.
So, what are your options? It's much easier to think of them in two main categories.
The first option is to switch to another Medicare Advantage Plan. If you choose a plan that includes drug coverage, the Part D issue will be resolved as well.
The second option is to return to Original Medicare and take out a supplemental insurance known as Medigap along with a separate Part D plan. While this may cost more, it offers much greater freedom in choosing doctors.
Timing is also important. This year's Annual Enrollment Period runs from October 15 to December 7.
If you select a new plan during this period, coverage will begin seamlessly on January 1, 2027. This is the route I recommend.
If you miss the December 7 deadline, there is still a way. Those whose plans are discontinued will have a special enrollment period from December 8 until the end of February 2027.
However, if you enroll after January, there may be a gap in coverage. To ensure new coverage starts on January 1, you must make your decision by December 31.
One crucial point to highlight is the guaranteed issue right for Medigap. Normally, when applying for Medigap, your health status is considered, and you may be denied or face higher premiums.
However, those returning to Original Medicare due to plan termination are an exception. If you apply between 60 days before your existing coverage ends and 63 days after, the insurance company cannot deny you based on pre-existing conditions or charge you more.
This opportunity cannot be used if you switch to another Advantage Plan. Remember that this is a window that, once missed, is hard to return to.
Therefore, I see this letter as a good opportunity. If your health has declined compared to a few years ago, this is a rare chance to switch to Medigap without underwriting.
Conversely, if you are healthy and find the monthly premiums burdensome, another Advantage Plan may be more practical. The right choice varies from person to person.
When comparing plans, be sure to check three things: whether your current doctors and hospitals are in the network, whether your medications are on the plan's drug list, and what the annual out-of-pocket maximum is.
By entering the names of your medications into the Plan Finder on Medicare.gov, you can see the estimated annual costs for each plan. If you find the English language challenging, you can call 1-800-MEDICARE to request an interpreter.
If you live in Alabama, I also recommend SHIP counseling. This is a free service operated by the state's Department of Senior Services and local Area Agencies on Aging, and the number is 1-800-243-5463.
These counselors do not sell insurance. Therefore, I believe you can ask questions more comfortably than with agents who earn commissions.
Since this is a busy time, it's best to make an appointment before October 15. Having your letter, medication list, and insurance card handy during the call will help expedite the process.
Of course, the right choice may differ based on your health status and income, so be sure to consult with a professional advisor before making a final decision.
There's no need to be overly alarmed by a single letter. Just be sure to avoid putting it in a drawer and forgetting about it. Those who act before December 7 will ultimately face fewer disadvantages.
 AutumnMonica

 sparkling |
 oh my salami |
 saffronroute |
 You Only Live Once |
 Texas Real Estate Blog |
 Information on All Regions of the United States |

 Skyline |
 Alabama Bang |
 My Two Way |
 toastyfox |
 FLORIDA Acus |
 tracker |
 TONTON COFFEE |
 sunrise |
 ultron78 |
 uplifted |
 Folding Instructions |
 same same life |
 USA Hyundai Kia |
 morvex37 |
 BOL SA RAM |
 TOUCHE NEWS |
 Small Business Information USA |
 draxen |
 gallery |
 milkyotter |
 Zoom Zoom Zoom |
 Minnesota Lakes and Clouds |