
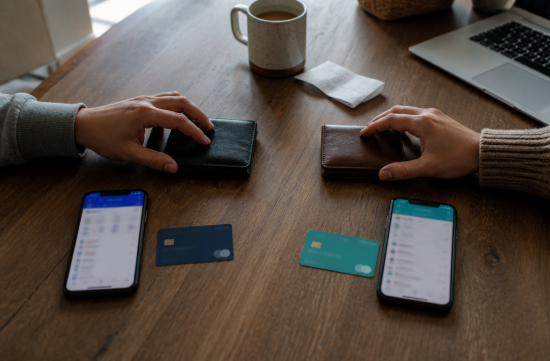
When talking with friends who are married in the U.S., a question that often comes up is whether they have combined their bank accounts. It's a question that assumes they would have, given that they are married, but the responses can be surprisingly varied.
In fact, many respond that they keep their finances separate. At first, I thought it might be due to relationship issues, but upon closer inspection, it seems that this trend is becoming more common in the U.S.
The statistics support this observation.
According to data from the U.S. Census Bureau tracking married couples' bank account types from 1996 to 2023, the percentage of couples who do not have a joint account at all has increased from 15 percent in 1996 to 23 percent in 2023. That's nearly one in four, which is not a small number.
The percentage of couples with at least one joint account has also decreased during the same period, from 85 percent to 77 percent. Over nearly 30 years, there has been a gradual but steady shift in this direction.
A recent survey by Bankrate highlights this trend even more clearly.
Sixty-two percent of couples reported that they manage at least some of their money separately, while less than 40 percent said they completely combine their finances.
When broken down by generation, the differences become even more pronounced. Among those in their early to mid-20s, 88 percent keep some money separate, while only about 52 percent of baby boomers do the same. The gap widens significantly with younger generations.
There are also interesting differences based on income levels. Among households earning less than $50,000 a year, 39 percent keep their accounts completely separate, while only 17 percent of households earning over $100,000 do the same.
This suggests that those with more financial stability are more likely to adopt a mixed approach, using both joint and individual accounts.
This trend may not solely be due to financial comfort; it could also reflect a belief that when there is a significant income disparity between partners, dividing expenses based on income ratios feels fairer than a strict 50/50 split.
The idea that couples must combine their finances upon marriage seems to be an outdated notion.
Curious about why this shift has occurred, I looked into it further, and one of the most noticeable reasons is the age at which people are getting married.
In 1996, the average age for women to marry for the first time was 24.8 years, and for men, it was 27.1 years. By 2023, those ages had risen to 28.4 and 30.2, respectively.
As people marry later, they often have already established their own credit cards, loans, and spending habits, leading them to feel less need to combine their finances.
Additionally, the strong individualistic culture in the U.S. cannot be overlooked. There is a prevailing sentiment that managing money is "my domain."
In Korea, merging finances is often seen as a symbol of trust, whereas in the U.S., maintaining separate accounts can be viewed as a sign of independence.
There are practical reasons as well. Keeping credit histories separate means that if one partner's credit score suffers, the other is less affected. If one partner has a record of late payments or bankruptcy, it won't automatically lower the other's credit card limits.
In the unfortunate event of divorce or separation, having separate accounts can make the process much cleaner. Those who have children from previous marriages or are remarrying often prefer to manage their assets separately from the start.
Some people even cite the surprisingly mundane reason that it's easier to calculate credit card expenses for birthday gifts or anniversary events without the other person knowing.
However, managing finances separately isn't always ideal.
In the same survey, only 12 percent of couples with joint accounts reported conflicts over money, while 15 percent of couples without joint accounts experienced conflicts. This result is somewhat contrary to the expectation that keeping finances completely separate would lead to fewer issues.
As a result, a growing trend is the mixed approach.
Shared expenses like rent, loan payments, and groceries are handled through a joint account, while the rest of the money remains in individual accounts.
The percentage of couples using this hybrid account model has nearly doubled from 9 percent in 1996 to 17 percent in 2023.
Nowadays, couples are increasingly using apps like Venmo or Splitwise to settle shared expenses without merging their accounts. This means that even without combining their bank accounts, the process of settling expenses has become more transparent.
On the other hand, completely merging accounts can lead to a situation where each partner's spending is visible in real-time, which can create a sense of fatigue as they feel the need to justify even small expenses.
Personally, I believe this hybrid approach is the most realistic.
I don't think whether or not to combine bank accounts is a measure of love.
Rather, having open and honest discussions about how each person spends money seems far more important than simply merging accounts. How couples share financial transparency may be what sustains their relationship in the long run.
 HeaterCat



 Korea Tiger News |
 Alpha and Omega World |
 Florida King |
 AH LALA |
 Victory 1988 |
 Sunny Fullerton |
 Until the Day It Gets Better |
 Agenda Center |
 calviro |
 Enjoying Samba at Home |
 Once in a Lifetime |
 novapixel |
 Banana |
 rouge88 |
 toffee |
 King County |
 DREAM BIG |
 Good News Good Thoughts |
 peelynew |
 Helpful Life Stories |
 chicpo |
 monorama tone |
 Kentucky Fried Chicken |
 bloomberg |
 morninpo |
 my town K blog |
 bravik31 |