
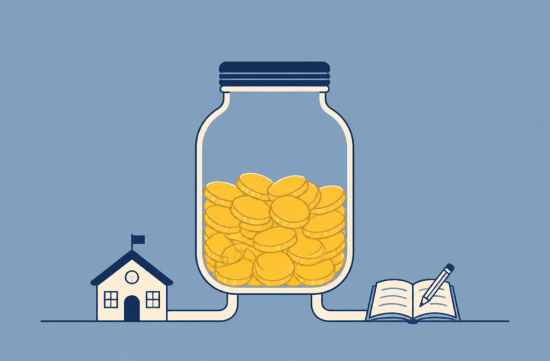
At five in the morning, while the coffee water was boiling, I sat at the table and unfolded this fall's tuition bill again. It was still dark outside, and the numbers stood out clearly at that hour.
These days, I often hear that you can pay up to $20,000 for private school tuition using a 529 account. They say it also covers tutoring expenses. Curious, I looked it up, and while it's true, there are quite a few conditions attached.
First, let's start with the big picture. The One Big Beautiful Bill Act, commonly referred to as OBBBA, signed on July 4, 2025, changed the 529 regulations.
Previously, the amount you could withdraw from a 529 for K-12 expenses was $10,000 per student per year. That only covered private school tuition.
With this new law, that limit has doubled to $20,000. This applies to withdrawals made after January 1, 2026.
So, if you pay for the fall semester of 2026 using a 529, it falls under the new limit. For tax purposes, it will be reflected in the tax return filed in the spring of next year for the 2026 tax year.
One thing that can be confusing is that the $20,000 is not per account but rather an annual total per student.
You can't spend $20,000 separately on tuition, tutoring, and textbooks. It means you can spend up to $20,000 total for all K-12 expenses in a year.
Now, let's move on to tutoring expenses. OBBBA also expanded the range of expenses recognized for K-12, and this part applies to expenditures made after July 5, 2025.
The new items include textbooks and course materials, online learning resources, tutoring, and fees for standardized tests like the SAT, ACT, and AP. Costs for dual enrollment courses for high school students are also included.
Educational therapies for students with disabilities are also eligible. This is likely great news for families in need.
However, not just any tutor qualifies. The tutor must not be a relative of the student.
There are also qualification requirements. The tutor must have a state teaching license, have taught or be teaching at an accredited school, or be an expert in the subject area.
So, if you're considering hiring a college student from the neighborhood for math tutoring, that might not qualify. Keeping receipts and the tutor's credentials will be helpful later on.
Now, here's something important from the perspective of someone living in North Carolina. Just because federal law has changed doesn't mean state tax law automatically follows suit.
North Carolina is a state that follows federal tax law (IRC) based on a specific date. Therefore, the state legislature must pass a separate law for the new regulations to be reflected.
Fortunately, Senate Bill 595 passed in July 2026, updating the state's federal tax law reference date to July 5, 2025. The summary of the state legislature's bill also includes provisions to allow the new educational expenses added by OBBBA to be used from 529 accounts.
Still, it would be wise to check with the NC 529 Plan or a tax professional to see if it applies to your situation. I would definitely make a call before making a withdrawal.
Another point to note is that North Carolina does not provide a state income tax deduction when you contribute to a 529.
Some other states offer a state tax deduction at the time of contribution, but our state does not have that benefit. Instead, if used for qualified expenses, withdrawals are exempt from both federal and state taxes.
This means that if you contribute this month and withdraw for tuition next month, the tax savings are almost nonexistent. The real benefit of a 529 comes from the tax-free growth of the money within the account.
Conversely, if you use the funds for non-qualified expenses, the earnings portion will be subject to income tax, and a 10% penalty may also apply. This is why it's important to carefully check the qualifications of the tutor.
Additionally, North Carolina has decided to participate in the new federal scholarship donation tax credit through HB 87 this year.
This is a system where you receive a federal tax deduction for donations made to scholarship granting organizations, separate from 529 plans. Families considering private school should keep an eye on this trend as well.
To summarize, the $20,000 limit starts in 2026, while tutoring and textbook expenses apply to expenditures made after July 5, 2025.
You need to keep track of tutor qualifications, save receipts, and calculate the limits yourself. For state tax issues, double-check before making a withdrawal.
Honestly, when I first heard the news, I thought my worries about private school tuition would be cut in half. But it turns out that you need to have saved money for it to be meaningful.
So, I believe it's better to contribute a little bit over time rather than withdrawing all at once when the child is older. Just like the trees on my morning walk, money that grows slowly is ultimately the most reliable.
 YuzuTeaSurf

 morvex37 |
 Ari Songhan American Immigration Life |
 Bearded Strawberry Smoothie |
 Heart Ticker |
 Duck Duck Go |
 Cohesive Kong |
 ORAVEZIN Oppa |
 North Carolina State University |

 Pierrot Jalang CPA |
 secure |
 Open Flex Mind |
 Hartford Blog |
 unified |
 Generation X |
 ringwinds |
 American Food Information & Calories |
 Hawaii Maui Kahului |
 calvorn |
 fernando park |
 newyorker 101 |
 coffeee |
 |
 Christopher |
 sylven |
 Sammy Beach |
 Bliss O |
 blue ocean |
 greenlight |
 Watanaka Karametibaksa |
 castle |