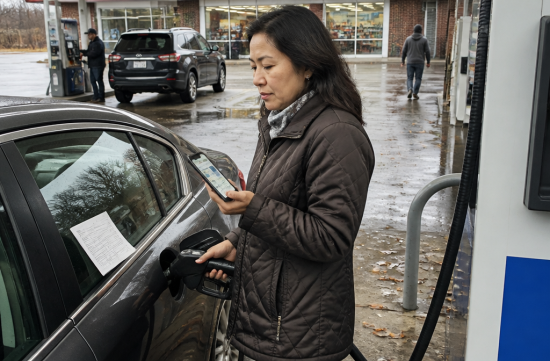
Last week, I opened the car insurance renewal notice and paused for a moment. There were no accidents or tickets, yet the premium had gone up again.
I wondered if I was the only one experiencing this, so I looked into it and found that the entire state of Connecticut is in the same situation. If you're in the New Haven area and facing year-end renewals, make sure to read this post to the end.
According to a mid-year report released by the insurance comparison site Insurify, the numbers are quite high. As of June, the average annual premium for full coverage in Connecticut was $2,652.
This is a 10.5% increase from January, and it was the largest increase among all 50 states for the first half of the year. Honestly, I didn't want to be number one in this regard.
The "4% increase at year-end" that is being discussed refers to the forecast for the second half of the year. Insurify predicts that it will rise by another 4.2%, bringing the average to $2,753 by December.
It's important not to get confused here. The 4.2% is a figure for the half-year, and when looking at the entire year, the projected increase for Connecticut is 14.7%, nearly reaching 15%.
The national average is expected to rise by only 1% this year, making the difference feel even larger. The national average actually dropped by 6% last year, so our state is going in the opposite direction.
According to a report by WFSB, by the end of the year, most drivers will be paying an additional $30 per month compared to the beginning of the year. Over a year, that's a significant amount of money.
This isn't just a one-time occurrence. Data from the state auditor's office shows that the average car insurance premium has increased by 11.2% in 2023 and is projected to rise by 8.9% in 2024.
So why is this happening? Insurify analyst Matt Brannon cites Connecticut's high vehicle repair costs as the main reason.
Modern cars have sensors and cameras even in the bumpers, making parts expensive. Additionally, the wages for repair technicians are higher than in other states, which means that the amount insurance companies pay out per accident has increased.
From a market principle perspective, it makes sense that costs are rising, leading to higher prices. However, it does feel unfair that this burden is being placed on drivers who haven't had any accidents.
So what can you do? I'll outline the steps I actually take before renewing. It's nothing complicated, and it only takes about 30 minutes.
First, open the declarations page of your renewal notice. Compare it with last year's amount to see which items have increased.
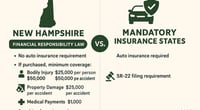
Second, check how your coverage limits compare to the state's minimum standards. In Connecticut, the minimum for bodily injury liability is $25,000 per person, $50,000 per accident, and $25,000 for property damage liability.
You also need uninsured and underinsured motorist coverage of at least $25,000 per person and $50,000 per accident. However, if you only carry the minimum limits, you may have to cover the difference out of pocket in the event of a major accident, so I would advise against cutting limits just to save on premiums.
Third, reassess your deductible. If you have a sufficient emergency fund, raising your collision deductible can often lower your premium.
Fourth, if your car is older, consider whether to keep collision and comprehensive coverage. If the annual premium is excessive compared to the car's value, dropping it may be a reasonable choice.
Fifth, ask about discounts one by one. Common examples include discounts for completing a defensive driving course, bundling home and auto insurance, and paperless billing.
Since discount names and conditions vary by company, it's best to directly ask, "Are there any additional discounts I might qualify for?" If you don't ask, they won't automatically offer them.
Sixth, get quotes from at least two or three companies. Even for the same coverage, different companies may cater to different types of drivers, leading to significant price differences.
When comparing quotes, make sure to match coverage limits and deductibles for them to be meaningful. If the conditions are different, a lower price may not actually be a better deal.
The state government also recommends using independent agents who can help you compare multiple companies. This method may be more convenient for those who find it daunting to communicate in English.
In an Insurify survey, 70% of drivers said they would have saved money if they had researched more. In fact, 30% of those who did research in advance successfully saved money, so it's worth the effort, even if it feels like a hassle.
Finally, mark your renewal date on your calendar. You should start comparing at least 2-3 weeks in advance to avoid rushing and ending up with an automatic renewal.
Just to note, the numbers mentioned today are based on analyses and forecasts from comparison sites, so they don't mean your premium will move exactly the same way. Results can vary significantly based on your driving record, vehicle type, and neighborhood.
If it were me, I would keep the limits the same during this renewal, adjust the deductible and discounts first, and only then seek quotes from other companies. This order feels much less regretful than cutting coverage to save money.
While we can't stop rising premiums, we don't have to passively accept them. I encourage you to pull out your documents this weekend and take a look.
 PuddingJungle


 Way to easy |
 holy cow |
 Soy Angelino |
 SKy Face |
 gleeful |
 My Heart Popper |
 Hagen |
 Lee Sang Don |
 Only Dentalbay |
 postcard |
 Buckwheat Muktudari Notebook |
 Kitchen Ideas |
 Jellia Angel |
 Victory 1988 |
 Rice Shop Uncle BLOG |
 ASURA |
 hot chocolate |
 rapids |
 Softember |
 mykiwi blog |
 Maria Mom |
 Watch for possible danger |
 northpeak |
 Far East Movement |
 Light of the World |
 mariashin |
 lavender |
 Bridgo |