These days, when I hear discussions about taxes from seniors around me, there's always a mention of Virginia's $12,000 deduction for those over 65. However, when they actually file, they find that the deduction isn't as much as they expected.
At first, I thought it was just a calculation error, but after checking the Virginia Department of Taxation's guidelines, the reason became quite clear. This deduction isn't given to everyone who meets the age requirement; it decreases based on income.
The Virginia Department of Taxation refers to this as the Age Deduction. It's an item that allows taxpayers aged 65 and over to deduct up to $12,000 from their income when calculating their main income tax.
If both spouses meet the age requirement, they can each claim up to $12,000, theoretically allowing for a total of $24,000. Just looking at the numbers, it seems like a substantial benefit.
However, this is where the birth date divides people into two groups. Those born on or before January 1, 1939, receive the full $12,000 regardless of income.
For those born after that date who are now over 65, the situation is different. Their deduction amount is calculated based on their income, and most retirees fall into this group.
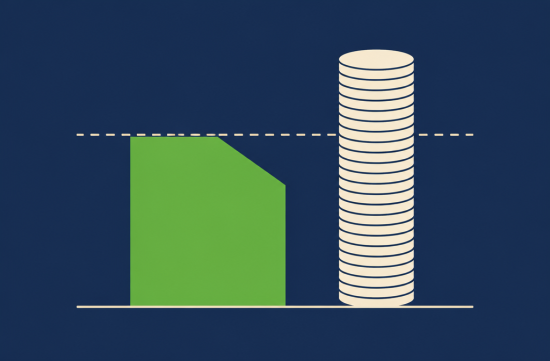
The reduction method is straightforward. For every dollar of income exceeding the threshold, the deduction decreases by one dollar.
The threshold is $50,000 for singles and $75,000 for couples. It's also worth noting that married individuals filing separately will still have their combined income assessed against the $75,000 threshold.
For example, if a single person has a threshold income of $56,000, they exceed the threshold by $6,000, so their deduction is halved from $12,000 to $6,000.
If the threshold income reaches $62,000, the excess amount is exactly $12,000, resulting in a deduction of $0. They meet the age requirement but receive no benefit at all.
The threshold income referred to here is known as AFAGI. It's the federal adjusted gross income minus the amounts of Social Security and Tier 1 Railroad Retirement benefits included in federal taxes.
This means that Social Security benefits are excluded from this calculation. Virginia also allows a deduction for the federally taxed Social Security amount from state taxes, so those who only receive pensions may find their tax burden lighter than expected.
The issue arises with other sources of income. Traditional IRA or 401(k) withdrawals, pension income, interest and dividends, capital gains from stock sales, and part-time earnings all contribute directly to AFAGI.
Particularly concerning are incomes that accumulate in a single year. Gains from selling a home or large amounts from a Roth conversion can cause the entire deduction to disappear in that year.
I was surprised to find that this threshold does not adjust for inflation. The figures of $50,000 and $75,000 have remained unchanged for a long time, meaning that as pensions gradually increase, the deduction quietly diminishes.
There have been proposals in the state legislature to raise the threshold. In 2020, there was a suggestion to increase the couple's threshold to $100,000, but it did not pass the committee.
In my opinion, considering $50,000 as a comfortable income in areas with high living costs, like DMV, seems unrealistic. Many retirees find themselves withdrawing more from their IRAs due to rising housing prices and insurance costs.
So, if it were me, I would try this approach. If my income fluctuates in the early years of retirement, I would stagger the timing and amounts of IRA withdrawals each year to avoid exceeding the threshold.
If a significant gain is expected, it's worth considering whether it can be spread out over multiple years. It's not a simple issue since it also involves federal taxes and Medicare premiums, but it's something to think about.
For couples, the calculations are a bit more complex. If both qualify, the combined deduction is reduced based on the couple's combined income, so following the calculation table in the Virginia Form 760 instructions is the most accurate method.
If only one spouse is over 65, the same combined income rule applies. If the other spouse is still working, their income can quickly reduce the deduction.
There are also overlaps with other deductions. Those receiving disability income can only choose between the age deduction and the disability deduction, so it's important to compare which is more beneficial.
Many also receive military retirement pensions. The military retirement income deduction is a separate item, and the tax department has indicated that you cannot receive overlapping deductions for the same income.
Additionally, the birthday criteria shift each year. The birth date recognized as 65 for that year's filing is listed in that year's form instructions, so be sure to check the correct year.
If you use tax software, most of these calculations are done automatically. However, if you enter the birth date or spouse information incorrectly, the deduction may not be applied at all, so it's a good idea to verify the Age Deduction amount on the results screen.
Ultimately, the key point is this: the $12,000 is just the maximum, and my deduction depends on how much my income, excluding Social Security, exceeds $50,000 or $75,000.
Taxes vary for each individual based on their income composition, so even with the same age, the outcomes can be completely different. Since it varies by personal circumstances, be sure to consult a tax advisor or financial expert before making withdrawal plans.
Understanding the structure beforehand and adjusting income flow is much more reassuring than being disappointed after expecting a deduction based solely on its name. Just reviewing last year's Form 760 before filing this year can provide valuable insights.
 SolidBridge73


 vivavida |
 MEDBIO American Doctor Blog |
 Burbank Lee |
 vibranto |
 sparkling |
 American Hardcore Band |
 lomira98 |
 Next Year, Let's Become Rich |
 berion88 |
 selvon |
 Mr Song Song |
 zonter88 |
 Let's Be Like a Salt-like City Person |
 Raymond K. |
 sunnyvale |
 Podongi Dad Blog |
 nexium |
 Washington Monument |
 dynamic |
 Key spots |
 berrypup |
 Yo Lock Me Up |
 Oh my Julia |
 bibigoo |
 silents |
 Team Korea Psychoanalysis Research |
 North Dakota Ragdoll Cat Owner |
 El Dorado |
 Cap Com |