
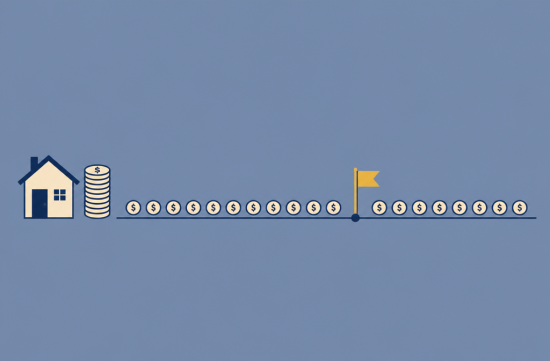
7.28%. This is the average interest rate for a 30-year fixed mortgage announced by Freddie Mac on October 1. It has risen from 7.03% just a week ago.
A year ago, the average was 6.34%, meaning it has jumped nearly 1 percentage point in just one year. Buyers are definitely feeling the impact.
With rates this high, the same question comes up during consultations: Can we buy points to lower the interest rate?
To put it simply, it can be beneficial or it can be a loss. The deciding factor is how long you plan to keep that house and that loan.
First, let's clarify the concept. Discount points are prepaid interest at closing.
One point equals 1% of the loan amount. If you borrow $500,000, one point costs $5,000.
So, how much will the interest rate drop? The industry commonly estimates about 0.25 percentage points for each point, but this is just a rough estimate.
The actual discount varies by lender and day. I've seen cases where the same one point only reduced the rate by 0.125%.
So, you need to do the math yourself. To get a clearer picture, let's assume a loan of $500,000, a 30-year fixed mortgage, with a base rate of 7.25%.
Under these conditions, the monthly principal and interest payment would be $3,411. This amount excludes taxes and insurance.
If you pay $5,000 to lower the rate to 7.00%, your monthly payment drops to $3,327. That's a savings of $84 per month.
You might feel that $84 is smaller than expected. When I first show this number, most people ask if that's all it is.
Calculating the break-even point is straightforward. You divide the cost of the points by the monthly savings. A simple calculator is all you need, and you can just plug in the numbers provided by the lender.
Dividing $5,000 by $84 gives you about 59 months. This means it will take nearly 5 years to recoup the cost.
If the same $5,000 only lowers the rate by 0.125%, the situation changes. The monthly savings drop to $42, and it would take 118 months, nearly 10 years, to break even.
Looking at the numbers, it's quite sobering. So, I don't agree with the notion that points are always beneficial. A small difference in the discount can double the break-even period.
The biggest variable is refinancing. Those who bought homes when rates were high often think about switching when rates drop.
If you refinance or sell before reaching the break-even point, the prepaid interest is lost. This is why points can be ambiguous in a high-rate environment like now.
On the other hand, if you plan to stay in the house for a long time and don't expect rates to drop significantly, buying points can make sense. You'll have a lower rate for the entire 30 years.
You also need to consider your cash situation. Sometimes it's better to use that $5,000 for a down payment or keep it as an emergency fund.
Especially right after moving, expenses for furniture, repairs, and various deposits can add up quickly. Keep in mind that this opportunity cost isn't factored into a simple break-even calculation.
There are also tax considerations. According to the IRS, points are considered prepaid interest and may be deductible if you itemize.
If it's a loan for a primary residence and meets certain criteria, the deduction can be taken in the year paid. Points paid during refinancing are usually deducted over the loan term.
However, if you take the standard deduction, you won't benefit from this. Tax treatment varies by individual circumstances, so be sure to check with a tax professional.
When getting estimates, there are specific areas to look at. According to CFPB guidelines, points are listed in Section A of the Loan Estimate page 2.
Legally, the points listed here must be tied to a rate reduction. Make sure there aren't any fees disguised as points.
When comparing lenders, don't just look at the interest rate; also consider the points and APR together. It's common for a seemingly low rate to come with two points hidden in the estimate.
There are also options in the opposite direction. You can slightly increase the rate and receive lender credits to reduce closing costs.
If you plan to refinance soon, this might actually be the more reasonable choice. If you're only going to use the rate for a short time, saving on initial costs makes more sense.
If you can negotiate seller credits on a property, you can use that money to buy points. For properties that haven't sold for a while, sellers may prefer this option over lowering the price.
I would recommend getting side-by-side estimates for zero and one point from two or three lenders on the same day. Only buy points if the break-even months are definitely shorter than the time you plan to keep the loan.
If there's even a slight chance of moving or refinancing within 5 years, I would choose to go without points. Remember, it's more about betting on time than buying a rate.
 HistoryProves



 garlic bread |
 Sugar Cream Door Bulletproof Noodles |
 urbanmint |
 |
 Premium Gas Camp |
 Tesla X |
 Next Year, Let's Become Rich |
 American Hardcore Band |
 Kondae Garusong Blog |
 Fairfax Fox |
 noraro |
 tervox95 |
 vale vale |
 yentra |
 Golden life |
 andrew park |
 Peter Pan Pet |
 Balan |
 Cali M Law Group |
 neroyo |
 Dreams Come True as Desired |
 Khan Film Blog Production |
 coloradoman |
 Living Economy Information Blog |
 rustley |
 Shim Ramen |
 Cool Beach Freeway |
 Mental Health Psychiatrist |
 element |