
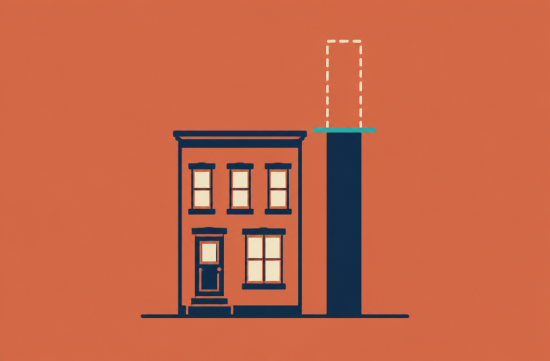
The property tax rate in Baltimore City is $2.248 for every $100 of assessed value. This is the highest level in Maryland, and the nominal tax rate has remained unchanged this year.
In places with such high rates, a small program can make a difference of hundreds of dollars each year. The Homestead Tax Credit is a prime example.
However, there are surprisingly many homes that qualify for this credit but have not submitted an application. Today, I will summarize that issue.
According to a WMAR report, the Maryland State Department of Assessments and Taxation (SDAT) revealed that out of 1,513,029 properties classified as residential, 487,739 have no applications. That's one in three homes.
Honestly, I was quite surprised when I first saw this number. Having worked in this field for a long time, I had often reminded my Korean clients about this.
The Homestead Credit does not freeze the value of your home. Instead, it sets a cap on how much the assessed value can increase each year, reducing the tax on the amount that exceeds that cap.
The state government sets the cap at 10%. Each county and city can set it lower, and Baltimore City has maintained a 4% cap since the early 1990s.
For reference, Howard County is at 5%, Prince George's County is at 3%, and Montgomery County remains at 10%. Even within Maryland, the level of protection varies significantly by region.
Let's look at some numbers. Here's a hypothetical example created to help with understanding.
Suppose a home had an assessed value of $200,000 last year and was reassessed to $230,000. With the 4% cap applied, this year's assessed value can only increase to $208,000.
Multiplying the $22,000 that exceeds the cap by the city tax rate of $2.248 results in a credit of $494.56. If no application is submitted, this amount must be paid in full.
At first glance, this may not seem like a lot for one year. However, in neighborhoods where assessed values continue to rise, this difference accumulates each year and grows larger.
The eligibility requirements are fairly simple. You must actually live in the residence, and you need to have lived there for at least six months, including July 1.
The credit applies to one property per person. Rental investment properties or second homes do not qualify.
If you try to claim it on multiple properties and get caught, you may face penalties. Those who own multiple investment properties should keep this in mind.
You only need to apply once per property. There's no need to reapply every year, and there are no income requirements.
However, if you buy or sell a home, the credit does not transfer. New homeowners must reapply based on their new property.
SDAT sends an application form by mail to new owners after registration, and since the 2021 law change, a copy of the application form is also provided at closing. It's quite common for this document to get lost in the paperwork.
Checking whether there is an application for your home is not difficult. You can select your county and enter your address on the SDAT property lookup page.
At the bottom of the page, look for the Homestead Application Status section. If it shows Approved or Application Received, there's nothing more to do.
If it says No Application, you should apply immediately. Online applications are the fastest, and you can also submit through the Maryland One Stop site.
The WMAR report stated that this credit generally does not apply retroactively, meaning benefits start from the year you apply. There are some exceptions for those over 70, so if that applies to you, it's advisable to check directly with SDAT.
For phone inquiries, the Baltimore area number is 410-767-2165, and for other Maryland areas, it's 1-866-650-8783.
One more change to note: the Baltimore City Council approved a proposal in June of this year to raise the Homestead cap from 4% to 5%.
The start date is the 2028 fiscal year. The city government initially proposed 6%, but the council adjusted it to 5%.
If the cap increases, the level of protection during rapid increases in assessed value will decrease accordingly. The city has stated that it will increase the target homeowner credit given to actual residents to lower the effective tax rate, so the actual impact on each household will need to be assessed individually.
I believe this change makes the decision to apply even more important. Regardless of how the cap changes, without an application, you receive no protection.
Take just five minutes to check your address on the SDAT site. It would also be beneficial to check your parents' or friends' homes as well. Since tax calculations vary by property, it's safer to confirm any ambiguous points with SDAT or a tax professional.
 ChocoMuffin



 moo moo |

 ultron78 |

 garlic bread |

 Sugar Cream Door Bulletproof Noodles |

 urbanmint |
 maryland park |
 Onion Ring |
 Good Karma |

 springw |
 Woooooah |
 frostpup |
 chocopup |
 Angeles Choi |
 My Heart Popper |
 comova |
 vintago |
 Sky Way |
 Top Beaches |
 folyfoly |
 ground |
 averagestudent |
 hot chocolate |
 SODA MAKER |
 james kim |
 All About Cars |
 lomira98 |
 calmbridge |
 oneonly |