
Last week, while working at a local café, I overheard a conversation between two elderly gentlemen at the next table. One mentioned that taxes apply to retirement income in Kentucky, while the other claimed that there are no taxes at all.
Both were partially correct, and I felt compelled to chime in. That night, I looked up Kentucky Department of Revenue materials and the relevant state statutes.
To get straight to the point, Kentucky allows a maximum of $31,110 in retirement income to be excluded from state income tax per person. This is referred to as the pension income exclusion, and it is calculated using a form called Schedule P when filing.
The eligibility criteria are broader than you might think. It includes not only company pensions and government pensions but also withdrawals from retirement accounts like 401(k)s, traditional IRAs, and annuities.
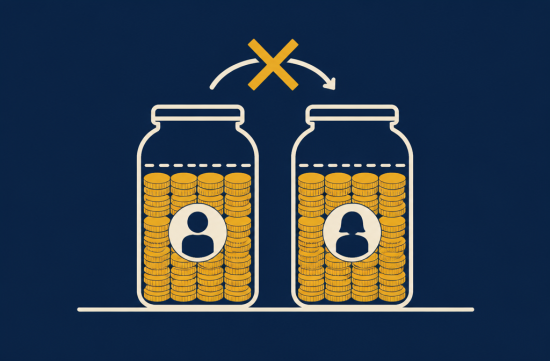
So, does this mean couples can double the exclusion? This is where caution is needed.
According to the Kentucky Department of Revenue's form instructions, taxpayers and their spouses must calculate their respective exclusions separately. This applies even if they file jointly; they combine the amounts they each calculated.
This means that if both individuals have retirement income exceeding $31,110, they can exclude up to $62,220 combined. However, if only one spouse receives a pension, the situation changes.
For example, if the husband receives a pension of $50,000 and the wife has no retirement income, only $31,110 can be excluded. The wife cannot use her share of the exclusion against the husband's pension.
Honestly, I was confused about this at first too. I thought that filing jointly would simply double the exclusion, but I realized it is based on individual limits.
Therefore, having retirement accounts in both names is quite meaningful in Kentucky. If there is money saved under each spouse's name, both can utilize their respective limits later on.
The tax rate also needs to be considered for calculations. Kentucky has a flat tax rate, which was reduced from 4% to 3.5% starting January 1, 2026, following the signing of House Bill 1 by the governor in February 2025.
Let's do a quick calculation. If someone receives a pension of $40,000, they would only pay taxes on the remaining $8,890 after excluding $31,110.
Multiplying that by 3.5% results in a state income tax of $311.15. Without the exclusion, it would have been $1,400, so the difference is significant.
If the limit is fully utilized, the state tax savings per person is $1,088.85. If both spouses fully utilize it, the total savings would be $2,177.70, which could cover a portion of annual property taxes.
Social Security is treated separately. Kentucky does not impose state income tax on Social Security benefits, so they are fully excluded regardless of the $31,110 limit.
In other words, Social Security is completely tax-free, while pension and retirement account withdrawals are tax-free up to the individual limit. Thinking of it this way makes it easier to understand.
If you are a retired public employee, there's one more thing to consider. Pensions from federal, Kentucky state, and local governments for service prior to January 1, 1998, can be excluded even if they exceed $31,110.
This part is calculated separately on Schedule P by noting the retirement date and length of service. Many people may qualify for this, and missing out on it would mean losing out on money.
For reference, this limit was originally $41,110. It has been reduced to the current amount since 2018, and a bill to raise it again in 2025 did not pass.
I don't lean politically toward either side. However, it is somewhat disappointing that while tax rates continue to decrease, the retirement income exclusion limit has remained unchanged for several years.
As inflation rises, the actual benefits are gradually diminishing. I hope discussions about tax rate reductions and adjustments to exclusion limits can happen together.
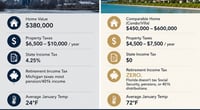
If you own a home, also consider property taxes. If you are 65 or older, the homestead exemption allows for a maximum deduction of $49,100 from the assessed value for the 2025 and 2026 tax years.
This is not related to income tax but must be applied for separately at the county property valuation administrator's office, commonly referred to as PVA. Once approved, you don't need to reapply every year, but you must reapply if you move.
Income for 2026 will be reported next spring, so now is a great time to get organized. Just confirming whose name the 1099-R pension statements come in is half the battle.
If I were you, I would organize a table with the names and expected withdrawal amounts for each retirement account before the end of the year. If everything is under one name, you can see if there are limits left over.
However, calculations can vary significantly based on the type of pension, work history, and income received from other states. Since it depends on individual circumstances, I recommend checking with a tax professional.
If I had shared this information with the gentlemen at the café, I think they both would have nodded in agreement. The one who thought he was paying a lot in taxes would likely find he pays less than expected, while the one who claimed he pays nothing would realize he is indeed paying taxes on the portion exceeding the limit.
 WildHorse

 MEDBIO American Doctor Blog |
 Burbank Lee |
 vibranto |

 sparkling |
 oh my salami |
 skyblue |
 Lightning Sikhye Cooking Method |
 The 2000 |
 vintago |
 Sky Way |
 Top Beaches |
 folyfoly |
 ground |
 averagestudent |
 hot chocolate |
 SODA MAKER |
 james kim |
 All About Cars |
 lomira98 |
 calmbridge |
 oneonly |
 Brighto |
 racuse |
 Total Beauty |
 crystal |
 Good Hotels |
 raspberry7 |
 Que que |