
This Thursday, starting October 15, new rates for California's FAIR Plan will take effect. The increase approved by the Department of Insurance (CDI) is an average of 29.1% across the state.
At first glance, the numbers seem daunting, but when you break it down, the situation varies significantly from home to home. Before you panic upon receiving your renewal notice, let's outline a few things to consider.
First, let's look at the background. The FAIR Plan is a state-level joint insurance pool for homes that have been denied coverage by regular insurance companies.
Previously, it was thought to only apply to a few high-risk wildfire areas. Now, the number of policyholders has exceeded 675,000, and this increase will affect all of them.
The initial proposed increase for the FAIR Plan was 35.8%. After review by the Department of Insurance, it was reduced to 29.1%, so it's worth noting that this is the adjusted figure.
Importantly, the 29.1% is just an average. The largest portion of the increase comes from the wildfire risk component of the premiums.
As a result, homes in high wildfire risk areas may see much larger increases than the average. Conversely, some policyholders in lower-risk areas may even see their premiums decrease.
This is true even in this neighborhood. Homes in the northern residential areas near the foothills and those in flat areas close to the freeway may receive different rates, even though they are in the same city.
Current policyholders will apply the new rates at the time of renewal after October 15. The first step is to check when your renewal date is.
The second thing to check is the wildfire mitigation discount. The FAIR Plan offers discounts on the wildfire portion of the premium if you have made your home and surroundings more fire-resistant.
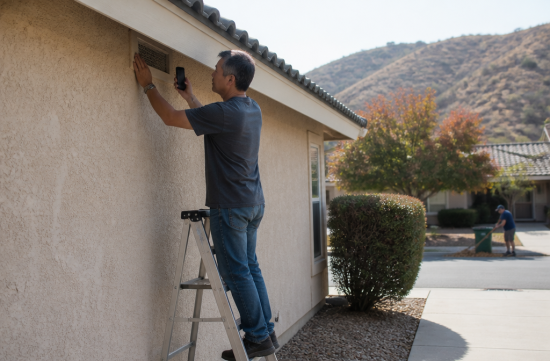
Eligible items include Class A roofing, enclosed eaves, ember-resistant vents, and double-pane windows. Keeping a 5-foot perimeter around your home clear of flammable materials and removing dry grass and leaves also qualifies.
The issue is that this discount does not apply automatically. You must apply for it and provide documentation such as photos or construction records for it to be considered.
Many people who replaced their roofs a few years ago have not submitted the necessary paperwork. Please gather receipts, contractor invoices, and before-and-after photos into one folder now.
The discount rate varies depending on which items you have. The most reliable way to find out the exact amount is to ask your agent or the FAIR Plan based on your address.
The third point is to review your coverage. The basic FAIR Plan homeowners policy primarily covers risks related to fire, lightning, and smoke damage.
It generally excludes water damage from theft or leaks, as well as liability. Therefore, many people opt for a supplemental insurance policy called DIC to fill these gaps.
If you only look at the FAIR Plan premiums, you may overlook the actual burden. You should consider the total annual amount, including the DIC renewal premium.
The fourth step is to get quotes from regular insurance companies again. Many people may not have looked into this in recent years as large insurers reduced new enrollments.
Recently, there have been reports that some insurers are reopening their doors following state insurance market reforms. Whether this is possible depends on your address and the condition of your home, but it doesn't cost anything to ask.
If you work with an independent agent, they can shop multiple companies at once. It's also fair to compare the total amount of the FAIR Plan and DIC side by side.
The fifth point applies to those with a mortgage. If your premiums are deducted from an escrow account, your monthly payment may increase during the next escrow analysis.
To avoid being surprised by a sudden increase in your monthly payment, it's a good idea to check with your mortgage servicer once the renewal amount is confirmed.
If you are renting out the property, there's an additional calculation. Since the premium is an operating expense, you need to factor the increase into your rental yield calculations.
If you don't understand the renewal amount or feel there's an issue with the process, you can contact the Department of Insurance. The consumer hotline is 800-927-4357.
From my perspective, having observed the market for a long time, insurance premiums have now become a variable that influences housing costs, following home prices and interest rates. In the past, insurance was often the last thing considered when buying a home, but that order has changed.
However, I do not recommend making hasty decisions like putting your home on the market solely because of this increase. It's not too late to check the numbers and consider discounts and alternatives before making a judgment.
If I were you, I would make sure to confirm the renewal date, organize discount documentation, and request quotes from agents—all within this week. Since insurance conditions vary by home, the final decision should be made in consultation with your agent.
The reference point is October 2026, and the rate information is based on announcements from the California Department of Insurance and the FAIR Plan. I want to reiterate that individual premiums will vary based on address and home condition.
 RubyShineFox



 garlic bread |
 Sugar Cream Door Bulletproof Noodles |
 urbanmint |
 |
 Premium Gas Camp |
 Star Way |
 CA Real Estate |
 Choi Cho |
 Lifestyle Information Search USA |
 Koreab Date |
 yolanda78 |
 Round and Round Children's Song Kingdom |
 Mia Flori |
 nova nova |
 healthy |
 leaves |
 sparkling |
 maryland park |
 persiste |
 conte |
 blueman |
 Going Once |
 Eldorado 88 |
 cherrydino |
 middlekick |
 Moscow Kim |
 nivex85 |